What Gold Backwardation Means: Rare Signal Hit 3 Times in 2025
Most investors focus on the spot price ticker. But gold and silver also trade across a curve of futures contracts. Occasionally that curve bends the other way: near-term contracts trade above longer-dated ones. When physical metal in hand is worth more than a promise to deliver it later, the market is in backwardation. This situation is uncommon in precious metals and deserves careful attention.
Key Takeaways
- Backwardation occurs when spot or the nearest futures month trades above longer-dated futures, reversing the normal cost-of-carry structure.
- It indicates that buyers are willing to pay a premium for metal now rather than later, often signaling tight physical supply or delivery bottlenecks.
- The clearest recent episode ran from December 2024 through February 2025, when tariff fears pushed the COMEX–London EFP spread to roughly $50–$60 per ounce and a record 151 tonnes of gold left London vaults for New York in one month [World Gold Council] [LBMA]. A second, larger EFP shock recurred in August 2025.
- Silver experienced an extreme episode in October 2025, when near-month futures traded about $2.88 above later contracts—the steepest backwardation in over 40 years—and London lease rates spiked to 39% [Benzinga].
- Backwardation is a stress signal for the physical market, not a guaranteed price forecast. It highlights the value of holding allocated physical metal rather than relying solely on paper claims.
What Is Gold Backwardation?
Gold backwardation is straightforward: the spot price—or the nearest futures contract—trades higher than contracts for delivery further out. Under normal conditions, futures rise for later months because storing, insuring, and financing physical metal costs money. That normal upward slope is called contango, which is the usual state for gold and silver.
Backwardation flips that relationship. When the curve is backwardated, buyers favor having metal now rather than holding a promise to receive it later. Exchanges and market educators describe this as spot trading above futures, and it typically reflects either unusually high near-term demand or constrained physical supply [CME Group]. In practice, backwardation often means someone urgently needs metal today more than they value a lower price in the future.
How Is Backwardation Different From Contango?
Contango and backwardation describe the same futures curve sloping in opposite directions. Contango reflects the normal cost of carrying metal forward: the basis—the gap between spot and futures—compensates holders for storage and financing and typically narrows toward expiry as futures and physical prices converge.
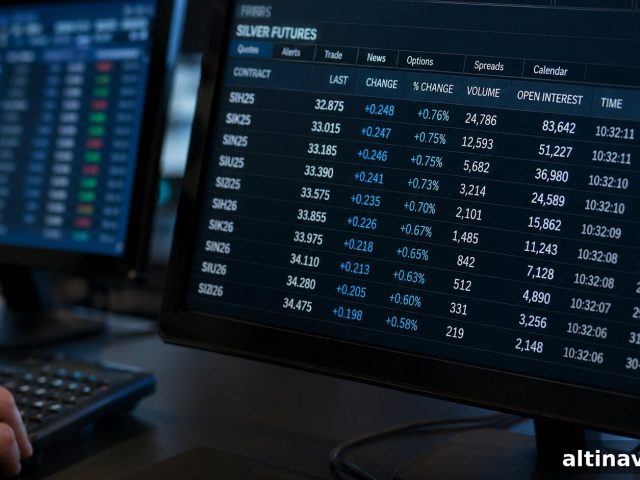
Backwardation breaks that pattern. Arbitrage strategies that buy spot and sell futures become less profitable or stop working because the premium for immediate metal outweighs the cost of waiting. When that happens, it signals a scramble for physical metal that overwhelms the usual carry economics.
Why Does Gold or Silver Go Into Backwardation?
Three factors typically appear together when backwardation emerges: first, a delivery or location bottleneck—bullion is concentrated in specific vaults and moving or recasting it takes time; second, a sudden shift in where buyers want the metal to be held; and third, spiking lease rates as the pool of lendable metal shrinks and borrowing costs surge.
The 2025 EFP Episode
From December 2024 through February 2025, all three conditions surfaced. Fears that U.S. tariffs might apply to imported bullion prompted buyers to move metal onto U.S. soil ahead of any levy. That demand widened the COMEX–London exchange-for-physical (EFP) spread to roughly $50–$60 per ounce [World Gold Council].
The World Gold Council traced how gold flowed: London bars moved through Swiss refineries, where 400-ounce bars were recast into the 100-ounce and one-kilogram bars required by COMEX contracts. The metal then traveled into New York vaults. LBMA data showed a record 151 tonnes leaving London vaults in January 2025, the steepest monthly outflow since the association began publishing vault data in 2016 [LBMA]. The premium eased only in April 2025 after the White House exempted gold bars from the broader tariff plans, and roughly 850 tonnes that had accumulated in New York began flowing back out [Reuters/Bloomberg via swissinfo.ch].
Technically, that episode was an EFP gap between exchanges rather than a textbook curve backwardation on a single exchange, but the market signal was the same: paper claims were priced below the metal itself, and the difference was reflected in dollar-per-ounce terms for anyone watching.
The August 2025 Repeat
A similar shock reappeared in August 2025. A report suggested U.S. Customs had reclassified Swiss one-kilogram and 100-ounce bars under a tariff-liable code, driving New York futures to a record above $3,530 an ounce and briefly pushing the premium over London spot past $125 per ounce. The premium eased after public clarification from the White House and subsequent guidance—illustrating how quickly uncertainty about transportability, not just permanent tariffs, can create acute short-term pressure [Reuters/Bloomberg via swissinfo.ch].
Silver’s Own Backwardation Episodes
Silver experienced a dramatic episode on October 9, 2025. The front-month COMEX contract traded roughly $2.88 above later months—the steepest backwardation in more than 40 years—and London lease rates spiked toward 39%, well above the typical sub-1% level [Benzinga]. London spot briefly exceeded $50 an ounce, outpacing COMEX futures. Exchanges responded by raising margin requirements as delivery stress intensified [Shanghai Metals Market].
Silver continued higher afterward, reaching a fresh all-time high near $121.62 an ounce on January 29, 2026 [CNBC]. Backwardation itself does not set a long-term price target, and silver retraced much of the intraday spike within days. Still, the curve flashed clear physical tightness well before the record—an important early signal for market participants.
Is Backwardation a Bullish Signal for Gold and Silver?
Backwardation is a signal of physical tightness, not a directional price forecast. It confirms that physical demand is outpacing what paper markets can comfortably deliver. When sustained, it often lines up with actual stress in the delivery and logistics system rather than routine contango dynamics driven by interest rates and storage costs.
Because backwardation appears only when the market’s plumbing—between vaults, refineries, and exchanges—is strained, it deserves attention from anyone who holds or considers holding physical metal. Checking the futures curve and exchange spreads reveals stresses that a simple spot-price watch would miss.
How Can Investors Use Backwardation Signals?
You don’t need to trade EFP spreads to benefit from watching them. Treat a widening EFP or a backwardated curve as a real-time health check on the physical market—similar to how bond traders monitor credit spreads without trading the underlying bond.
The practical takeaway is simple: when paper claims on metal trade at a discount to physical metal, that discount is meaningful. Futures contracts, ETF shares, and unallocated accounts are promises to deliver metal. In stressed conditions those promises may be harder to convert into physical metal quickly.
Owning allocated, physically segregated gold and silver removes that delivery-risk question entirely. When the metal is already in your vault account, labelled or segregated for you, there is no reliance on an exchange resolving a squeeze in your favor—the metal is already yours.
The Knowledge That Changes Everything
Two essential guides — free. Learn why gold matters and why fiat systems can fail under stress.
Stay On Top of Gold & Silver Prices
Get important market alerts sent straight to your inbox.
People Also Ask
Backwardation means the spot price or near-month futures price is higher than prices for later delivery months. It is the opposite of contango and indicates stronger near-term demand relative to later supply.
Backwardation in silver is episodic. The most severe recent episode occurred in October 2025. To know the current state, check live futures-curve data—past episodes do not guarantee present conditions.
Not necessarily a global shortage. Backwardation usually signals a location or delivery bottleneck: metal exists but is not moving quickly enough to where buyers need it, so they pay a premium for immediate delivery.
Yes. Backwardation can appear in any commodity market, including oil and metals, whenever near-term physical demand outstrips available supply. Gold’s backwardation is rarer because above-ground stocks are large relative to annual mine supply—so when it happens it attracts attention.
SOURCES
1. World Gold Council — You Asked, We Answered: Is the Threat of US Tariffs Moving the Gold Market? (February 2025)
2. London Bullion Market Association — London Vault Data (January 2025 data, reported February 2025)
3. CME Group — What Is Contango and Backwardation? (accessed September 2026)
4. swissinfo.ch (Reuters/Bloomberg) — New York Gold Futures Spike Over Spot Price After Tariff Shock (August 8, 2025)
5. Benzinga — Silver: How Record Backwardation Could Push The Metal Into Triple-Digit Zone (October 13, 2025)
6. Shanghai Metals Market — Overseas Markets Witness Rare “Squeeze Scenario with Futures-Spot Misalignment” as Silver Prices Surge Toward Historic Highs (October 12, 2025)
7. CNBC — Silver Hits New All-Time High as Precious Metal Surges Again (January 26, 2026)
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Past performance is not indicative of future results. Consult a qualified financial advisor before making investment decisions.
You May Also Like:
- A Bank Just Said the Fed Isn’t Done Hiking. Here’s the Math on What That Does to Gold.
- Gold Fell 23% This Year. One Number Explains Why.
- What Is the Debt-to-GDP Ratio, and What the US Number Tells You About Gold
- The World’s Last Zero-Rate Anchor Is Rising, and Gold Should Care
- What Is a FOMC Meeting? What the Fed Decides and How Gold Reacts
- Gold in Your Phone: How Much Gold Is in Electronics and What It Means for Demand
- Real Yields vs. Nominal Rates: The Number That Actually Moves Gold
- How to Read a Gold Spot Price Chart: The 4 Things That Actually Matter
Popular Topics
Picked from the archive
-
01
 Topics
Store Gold at Home Securely: Safes, Security and Insurance
-
02
Topics
Xi Arrives in Washington as Gold and Silver Tumble
-
03
Topics
Gold Near $4,330 as 70% Rate-Hike Odds Rise, China Intervenes
-
04
Topics
Five Major Institutions Issue Identical Warning on Gold Selloff
-
05
Topics
Silver vs Gold 2026-2031: 5-Year Investment Outlook
-
06
Topics
October Gold and Silver Selloff: Impact for Long-Term Holders
-
07
Topics
Federal Reserve Votes Wednesday: Track the Vote Tally
-
08
Topics
COMEX Silver First Notice Day: Key Events to Watch April 30