Why 72% of Family Offices Don’t Hold Gold: What They’re Missing
Key Takeaways
- About 72% of family offices surveyed in 2024–2025 report holding no gold at all.
- The barriers are largely psychological and structural rather than analytical — and they affect individual investors as well.
- The same cognitive biases that keep many family offices out of gold also cause most retirement savers to underweight it.
- Recognizing those biases is the first step toward making a reasoned allocation decision.
- The argument for gold rests on monetary forces, not popularity: currency debasement continues whether or not you accept it.
Here is a statistic that should make you stop and think.
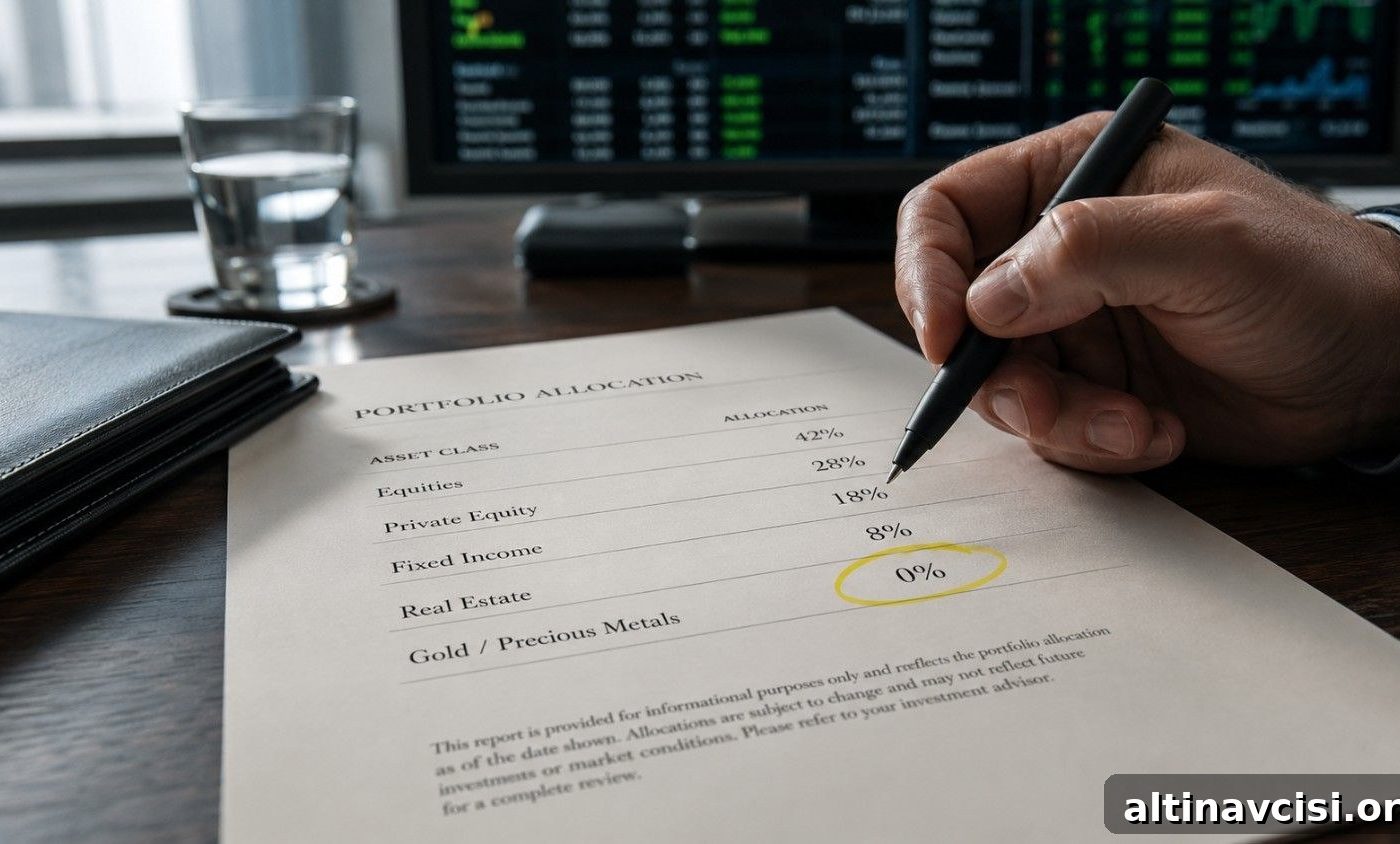
A major 2024 survey of global family offices found that roughly 72% reported no gold holdings at all. These firms — the private investment vehicles for some of the world’s wealthiest families — manage large pools of capital and employ teams of investment professionals. Yet nearly three in four of them have chosen, explicitly or implicitly, to leave gold out of their portfolios.
That choice is worth examining carefully. It isn’t proof that gold is a poor asset; rather, it reveals powerful social, institutional, and cognitive forces that shape allocation decisions. Those same forces influence individual investors, too. What many decision-makers overlook is that gold has preserved purchasing power across multiple decades and monetary regimes, and that its role does not depend on how many people believe in it.
Your Gold Buying Guide Many investors overpay when they buy physical gold and again when they sell. This guide explains what to own, why it matters, and how to avoid common mistakes.
Subscribe to receive a concise, practical guide to buying and holding gold.
Why Don’t Institutional Investors Own Gold?
At the core is a simple fact: mainstream institutional finance largely excludes gold from standard frameworks. Modern portfolio theory and conventional allocation models give gold no obvious role. It does not pay dividends, it earns no cash flow, and it resists valuation by discounted cash flow models. That absence inside the dominant models breeds skepticism.
Allocators operate within social and professional contexts. Proposing an allocation to gold can feel risky for career reasons: underperforming with equities is easier to explain than being the outlier who held gold as stocks rallied. This dynamic — often called career risk bias — nudges decision makers toward consensus positions, even when the consensus overlooks long-term structural risks.
“Gold doesn’t fit the model” is not an analytical statement; it’s an admission that the model excluded gold from the start.
Explaining an equity drawdown fits a large, familiar narrative. Defending a contrarian allocation to gold, by contrast, is a lonelier and less defensible conversation among peers.
How Does Recency Bias Keep Investors Out of Gold?
Recency bias plays a major role. Gold experienced a significant peak in 2011 and then fell substantially in the subsequent years, including a sharp decline in 2013. Those market losses are vivid memories for many allocators. When the most recent experience is a painful multi-year correction, that memory weighs heavily on future decisions.
Meanwhile, a prolonged equity bull market since 2009 has shaped expectations in the opposite direction. People who built their investing habits during long equity gains naturally overweight those results and underweight assets whose attractive properties show up in different scenarios.
Does Complexity Bias Work Against Gold?
Yes. Institutions reward complexity: private equity, hedge funds, and venture capital require deep analysis, documentation, and ongoing oversight, which justify teams and fees. Gold, by contrast, is straightforward: buy, hold, and secure. That simplicity can look less respectable to organizations built around specialized expertise.
The complexity trap is the tendency to undervalue simple solutions because they don’t showcase the skills a team was hired to provide. For a group steeped in complex deal-making, a cash-like, non-yielding asset feels out of place even when its historical role as a monetary store of value is relevant to long-term portfolio resilience.
Is Benchmarking Gold Against Private Equity a Fair Comparison?
Family offices often compare gold to their highest-returning holdings, like private equity or venture investments. When those assets produce outsized gains, an 8–12% annualized return from gold looks unimpressive. This is the opportunity cost illusion: the mistaken belief that owning gold means giving up something clearly superior.
But diversification is about how a whole portfolio behaves under stress, not about maximizing returns dollar-for-dollar during every market phase. Gold historically tends to hold or gain value during significant equity declines. Even a modest allocation that cushions a severe downturn can preserve wealth in ways that outperform chasing higher returns in good years.
The relevant question is not “what would gold return?” but “what happens to the portfolio if gold is missing?”
Does the Way Institutions Classify Gold Work Against It?
Structurally, many investment policy statements place gold in a commodities bucket alongside oil and agricultural products. That classification treats gold as a consumable or speculative commodity, which strips it of its distinct monetary properties before the asset is considered on its merits.
Analytically that is inaccurate. Gold has no meaningful industrial consumption relative to its above-ground stock; most of the gold ever mined still exists in vaults, jewelry, and electronics. Its historical role across civilizations has been monetary rather than consumptive. Lumping it with oil or wheat makes it harder for policy frameworks to recognize gold’s unique portfolio function.
What Do Family Office Biases Mean for Individual Investors?
The same biases affect retail investors, though they appear differently:
- Career risk becomes social pressure: holding gold while peers discuss booming equities can feel isolating.
- Recency bias: if you began investing during a long equity rally, gold may look like a poor performer based on recent memory alone.
- Perceived complexity: individuals may avoid owning physical gold because custody and storage seem complicated, while institutions avoid it because it’s too simple.
- Opportunity cost: short-term underperformance versus hot assets masks gold’s role as protection during severe market stress.
Does Monetary Debasement Make the Case for Gold Regardless of Investor Sentiment?
Yes. The monetary dynamics that make gold a durable store of value operate independently of investor opinion. Central banks and governments can increase the money supply, and political pressures often encourage spending beyond tax revenues. Over time, expanding money supplies reduce each currency unit’s purchasing power. That mechanism has been documented across modern monetary systems.
You don’t have to “believe” in gold to recognize that a portion of savings placed in a non-printable asset can serve a distinct purpose. Many investors who reach that conclusion choose a modest allocation to preserve purchasing power and diversify against systemic currency risk.
People Also Ask
Why do most family offices not invest in gold?
Psychological and institutional factors dominate: standard investment models omit gold, career risk discourages contrarian positions, and policy statements frequently classify gold as a commodity, limiting its consideration.
Is a 72% zero-gold allocation among family offices unusual?
It is notable. Given gold’s long monetary history and its role in portfolio diversification during extreme market stress, the statistic highlights how consensus frameworks and biases can push even sophisticated investors away from the metal.
What percentage of a portfolio should be in gold?
Many prudent frameworks suggest a starting point of 5–10% for meaningful protection, but the right allocation depends on your overall holdings, time horizon, and view of monetary risk. The goal is portfolio resilience, not maximizing short-term returns.
Does gold actually protect against inflation and currency debasement?
Historically, gold has maintained purchasing power better than many fiat currencies during extended periods of monetary expansion. That historical relationship supports its role as a hedge against currency debasement and inflationary pressures.
What is career risk bias and how does it affect gold allocation?
Career risk bias leads decision makers to favour positions that are defensible to peers. Because gold sits outside many mainstream narratives, it is harder to defend when it underperforms, which discourages allocations even when the asset could improve portfolio resilience.
The 72% Number Is an Opportunity, Not a Reassurance
It is tempting to conclude that if the world’s most sophisticated investors largely avoid gold, individuals should, too. In fact, the opposite reading can be more useful. When so many investors exclude an asset with a long monetary history during a period of accelerating monetary expansion, that gap may represent a window of opportunity rather than a signal of irrelevance.
The family offices that do hold gold have typically overcome the psychological and institutional obstacles that keep most portfolios exposed. Owning physical gold is not a bet on catastrophe; it is a strategic decision to add a non-printable, historically durable form of savings to a diversified portfolio.
If you decide to explore a position, begin by asking the clearest question: what could make gold a poor store of value over the next two decades, and is that mechanism actually in place? Most investors who answer honestly tend to allocate at least a modest portion of their savings to the metal.
Start by educating yourself and then decide whether a small, intentional allocation fits your overall plan.
Stay On Top of Gold & Silver Prices
Get important market alerts sent to your inbox.
Sign up to receive concise updates and price alerts. (Subscription form removed for clarity.)
SOURCES
1. UBS — Global Family Office Report 2024
2. Campden Wealth Research — Global Family Office Report 2025
3. London Bullion Market Association — Precious Metal Prices & Historical Data
4. World Gold Council — Gold Demand Trends Full Year 2024
5. Bank for International Settlements — Annual Economic Report 2024
6. Federal Reserve — H.6 Money Stock Measures
7. U.S. Bureau of Labor Statistics — Consumer Price Index
8. U.S. Treasury — Debt to the Penny
Disclaimer: This article is for informational and educational purposes only. It does not constitute investment advice. Consult a qualified financial adviser before making any investment decisions.
You may also like:
- Gold Remonetization: Six Forces Restoring Gold’s Monetary Role
- Silver Industrial Demand: Solar, EVs, and the Supply Gap
- Bank of America’s $6,000 Gold Forecast: A System Perspective
- Silver IRA Complete Guide: Rules, Limits, and Custodians Explained
- Silver’s Tesla Moment: The Solid-State Battery Thesis
- Physical Gold vs. Digital Gold: Which Is the Ultimate Safe Haven?
- BRICS Is Hoarding Gold: What It Means for Portfolios
- Gold to Oil Ratio: A Guide for Economic and Portfolio Analysis
Popular Topics
Picked from the archive
-
01
 Topics
5 Factors Driving Gold and Silver Prices Higher
-
02
Topics
US Treasury Yields Rise Ahead of Major Bond Auction
-
03
Topics
Gold Price Volatility Back to COVID-Era Levels
-
04
Topics
Gold Price Nears $3,700 Ahead of Fed Meeting
-
05
Topics
CPI 3.3% and GDP Stalling: Is 2026 Stagflation Coming?
-
06
Topics
Dollar Drops as Markets Price In Fed Cuts; Tariff Fears Rise
-
07
Topics
Why Turkey Sold Its Gold and What It Means for Sound Money
-
08
Topics
Gold Price Forecast: Oil Futures Diverge From Stocks