Why the SLV ETF Holds Your Silver but Won’t Return It
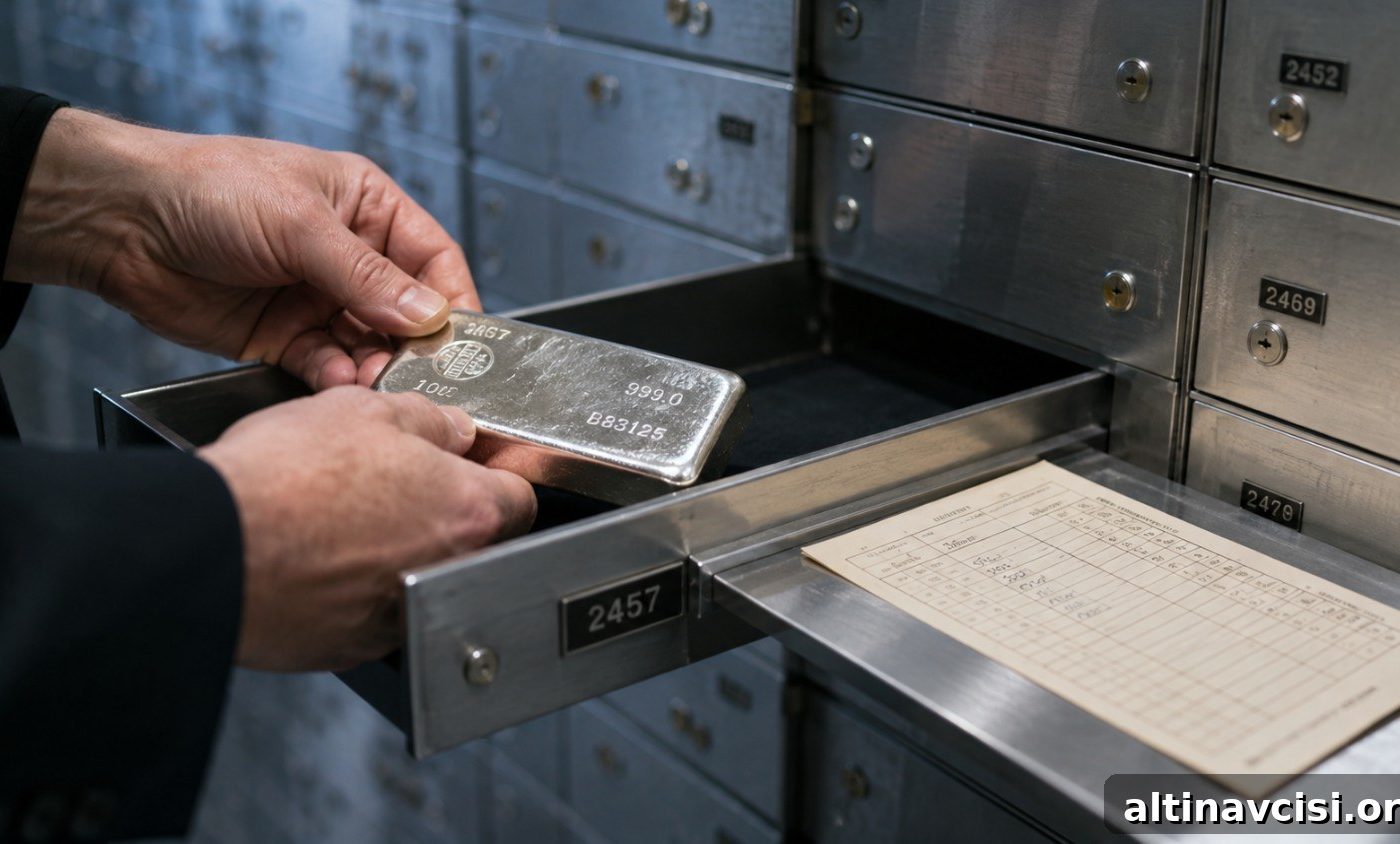
Key Takeaways
- SLV shareholders do not have a direct path to exchange individual shares for physical silver. Only Authorized Participants can redeem or create SLV shares in large Baskets of 50,000 shares, a threshold most investors never meet on their own.
- Sprott’s PSLV operates as an allocated, closed-end trust. Qualified unitholders who meet a minimum (about 10,000 ounces) can redeem units for serialized, allocated silver bars held at the Royal Canadian Mint.
- As of August 25, 2026, COMEX registered silver totaled 99.2 million ounces while open September contracts implied 129.9 million ounces of potential delivery. That yields a coverage ratio near 17.4%, a level market participants generally classify as “tight.”
- The meaningful difference between SLV and allocated vehicles like PSLV is legal and operational: SLV holders own a beneficial interest in a pooled trust, while PSLV unitholders can claim specific, redeemable bars.
- Silver experienced a supply deficit every year from 2021 through 2025. Industrial demand—driven by solar, electronics and AI-related hardware—now accounts for roughly 58% of total silver demand, according to the Silver Institute’s 2026 survey.
Many sophisticated investors are moving some silver exposure away from SLV, the largest silver ETF, toward allocated structures such as Sprott’s PSLV. The shift is not driven by sentiment alone but by the legal and operational differences between products. SLV issues shares that represent a fractional beneficial interest in a pooled trust; only large, registered Authorized Participants can convert those shares into physical metal in 50,000-share increments. By contrast, PSLV holds serialized, allocated bars and allows qualifying unitholders to redeem units for specific bars. With COMEX deliverable inventories tight heading into September, that distinction has real practical value and is influencing institutional positioning.
Why Are Institutions Choosing Allocated Silver Over SLV?
Silver prices reached near-record levels in January 2026 and then retreated, with much of the fluctuation following broader precious-metals moves linked to Federal Reserve policy. Beneath headline price action, institutional holders have been reassessing how they want exposure to physical metal. The choice increasingly centers on legal ownership and redemption mechanics rather than short-term trading convenience.
SLV remains the largest silver ETF by assets. As of Q2 2026, SLV reported net assets of $28.19 billion and approximately 530.3 million shares outstanding, down from 542.0 million at the end of Q1. PSLV is smaller but expanding: it reported holding 215.4 million ounces of silver as of July 31, 2026, and Sprott expanded PSLV’s at-the-market issuance capacity in January 2026 to support additional physical purchases.
These issuance and redemption patterns highlight the core decision investors face: do you want a claim on a large pooled trust, or do you prefer a structure that offers direct, serialized redemptions? For many long-horizon institutions, the latter is increasingly attractive.
The Knowledge That Changes Everything
Two essential guides — yours free. Understand why gold matters and why fiat currencies have historically lost purchasing power.
Why Does the Redemption Structure of a Silver ETF Matter?
When investors buy shares in a silver ETF, they face one practical question: if I want the metal itself, how can I convert my position into physical silver? Different funds answer that question in fundamentally different ways, and the legal form of ownership matters during stress events or delivery squeezes.
SLV’s regulatory filings show a narrow operational model: redemption is limited to Baskets of 50,000 shares and only registered Authorized Participants may create or redeem those Baskets. Authorized Participants are typically large banks and market makers, not retail investors and often not even smaller institutional accounts. SLV holders therefore own a fractional beneficial interest in a pooled trust rather than title to specific bars. That beneficial interest trades on exchanges and may not always track the trust’s net asset value exactly.
PSLV follows a different model. Sprott describes PSLV as holding fully allocated, serialized London Good Delivery silver bars custodied at the Royal Canadian Mint. Qualified unitholders who meet the trust’s minimum — roughly 10,000 ounces — can redeem units for specific bars, on a monthly schedule. That right expands the set of investors who can access physical metal directly compared with SLV’s Basket-only mechanism, and it is the central structural distinction many investors care about.
A common retail claim is that SLV’s custodian can lease or lend the fund’s silver to short sellers. SLV’s governing documents reject that claim: BlackRock stated in a 2011 SEC filing that leasing is not permitted under SLV’s prospectus and that the custodian holds metal without legal title to use as its own. Thus, the primary difference is not leasing but how ownership and redemption rights are structured.
What Is Rehypothecation and Why Do Investors Worry About It?
Rehypothecation occurs when a custodian reuses client assets as collateral for its own borrowing or trading. That risk is most relevant to unallocated metal accounts, where clients hold a claim against a pool of metal rather than title to specific bars. Allocated metal—where bars are serialized and held in a client’s name—cannot legally be rehypothecated under typical custody agreements.
The 2011 MF Global collapse is a cautionary example: clients holding clearly allocated metal fared better than those in unallocated or leveraged positions. This difference underpins why many investors focus on redemption rights and allocation, not on speculative claims about leasing.
How Tight Is the Physical Silver Market Right Now?
Physical availability matters for redemption decisions. On August 25, 2026, COMEX-registered (deliverable) silver in approved warehouses stood at 99.2 million ounces, with an additional 239.1 million ounces classified as eligible but not warranted into the deliverable pool. At the same time, open September futures contracts implied about 129.9 million ounces of potential delivery. That produces a registered-stock coverage ratio of roughly 17.4%, a level industry participants typically describe as “tight.”
Total open interest across all COMEX silver contracts converted to ounces was about 5.7 times registered inventory at that date, a measure often called “paper leverage.” Most contracts, however, settle financially rather than by physical delivery, which is why paper and physical figures can diverge.
Does Silver’s Supply Deficit Make This Structural, Not Temporary?
COMEX tightness matters more when it sits atop a persistent supply trend. Silver recorded annual supply deficits from 2021 through 2025, meaning mine output plus recycling fell short of total demand each year. Industrial demand now accounts for roughly 58% of total consumption—driven by solar panels, electronics and hardware used in data centers and AI infrastructure—demand that is relatively insensitive to short-term price moves compared with jewelry or coins. For institutions building long-term allocations, a structural deficit elevates the importance of having a clear legal claim to physical metal.
What Should an Investor Take Away From the SLV-to-Allocated Shift?
SLV remains a highly liquid vehicle well suited for traders and investors who prioritize easy entry and exit. Its trading volume and market depth are advantages for shorter holding periods. But for long-horizon investors—pension funds, endowments, family offices—the legal form of ownership and the ability to redeem for specific bars can be decisive. For these investors, an allocated, redeemable structure reduces counterparty exposure and offers a clearer path to physical metal if delivery markets tighten.
Even an allocated ETF is one step removed from holding silver directly in an investor’s own name. Those who conclude redemption rights matter next ask where and how to hold metal outside of a fund—secure vaults, independent audits, and insured custody arrangements become the focus once a decision to take physical delivery is made.
Stay On Top of Gold & Silver Prices
Get important market alerts delivered to your inbox.
People Also Ask
Can SLV shareholders redeem their shares for physical silver?
No. SLV permits redemption only in 50,000-share Baskets and only through registered Authorized Participants, who are usually large banks and market makers. Individual shareholders and most institutions therefore hold a beneficial interest in the trust rather than a direct claim to specific bars.
Does SLV lease its silver to short sellers?
No. SLV’s prospectus and related SEC filings state that leasing the trust’s silver is not permitted under its legal structure, and the custodian holds the metal without rights to repurpose it as its own collateral.
What makes PSLV different from SLV?
PSLV is a closed-end trust that holds allocated, serialized silver bars at the Royal Canadian Mint. Qualifying unitholders can redeem units for specific bars, subject to PSLV’s minimums and redemption terms, which differ from SLV’s Basket model.
What is the difference between allocated and unallocated silver?
Allocated silver means specific, serialized bars held in custody under a client’s name and not available for the custodian to reuse. Unallocated silver represents a claim on a pool of metal and carries rehypothecation risk because the account holder does not own specific bars.
How tight is the COMEX silver market in 2026?
On August 25, 2026, COMEX-registered (deliverable) silver was about 99.2 million ounces. Open September contracts implied roughly 129.9 million ounces of potential delivery exposure, producing a registered-coverage ratio near 17.4%, a level commonly described as tight by market participants.
Why has silver run a supply deficit for six straight years?
From 2021 through 2025, total demand exceeded mine supply plus recycling each year. Industrial demand now accounts for about 58% of consumption—driven by solar, electronics and AI-related hardware—which tends to be less price-sensitive than jewelry or coin demand.
SOURCES
1. SEC EDGAR — iShares Silver Trust filings (Q2 2026 10-Q; redemption structure; 2011 leasing clarification)
2. Sprott Asset Management — Sprott Physical Silver Trust (PSLV) materials
3. Sprott Asset Management — PSLV redemption and custody descriptions
4. CME Group — COMEX Silver Warehouse Stocks Report
5. World Silver Survey 2026, Silver Institute
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Past performance is not indicative of future results. Always consult a qualified financial advisor before making investment decisions.
You May Also Like:
- What Are the IRS Rules for a Precious Metals IRA in 2026?
- Why Your Pension Can Own Gold and Your 401(k) Still Can’t
- Central Bank Gold Custody: Where Nations Store Gold
- Permanent Portfolio: Harry Browne’s 25% Gold Rule
- Australian Gold Kangaroo: The Bullion Coin Backed by an Act of Parliament
- What Is Sound Money? Why the Dollar Lost 87% of Its Value Since 1971
- Vault Storage vs. Gold ETFs: Who Owns the Gold You Paid For?
- Silver Price Outlook August 2026: Down 47% and Barely Owned
- What Does an Inverted Yield Curve Mean for Gold Prices — and How Do You Use It?
Popular Topics
Picked from the archive
-
01
 Topics
Fed’s September Shift: Impact on Gold Prices
-
02
Topics
5 Catalysts That Moved Gold and Silver This Week
-
03
Topics
Gold Price Tops $5,200, Silver $90 as Inflation Persists
-
04
Topics
Sound Money: Why the Dollar Has Lost 87% Since 1971
-
05
Topics
Gold Price Volatility Back to COVID-Era Levels
-
06
Topics
Gold Jumps 1% – Why July CPI Matters More Than the Headline
-
07
Topics
Why Gold Holds Value: The 5,000-Year Truth Investors Miss
-
08
Topics
Fed Decision Looms: Gold Poised for 8:30 AM Reaction