Gold Speculative Traders Hit 60-Week High, Few Buyers
Gold’s speculative crowd is the largest it has been in 60 weeks, but that reading is misleading. The Commodity Futures Trading Commission’s Commitments of Traders report for positions as of August 11 shows large speculators’ net long reached 54.44% of open interest. Yet gross long positions remained below the 60-week median. In short, the apparent crowd grew because sellers left the market rather than because buyers aggressively piled in.
As of Friday, August 21, 2026, Gold trades at $4,591.45, up 1.60% on the day and 4.91% on the week. Silver sits at $69.16, up 1.53% on the day and 6.89% on the week. Why has silver outperformed gold this week? The positioning data helps explain the difference.
Key takeaways
- Silver rose faster than gold this week, yet its speculative net length ranked 47th of the past 60 weeks on August 11. Gold’s net length hit a 60-week high at 54.44% of open interest.
- Gold’s 60-week high resulted from departing shorts rather than unusually large long buying. Gross longs were below the 60-week median, while gross shorts were unusually thin — roughly 64% of their median.
- Positioning data describes leverage and one-sidedness in the paper futures market. Physical holdings and industrial demand operate outside this mechanism.
Why gold’s 60-week high is not necessarily a buying signal
First, how the measure works: crowding is net speculative length divided by open interest, not the raw number of contracts. Open interest varies, so expressing net length as a share of open interest normalizes for market size and reveals how one-sided positioning actually is. The CFTC figures referenced here reflect positions as of August 11, so they are several days old when released.
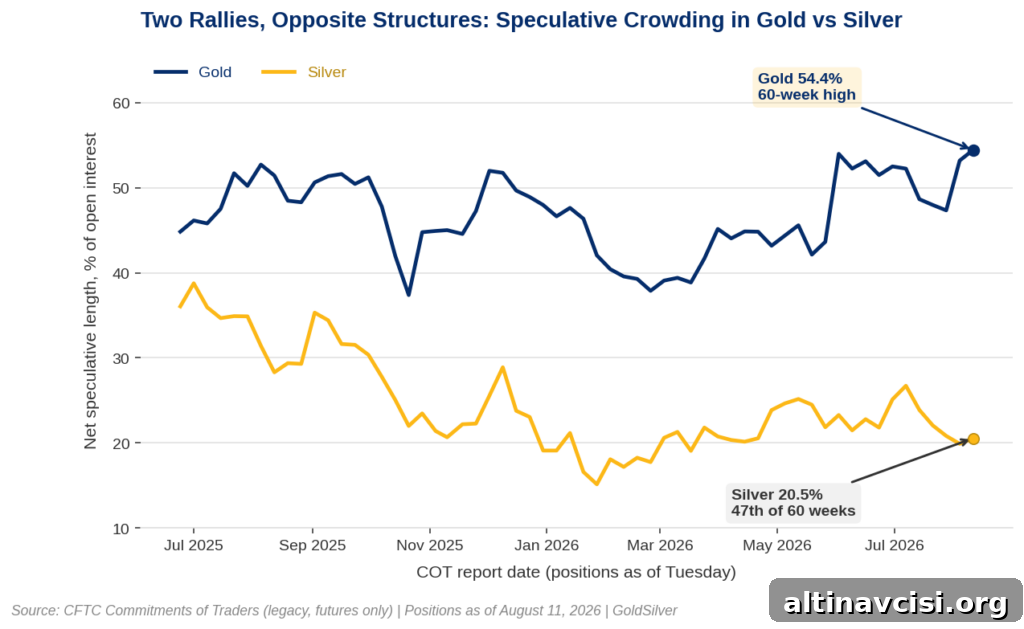
On August 11, non-commercial (speculative) traders held a net long of 217,940 contracts in gold while open interest was 400,309 contracts — hence the 54.44% reading. That was the highest percentage in the 60-week dataset, but it beat the prior peak by only 0.45 percentage points. A marginal high like that does not indicate a regime change.
More important is the composition behind the net number. Gross longs were 250,936 contracts, slightly below the 60-week median of 253,558 and ranking 33rd of 60 weeks. Speculators were not especially long. The change that produced the high net reading was a reduction in gross shorts, which were 32,996 contracts against a 60-week median of 51,716 — about 64% of their typical level. In other words, the short side thinned, lifting net length as a share of open interest.
What is the short-covering cushion?
Short positions are closed by buying, so gross short open interest represents standing buying power that will automatically trigger if prices fall. That short-covering demand acts as a shock absorber under a declining market and tends to cushion price moves. When gross shorts thin relative to their history, the automatic bid weakens. Declines that would normally be absorbed can instead become forced liquidations, producing sharper price drops. This dynamic is about the paper futures market; it says nothing directly about physical supply or industrial demand for the metal itself.
Why is silver rising while speculators largely stay on the sidelines?
Silver’s positioning looks different. On August 11, silver’s net speculative length was 20.54% of open interest, ranking 47th of 60 weeks and only 53% of its 38.76% peak from the week of July 1, 2025. Gross longs ranked mid-pack at 34th of 60 weeks. The short side provides the contrast: gross shorts were 15,629 contracts versus a 60-week median of 17,932, or about 87% of normal. That means silver’s short-covering cushion remains more intact than gold’s.
Silver outpaced gold by about 1.98 percentage points this week, which is not unusual given silver’s smaller size and greater volatility. What matters is that silver moved with less one-sided futures leverage behind it. Thin speculative positioning is not inherently bullish; it can also reflect professional traders’ skepticism. Low positioning may persist for months, so it’s a signal of fragility or room to move, not a directional forecast.
What this means for owners of physical metal
Futures positioning describes the paper market and does not capture all demand channels. Physically backed exchange-traded funds and industrial buyers transact in metal without appearing in the Commitments of Traders report. For example, iShares reported that the iShares Silver Trust held 15,275.59 tonnes as of August 19. The Silver Institute’s World Silver Survey 2026, published April 15, 2026, estimated industrial demand at 657.4 million ounces — roughly 58% of total demand — and noted a sixth consecutive year with a supply deficit. Those physical channels don’t show up in CFTC positioning data.
A leveraged unwind in futures can push the quoted price down sharply even when physical stocks remain unchanged, because futures set the benchmark market price. A holder of allocated physical metal has no margin calls and cannot be forced to sell; the quoted price may move, but the ounces remain in storage. That distinction matters when interpreting short-term price moves driven by paper-market dynamics.
Why these two rallies are not the same trade
Both metals rallied this week amid a softer dollar and easing yields, which explains direction but not structural resilience. Beneath the headline move, the rallies have opposite mechanics. Gold’s gain sits on a short book that was thin — around 64% of its median on August 11 — meaning its mechanical cushion is reduced. Silver, by contrast, remains far below its record high (about $121 on January 29, 2026) and still has a more intact short-side cushion. That difference means gold may be more vulnerable to a sharp unwind driven by its futures positioning, while silver’s mechanics currently offer more built-in support.
The next Commitments of Traders release for positions as of August 18 is due at 3:30 p.m. Eastern. For traders and observers, gross shorts — not just net length — will be the key figure to watch.
Stay on Top of Gold & Silver Prices
Sign up for alerts to receive timely market updates and price movements.
Frequently asked questions
The Commitments of Traders report is a weekly disclosure by the U.S. Commodity Futures Trading Commission that shows how open interest in futures markets is split among trader categories. It is published every Friday at 3:30 p.m. Eastern and reflects positions held the prior Tuesday, so the data is always several days old on release. The legacy report groups positions into non-commercial (speculative), commercial, and non-reportable categories.
Open interest changes over time. A net long of a given contract count means different things in a small market versus a large one. Expressing net speculative length as a percentage of open interest normalizes for market size and reveals how one-sided positioning really is. That’s why a net percentage can look extreme even when gross longs are ordinary.
Gross shorts are the total short contracts outstanding before netting against longs. They matter because shorts are closed by buying; that pool of short interest provides automatic demand if prices fall. When gross shorts are thin relative to history, the market’s short-covering cushion weakens and declines can become self-reinforcing liquidations rather than orderly repricing.
No. Light positioning indicates a less crowded futures market, which can mean either that the market has room to attract buyers or that professionals remain unconvinced. Positioning data helps assess fragility and leverage risk, but it is not a directional forecast.
Because the futures market is only one channel of demand. Physical ETFs, industrial users, and other buyers transact outside the CFTC’s report. For example, the iShares Silver Trust reported large holdings and the Silver Institute reports sustained industrial demand, neither of which appears in positioning data.
When leveraged futures positions unwind, the quoted price can fall quickly since futures set the benchmark. But holders of allocated physical metal face no margin calls and cannot be forced to sell. The price may move, yet the physical ounces remain unchanged in storage.
SOURCES
1. U.S. Commodity Futures Trading Commission — Commitments of Traders, positions as of August 11, 2026, released August 14, 2026
2. iShares — iShares Silver Trust (SLV) Fund Disclosure, holdings as of August 19, 2026
3. The Silver Institute — World Silver Survey 2026, published April 15, 2026
4. GoldSilver — Live Gold Price Chart, accessed August 21, 2026
5. GoldSilver — Live Silver Price Chart, accessed August 21, 2026
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Past performance is not indicative of future results. Always consult a qualified financial advisor before making investment decisions.
You may also like:
- Gold hit a three-month high. Silver hit a two-month high. One story connects them.
- The national debt reached $40 trillion. Jefferies turned bullish on gold.
- Gold fell and silver rose on the same report. Here is the mechanism.
- Geopolitical developments barely moved gold. Here’s why.
- Gold’s pullback wasn’t about ETFs. It was about a Treasury buyback.
- The Fed confirmed a key split in its minutes. Then it said something bigger.
Popular Topics
Picked from the archive
-
01
 Topics
Gold Prices Stabilize Amid Saudi-Iran Tensions
-
02
Topics
Why Gold Held Steady After Trump’s Economic Pressure on Iran
-
03
Topics
Oil Drops 11% as Gold Rises: What Investors Need to Know
-
04
Topics
3 Questions Investors Must Ask Before Buying Any Asset in 2026
-
05
Topics
Silver Surges Past $70 Amid Conflicting GDP Data
-
06
Topics
What’s Moving Gold and Silver Prices This Week
-
07
Topics
How FOMC Minutes and Jackson Hole Could Move Gold
-
08
Topics
Two Investors Ran Debt Math Separately and Chose 15 Percent Gold