Manufacturing Hits Strongest Month of 2026 as Gold Plunges
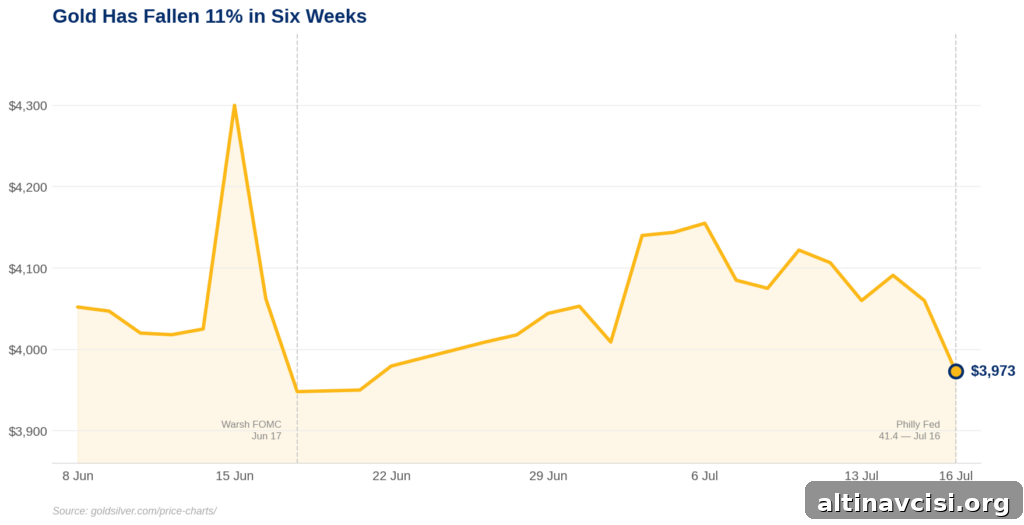
Gold fell 2.2% on Thursday, July 16, 2026, sliding to $3,973 per ounce after U.S. factory activity surged to its strongest level in years. The Philadelphia Fed manufacturing index jumped to 41.4 in July, well above the consensus estimate of 13. At the same time, initial jobless claims declined to 208,000 for the week ending July 11, below the expected 217,000. Together, those data points signaled a resilient economy and reduced the likelihood of near-term rate cuts by the Federal Reserve — a development that pressured gold prices.
This outcome is not a contradiction; it is the mechanism at work.
Why Does Strong Manufacturing Data Push Gold Prices Lower?
Gold tends to move inversely to real yields — the interest rate investors earn after adjusting for expected inflation. When economic data indicate the economy is running hot, the Federal Reserve has more reason to keep interest rates elevated. Higher nominal rates, when combined with steady or falling inflation expectations, raise real yields. Because gold yields nothing, the opportunity cost of holding bullion increases as real yields rise. That dynamic prompts some investors to move funds into yield-bearing assets, putting downward pressure on gold prices.
On Thursday, the market reacted quickly. The Philadelphia Fed number was released at 8:30 AM ET; by mid-morning, gold had given back nearly $90 from its opening price of $4,060. Silver dropped even more sharply, down roughly 4% to $55.47, reflecting silver’s dual sensitivity to monetary and industrial demand. Strong manufacturing data can be constructive for industrial metals over time, but in the immediate term it can be bearish for precious metals because it reduces the chances of monetary easing.
Historical relationships documented by market researchers show a sizable sensitivity of the gold price to moves in real yields. For example, a 25-basis-point rise in real yields has often correlated with a $40–$60 per ounce move lower in gold. The data on Thursday did not trigger a policy rate change, but it did shift traders’ expectations: CME FedWatch probabilities moved to roughly a 51% chance of a September rate increase by late afternoon, reflecting a higher perceived likelihood of tighter policy ahead.
The Edge Every Investor Needs
Smarter precious metals investing starts with timely insights. The Nuggets Newsletter delivers concise market analysis, Fed updates, trends, and educational content to help investors make informed decisions.
What Did the Philadelphia Fed Manufacturing Index Actually Show?
The Philadelphia Fed manufacturing index surveys roughly 250 manufacturers in eastern Pennsylvania, southern New Jersey, and Delaware and is one of the earliest regional monthly reads on U.S. factory conditions. A reading above zero denotes expansion; a reading of 41.4 denotes a substantial acceleration. By comparison, the index was 10.3 in June, so the July report represented a jump of more than 31 points in a single month and far exceeded the consensus forecast of 13.0.
Details within the report reinforced the strength: new orders and shipments both rose, with general activity and new orders indexes approaching multi-year highs. Paired with the labor-market update — initial jobless claims at 208,000 versus an estimate of 217,000 — the data painted a picture of sustained demand and a tight jobs market. That combination reduces the Federal Reserve’s room to ease policy ahead of the July 28–29 FOMC meeting and likely influenced investors’ short-term positioning in gold.
What Should Gold Investors Watch Next?
Investors should track a handful of near-term indicators that influence Fed expectations and real yields. On Friday, July 17, the University of Michigan will release its preliminary consumer sentiment and inflation expectations survey for July. Long-run inflation expectations have stayed above 3% since the onset of the Iran conflict in late February, even as gas prices eased through June. If those expectations move higher, it adds further pressure on the Fed to maintain or even raise rates.
The Federal Open Market Committee meets July 28–29. Markets currently expect a hold as the consensus outcome, but recent data — retail sales rising 0.2% in June, a Philly Fed reading that far exceeded forecasts, and continued tight jobless claims — have lowered the chance that policymakers will signal any easing. Gold is approaching levels not seen since November 2025 and is down roughly 29% from its January 28, 2026 all-time high of $5,589 per ounce.
That said, a single day of strong manufacturing data does not alter the broader structural forces underpinning the case for physical gold. Fiscal dynamics remain unchanged: the U.S. ran a deficit of $1.8 trillion in fiscal 2025, and annual interest payments on the national debt reached $970 billion in fiscal 2025 — the largest on record and on track to surpass $1 trillion in fiscal 2026. Servicing a large, growing national debt typically requires an expanding money supply over time, and those structural pressures are part of the long-term rationale for allocating a portion of a portfolio to sound money like physical gold.
In short, the immediate move lower in gold reflects markets pricing a resilient economy and a lower near-term probability of rate cuts. Over the longer horizon, fiscal strain and monetary dynamics continue to support the argument for holding physical gold as insurance against currency debasement and rising systemic financial risks.
SOURCES
1. Federal Reserve Bank of Philadelphia — Manufacturing Business Outlook Survey, July 2026
2. Bureau of Labor Statistics — Unemployment Insurance Weekly Claims, week ending July 11, 2026
3. CME Group — FedWatch tool and FOMC meeting probabilities, September 2026 contract month
4. Live gold and silver spot price data, July 16, 2026 (industry pricing services)
5. World Gold Council — analysis of the relationship between gold and real yields
6. Congressional Budget Office — Monthly Budget Review summary for fiscal year 2025
Disclaimer: This article is for informational purposes only and does not constitute financial or investment advice. Always consult a qualified financial adviser before making investment decisions.
You May Also Like:
- Warsh Told Wall Street to Stop Watching the Fed. Gold Already Knew.
- Gold Falls as Retail Sales Confirm the Fed Has No Reason to Cut
- Silver Dropped 1.4% Today. Gold Didn’t. The Ratio Just Hit 70:1.
- Gold Holds as CPI and PPI Both Miss. Here’s Why.
- Gold Is Flat. Oil Is Up 9%. Here’s Why.
- Gold and Fed Policy: When the System Picks Winners
Popular Topics
Picked from the archive
-
01
 Topics
Gold vs Silver: Why Gold Stabilizes Markets, Silver Amplifies
-
02
Topics
Gold Prices Surge: The Unexpected Reason
-
03
Topics
How Gold Is Changing Wall Street’s 60/40 Portfolio
-
04
Topics
Gold ETFs Lost 45 Tonnes as Central Banks Net 289: Why It Matters
-
05
Topics
Fed Split on Rate Hike as 45% of Central Banks Buy Gold
-
06
Topics
Why Gold and Oil Move Opposite and What It Means for Investors
-
07
Topics
Gold Near $4,700: Market Chaos May Be a New Floor
-
08
Topics
Gold Radar: 5 Hidden Signals Your Price Chart Misses