How Gold Is Changing Wall Street’s 60/40 Portfolio
Key Takeaways
- The traditional 60/40 portfolio’s diversification premise has deteriorated: the negative correlation between stocks and bonds that made bonds a reliable hedge turned positive in 2022 and has remained elevated — bonds now often move with equities during drawdowns instead of offsetting them. [Incrementum AG, In Gold We Trust 2025]
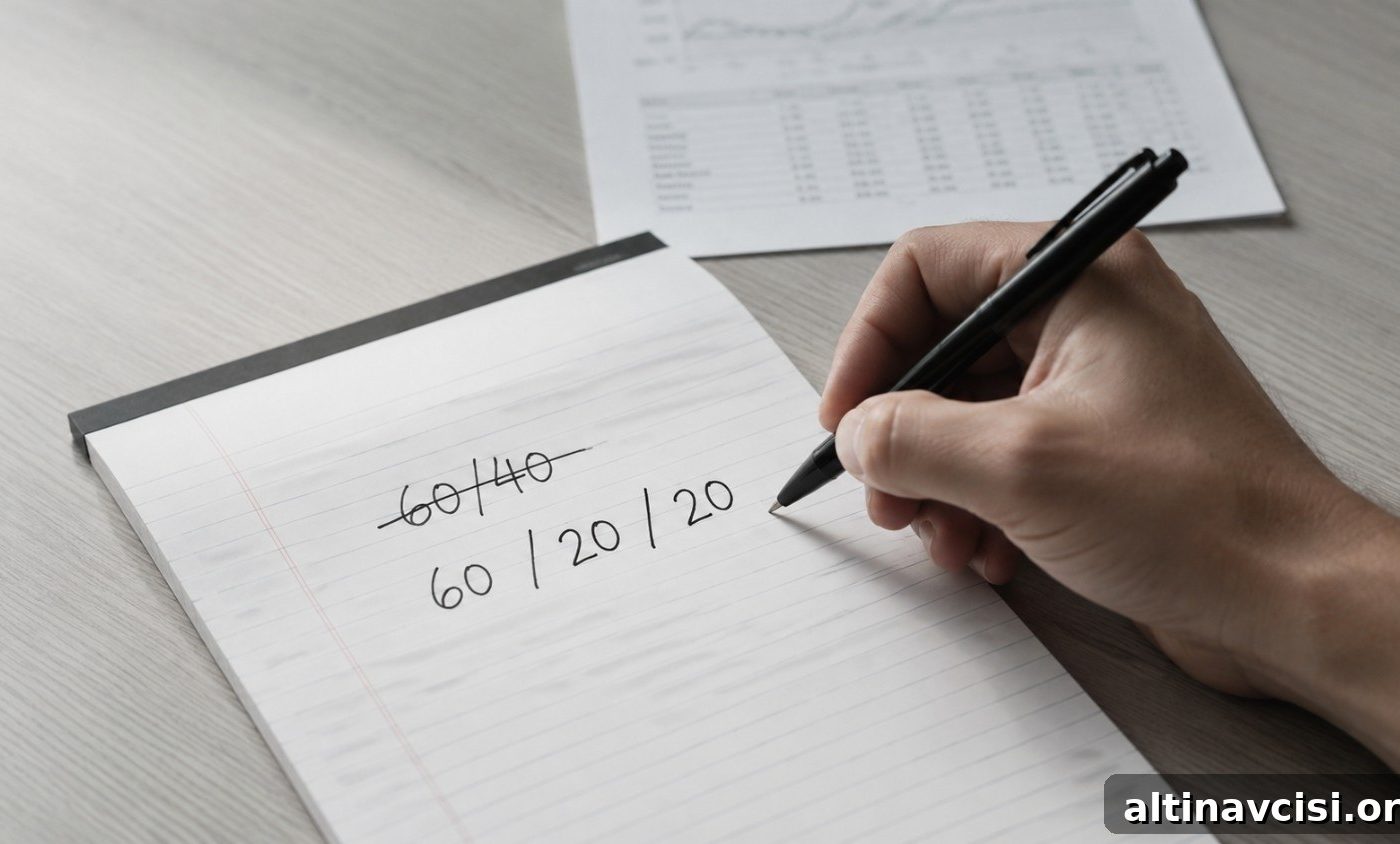
- Major institutions now recommend materially larger gold allocations. Morgan Stanley’s Chief US Equity Strategist proposed a 60/20/20 model (60% equities, 20% short-term bonds, 20% gold). BlackRock’s Investment Institute and Goldman Sachs’ commodities desk both describe gold as a structural, long-term portfolio holding rather than a short-term tactical trade. [Morgan Stanley; BlackRock Investment Institute; Goldman Sachs]
- This shift is primarily a reassessment of government bonds: recommending gold as a partial bond replacement signals that fiscal deficits and monetary conditions have weakened bonds’ historical role as a dependable safe asset — and that a real asset outside the financial system is needed to restore portfolio resilience. [Morgan Stanley; Goldman Sachs]
The Model That Broke
For decades the 60/40 allocation—sixty percent equities for growth, forty percent bonds for ballast—served as the standard blueprint for diversified portfolios. Its success relied on a consistent empirical pattern: during market stress, equities and high-quality bonds tended to move in opposite directions. Investors fleeing equities found refuge in bonds, which rose in value and cushioned portfolio losses.
That dynamic changed in 2022. Fast, aggressive rate hikes from the Federal Reserve produced a regime where stocks and bonds declined together. The S&P 500 fell sharply and long-duration Treasuries dropped even more, inflicting simultaneous losses across both sleeves of the traditional 60/40. That year marked the worst modern performance for the classic construction and exposed an important structural vulnerability.
By May 2026, several leading institutional research desks had converged on a new recommendation: increase portfolio gold allocation to the 10–20% range, replacing a meaningful share of bond exposure. This is a significant departure from the long-standing 2–5% strategic hedge that dominated financial planning. The catalyst is clear: since 2022, stock-bond correlation during drawdowns has often been positive, eroding the diversification benefit that justified the 40% bond sleeve. [Incrementum AG, In Gold We Trust 2025]
Incrementum AG’s research demonstrates that under current conditions a higher gold allocation produces materially better risk-adjusted outcomes. Gold has also appreciated substantially, reflecting these changing dynamics rather than a single crisis event.
Is the 60/40 Portfolio Still a Good Strategy?
The 60/40 portfolio is not dead, but its core diversification mechanism is compromised. The model depends on a persistent negative correlation between equities and investment-grade bonds during downturns. That pattern largely held from the late 1990s through 2021 but broke in 2022 when rising rates and inflation pressures drove both asset classes lower simultaneously. [Incrementum AG, In Gold We Trust 2025]
When inflation runs persistently above bond yields, bonds no longer function reliably as insurance. Instead, they can become a second source of loss during market stress. Reassessing gold portfolio allocation is therefore a structural response to a changed regime, not just a short-term market call.
The difference is determined by the type of shock. A pure growth shock—recession without inflation—pushes equities down and bonds up, and the 60/40 works. An inflation shock pushes both down and exposes the 60/40’s weakness. Current fiscal and monetary conditions increase the odds that inflationary shocks remain a relevant risk for the coming decade.
Why Are Institutional Investors Adding Gold to Portfolios?
The institutional case for increased gold allocation rests on three pillars: gold’s low correlation with both equities and bonds in the current environment, its historical strength during inflationary regimes, and the demand support from central bank accumulation. Together these factors create a compelling structural rationale for holding gold. [Morgan Stanley; BlackRock Investment Institute; Goldman Sachs]
Morgan Stanley’s model explicitly prescribes 60% equities, 20% short-duration bonds (to reduce rate sensitivity), and 20% gold. The bank highlights gold’s near-zero correlation with equities and short-duration bonds and underscores gold’s historical role in inflationary periods. BlackRock labels gold a “structural” holding—meaning it belongs in portfolios for its inherent properties, not timing. Goldman Sachs emphasizes central bank buying as a persistent price floor, real-yield dynamics that can favor gold in deficit-heavy regimes, and a unique diversification premium when stock-bond correlation is positive.
The convergence of three independent research desks on similar guidance is a strong signal: the correlation structure of global markets has shifted, and portfolio theory must adapt accordingly.
What Happens to Bonds When Inflation and Stocks Both Fall?
In an inflationary environment with rising rates, bonds suffer a double hit: their real purchasing power is eroded by inflation, and their market price falls as yields rise. This combination undermines bonds’ value as portfolio insurance and explains why gold can be a superior replacement in certain regimes.
Bonds provide fixed nominal cash flows. If inflation outpaces the bond’s yield, real returns become negative. When rates rise, existing bonds reprice lower to match new issuance yields, producing capital losses. That dynamic occurred in 2022 and mirrors the inflationary pressures of the 1970s.
Gold, as a real asset without fixed nominal cash flows, is not subject to the same mechanics. Its value tracks purchasing power and currency relationships rather than a central bank’s nominal policy rate. While bonds are effective hedges in low-inflation recessions, gold protects against currency debasement and inflationary shocks.
High and persistent fiscal deficits, such as multi-trillion-dollar annual budget gaps, increase the probability of prolonged inflationary pressure, making long-duration bonds riskier as “insurance” and strengthening the argument for gold as a genuine hedge.
How Much Gold Should Be in a Portfolio?
Institutional research from 2025–2026 commonly recommends a structural gold allocation between 10% and 20% of a diversified long-term portfolio. This materially exceeds the traditional 2–5% strategic allocation that was calibrated for a low-inflation, negative stock-bond correlation environment.
Incrementum AG’s analysis supports a 20% gold weighting under scenarios of above-target inflation, elevated fiscal deficits, and persistent positive stock-bond correlation. Their New 60/40 model—60% equities and 40% gold—outperformed the classic 60/40 over the period analyzed. Morgan Stanley’s 60/20/20 model is a compromise that retains a short-duration bond sleeve as protection against pure growth shocks while assigning 20% to gold as a permanent allocation.
Ten percent is typically the lower bound asserted in structural gold research, while twenty percent is the explicit upper bound recommended by some major desks. The optimal allocation for an individual depends on inflation expectations, time horizon, and risk tolerance—but evidence now makes a 2–5% allocation difficult to defend in many scenarios.
What Does the Performance Data Actually Show?
Recent performance supports the thesis: a “New 60/40” portfolio replacing bonds with gold outperformed the traditional 60/40 by a substantial margin since mid-2024. Incrementum AG’s report highlights that over a recent two-year period gold returned strongly while investment-grade bonds produced modest nominal returns, creating a large performance gap between the non-equity sleeves.
This result is arithmetic: when bonds fail to provide their historical return or hedge, any alternative sleeve that preserves value or appreciates materially will improve overall portfolio outcomes. Institutional research emphasizes that the drivers behind gold’s recent performance—fiscal deficits, inflationary pressures, positive stock-bond correlation, and central bank accumulation—are structural factors that are unlikely to reverse quickly.
Long-range scenario models in institutional research explore extended trajectories under continued debasement and monetary expansion. Those scenarios are not precise price forecasts but they demonstrate the directional logic supporting higher structural gold allocations in many plausible futures.
What Is the Institutional Shift Actually Saying?
The institutional move to recommend more gold is primarily a judgment about the declining reliability of government bonds as a safe asset. Recommending a permanent gold allocation indicates that major research desks no longer view long-duration government bonds as dependable portfolio insurance given current fiscal and monetary trends. This is as much a fiscal assessment as an investment recommendation.
In practice, the message is: the asset historically meant to protect you from equity risk is now exposed to the same fiscal and monetary risks that threaten equities. Investors may therefore need a real asset outside the financial system to restore genuine diversification. Institutional endorsement reduces the social friction around acting on that logic, making conversations about higher gold allocations more mainstream.
The Knowledge That Changes Everything
Two essential guides — free: learn why gold matters and how fiat currencies can be challenged by persistent debasement.
Stay On Top of Gold & Silver Prices
Receive timely market alerts and updates delivered to your inbox.
People Also Ask
Is the 60/40 portfolio dead?
Not dead, but its core diversification mechanism is compromised. The historic negative correlation between stocks and bonds held from roughly 1998 to 2021 and broke in 2022 when monetary tightening pushed both asset classes lower simultaneously. As long as inflation remains elevated and deficits persist, the bond sleeve’s hedge value is unreliable — which is why institutional debate over gold allocation has intensified. [Incrementum AG, In Gold We Trust 2025]
What percentage of my portfolio should be in gold?
Institutional guidance in 2025–2026 centers on a 10–20% structural allocation to gold. Morgan Stanley explicitly recommended 20% in one proposed model; other major research teams have argued that allocations above the historical 2–5% range are warranted given current macro conditions. The precise allocation should reflect personal inflation expectations, time horizon, and risk tolerance. [Morgan Stanley; BlackRock Investment Institute; Goldman Sachs]
Why are major banks recommending more gold now?
Because long-duration government bonds—traditionally the hedge in a 60/40 portfolio—are exposed to fiscal and monetary risks that can make them fail when equities fall. Recommending gold is a recognition that bonds have lost some of their historical “risk-free” status in the current fiscal and inflationary environment. [Goldman Sachs; Morgan Stanley]
How has gold performed compared to bonds since 2024?
Over a recent two-year window, gold produced substantially higher returns than investment-grade bonds, which delivered modest nominal gains. That divergence boosted portfolios that replaced bonds with gold during the period covered by institutional studies. These outcomes reflect changing regime dynamics rather than a single speculative episode. [Incrementum AG, In Gold We Trust 2025]
What is the difference between physical gold and a gold ETF for portfolio purposes?
A gold ETF provides price exposure but entails counterparty and custody layers on the issuer’s balance sheet. Physical gold is direct ownership of the asset with no intermediary. Institutional research often models ETF exposure for convenience and liquidity; physical ownership adds the benefit of eliminating counterparty risk, which can be relevant in extreme scenarios when gold’s protective properties are most needed. [World Gold Council]
What This Means for Individual Investors
The institutional shift matters because it normalizes a portfolio conversation that was once contrarian. You do not have to copy any institution’s model exactly, but you can now cite mainstream research when discussing higher gold allocations with advisors. Institutional recommendations mostly reference ETFs and futures, while physical gold remains an option for those who prioritize direct ownership and elimination of counterparty exposure.
Ultimately, the consensus that 10–20% in gold is reasonable under many plausible fiscal and monetary scenarios is now part of mainstream institutional guidance. Whether your portfolio reflects that judgment depends on your objectives, risk tolerance, and time horizon. Evidence and institutional analysis are no longer the primary constraints—personal preference and execution remain the deciding factors.
SOURCES
1. Morgan Stanley — Investment Insights & Research
2. BlackRock Investment Institute — Research & Commentary
3. Goldman Sachs — Insights & Research
4. Incrementum AG — In Gold We Trust 2025
5. World Gold Council — The Relevance of Gold as a Strategic Asset
6. US Congressional Budget Office — The Budget and Economic Outlook: FY2024
7. International Monetary Fund — Fiscal Monitor
Disclaimer: This article is for informational and educational purposes only. It does not constitute investment advice. Consult a qualified financial adviser before making investment decisions.
You may also like:
- What Does the SILVER Act Mean for Precious Metals Investors?
- What Backs the US Dollar? Not Gold. Not Silver.
- Why Is Gold Valuable? The 5,000-Year Answer Most Investors Get Wrong
- 72% of Family Offices Hold No Gold. What They’re Missing.
- Gold Remonetization: Six Forces Restoring Gold’s Monetary Role
- Silver Industrial Demand: Solar, EVs, and the Supply Gap
- Bank of America’s $6,000 Gold Forecast Isn’t a Price Call. It’s a System Call.
- Silver IRA Complete Guide: Rules, Limits, and Custodians Explained
Popular Topics
Picked from the archive
-
01
 Topics
Gold Prices Near Record as Tariffs Return
-
02
Topics
Inflation Under Trump: Fact Check on Price Changes
-
03
Topics
Tech Giants Drive 90% of Earnings Growth Despite Trade War Fears
-
04
Topics
Gold and Silver Rally Amid Market Volatility
-
05
Topics
Why Gold Prices Held Steady After Iran Peace News
-
06
Topics
Gold Price Volatility Back to COVID-Era Levels
-
07
Topics
Wholesale Prices Jump Most in 3 Years as Tariffs Hurt US Economy
-
08
Topics
Extra $21 Billion in Tariff Revenue Fails to Stem the Deficit