Gold Allocation Calculator: How Much Gold Should You Hold?
Key Takeaways
- Most investors hold less gold than updated research supports. Traditional guidance of 5–10% comes from studies in the 1980s. Recent analyses from CPM Group and Flexible Plan Investments indicate an optimal range closer to 18–30%, depending on your financial profile.
- Your ideal allocation depends on three variables: total paper-asset exposure, a financial vulnerability score, and your investment time horizon.
- Silver serves a different role than gold. It is more volatile and more tied to industrial demand. The gold-to-silver ratio near 69:1—above its 50-year average of roughly 65:1—indicates silver is historically undervalued relative to gold.
- A 5% gold allocation should be treated as a floor, not a target. World Gold Council research finds even 5% improves a portfolio’s Sharpe ratio, but current fiscal conditions may justify a larger position for many investors.
- Different macroeconomic scenarios—persistent stagflation, a deflationary liquidity correction, and a structural currency reset—change the allocation calculus and the protection gold provides.
The old 60/40 portfolio—stocks for growth, bonds for protection—worked reliably for decades. Around 2022 that framework began to lose its effectiveness, and new data have been building a case for a different approach since then.
The important question today is not whether gold should be part of a portfolio—the research has settled that—but how much gold is appropriate. The answer is more personal and more mathematical than the generic 5–10% guidance suggests.
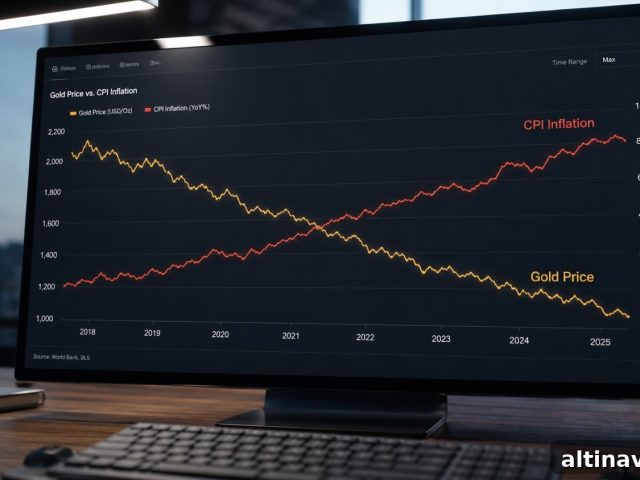
By July 2026 the U.S. national debt was roughly $39.4 trillion and annual interest payments exceeded $1 trillion. The Federal Reserve maintained the funds rate at 3.50–3.75% while core inflation, as measured by May 2026 PCE, ran at about 4.1% year over year. When savings earn less than inflation, purchasing power erodes. This environment is central to the allocation framework outlined below.
What Is a Gold Allocation Calculator and Why Does It Matter?
A gold allocation calculator is a structured way to determine what percentage of your investable assets should be held in physical gold and silver. Unlike a fixed recommendation, this method takes your individual exposure to paper-based financial risk into account and produces an allocation tailored to your situation.
This matters now because major institutions are rethinking traditional portfolios. Morgan Stanley’s CIO has recommended a 20% gold allocation within a 60/20/20 structure, and the In Gold We Trust 2026 report likewise called the 60/40 model structurally broken and proposed a 20% anchor in gold. These are influential voices, not fringe opinions.
The Knowledge That Changes Everything
Two essential guides — free. Learn why gold matters and why fiat currencies historically lose purchasing power.
Sign-up form removed for this version.
How Much Gold Should You Own in Your Portfolio?
The honest answer: more than many investors currently hold, but the exact percentage depends on your circumstances. Research provides a starting range; your personal variables narrow that into a target allocation.
World Gold Council research shows that adding as little as 5% gold historically improved risk-adjusted returns and reduced drawdown during equity bear markets. That is the floor. Updated studies push the ceiling higher: Flexible Plan Investments’ 45-year update (2025) finds an optimal allocation near 18% for risk-adjusted returns, while CPM Group’s analysis for current conditions suggests an updated optimal range around 25–30%.
The broad 5–30% range exists because no single optimal percentage fits every investor. Three variables determine your place within that band.
Step 1: Calculate your total paper-asset exposure.
Sum the market value of assets that depend on a counterparty to deliver value: stocks, bonds, mutual funds, ETFs, and bank deposits. This is your Paper Exposure.
Paper Exposure = Stocks + Bonds + ETFs + Cash DepositsStep 2: Assign your Financial Vulnerability Score (1–10).
Rate your situation based on income stability, proximity to retirement, bond exposure, and ability to tolerate a prolonged market drawdown:
- High vulnerability (7–10): Heavy reliance on fixed income, near or in retirement, limited ability to wait out multi-year corrections.
- Moderate vulnerability (4–6): Mid-career, mixed portfolio, a 10–20 year horizon, moderate flexibility.
- Low vulnerability (1–3): Long time horizon (20+ years), high equity tolerance, primary wealth accumulation from employment.
Step 3: Determine your starting allocation range.
Use these directional ranges rather than fixed prescriptions:
Low vulnerability (1–3): target 7–12% gold. Moderate (4–6): target 12–18%. High (7–10): target 18–25% as a starting position. If your current holdings fall well below your calculated range, your portfolio may be under-hedged for the scenarios that follow.
What Percentage of a Portfolio Should Be in Gold? What the Research Shows
Mainstream guidance still often cites 5–10% based on research from the early 1980s, but updated methodologies and current monetary conditions push the recommended range higher. Here is where major research and institutions stood in 2026:
- World Gold Council: 5% as a minimum insurance position; 10% as a balanced diversifier. Both levels show improvements in risk-adjusted returns.
- Flexible Plan Investments: An 18% optimal allocation in its 45-year backtest updated in October 2025.
- CPM Group: Analysis suggesting 25–30% may be optimal given fiscal and monetary dynamics in 2026.
- Bridgewater (Ray Dalio): Public guidance in the 5–15% range, emphasizing gold’s role when other assets perform poorly.
- Morgan Stanley / In Gold We Trust 2026: Proposals to use 20% gold as an anchor within a revised 60/20/20 portfolio that replaces bonds with gold as a traditional hedge.
The difference between where many investors actually hold gold—often under 5%—and where research indicates they might benefit from holding it is the central allocation gap this framework addresses.
How Does Silver Change Your Allocation Math?
Silver is not simply a smaller gold. It combines monetary demand with substantial industrial demand—about 58% of annual silver demand comes from industry, including solar panels, electronics, and medical devices. That industrial component makes silver more sensitive to economic growth expectations than gold.
When central banks signal tighter policy, silver faces two headwinds: higher opportunity cost like gold and weaker industrial demand expectations unique to silver. That dynamic contributes to the gold-to-silver ratio rising (near 69:1 at the time of writing), which suggests silver is historically undervalued relative to gold.
Allocation guidance by horizon:
- Short horizon (under 3 years): 80–90% gold, 10–20% silver.
- Medium horizon (3–10 years): 60–70% gold, 30–40% silver.
- Long horizon (10+ years): 50–60% gold, 40–50% silver—accepting higher short-term volatility for greater upside potential.
Silver’s supply dynamics also matter: recent years have shown a supply deficit, which supports a constructive long-term view for silver when combined with an appropriate risk profile.
How Does Your Gold Allocation Change Across Different Economic Scenarios?
Three plausible macro scenarios over the next five years change how gold performs and what allocation makes sense. Stress-testing your allocation against each scenario helps determine whether your position offers the protection you expect.
Scenario A: Persistent Stagflation
Slow growth combined with persistent inflation is where gold’s asymmetric upside is strongest. Real yields would remain suppressed or negative, reducing the opportunity cost of holding gold while inflation erodes the purchasing power of cash and bonds. If this persists, gold is supported structurally rather than just temporarily.
Scenario B: Deflationary Liquidity Correction
In a sudden liquidity shock, all assets can be sold to raise cash, and gold often falls initially. Central banks typically respond with liquidity measures; real yields then collapse and gold usually recovers and surpasses pre-correction levels. An allocation should be sized so a temporary 15–20% decline does not force a sale.
Scenario C: Structural Currency Reset
A formal or de facto reset of the dollar’s reserve role—through revaluation, de-dollarization, or broad shifts in reserve assets—would be highly favorable to physical gold. Central bank buying activity in recent years signals a long-duration institutional view; in a structural reset the difference between a 10% and a 20% allocation becomes especially consequential.
What Are the Biggest Mistakes Investors Make With Gold Allocation?
Three common mistakes recur:
Mistake 1: Confusing paper exposure with physical ownership.
Gold ETFs and futures provide price exposure but do not always provide physical possession. For protection during systemic stress, physical, allocated metal held in your name carries no counterparty risk.
Mistake 2: Treating 5% as a destination instead of a floor.
Five percent improves portfolio metrics but may be insufficient in several macro scenarios. Consider both the potential drawdown of other assets and how much protection you actually need rather than stopping at the floor.
Mistake 3: Buying only at moments of maximum fear.
A systematic approach—dollar-cost averaging into precious metals over 12–24 months—removes timing and emotional risk and yields a more durable allocation than large, fear-driven purchases.
Is Now a Good Time to Build or Increase a Gold Allocation?
In mid‑July 2026 gold traded near $4,143 per ounce, roughly 26% below its January intraday high of $5,589. Institutional year‑end forecasts clustered in a $4,300–$4,900 range at the time, but the allocation framework does not hinge on short-term price predictions. It depends on structural inputs: rising national debt, inflation above central-bank targets, sustained central bank buying, and constrained real yields. Those measurable conditions are present and inform the allocation decision.
After deciding your allocation target, the practical question is custody: physical gold and silver can be stored at home, in a private vault, or in an insured institutional depository outside the banking system. Each option has trade-offs in cost, convenience, and security. The allocation calculator tells you how much; custody is the implementation step.
Stay On Top of Gold & Silver Prices
Get important market alerts sent to your inbox.
Price widget removed for this version.
People Also Ask
Research from Flexible Plan Investments indicates an 18% allocation can optimize risk-adjusted returns over a long horizon. Investors within ten years of retirement, who cannot tolerate prolonged portfolio drawdowns, generally benefit from a higher allocation—commonly 15–25%—because gold’s low correlation with equities helps protect assets when markets fall near spending timeframes.
Silver increases both upside potential and volatility. It often outperforms gold percentage-wise in bull markets but lags more during corrections. For long-term investors who can accept short-term swings, silver can add return potential—especially when its ratio to gold is elevated—while increasing the overall volatility of the precious metals sleeve.
Annual rebalancing to a target range is practical. If gold rises substantially and exceeds your target by more than a few percentage points, trimming maintains portfolio structure. If gold falls below target, that creates a systematic buying opportunity.
For protection against systemic financial risk, physical, allocated ownership is the instrument that best delivers the stated thesis. ETFs provide convenience and price exposure but carry custodian and counterparty considerations that physical allocated metal does not.
SOURCES
1. U.S. Treasury Fiscal Data — Debt to the Penny, July 2026
2. U.S. Bureau of Economic Analysis — Personal Income and Outlays, May 2026
3. World Gold Council — Portfolio Research and Gold Demand Trends
4. Silver Institute — World Silver Survey 2026
5. CPM Group — Optimizing Your Portfolio with Gold and Silver
6. Flexible Plan Investments — The Evidence-Based Case for an Optimal Gold Portfolio Allocation, October 2025
7. In Gold We Trust Report 2026 — Incrementum AG
8. JPMorgan Global Research — Gold Price Forecast, July 2026
9. GoldSilver.com — Live Gold and Silver Price Charts
10. Advisor Perspectives / Money Metals Exchange — The 60/20/20 Portfolio Strategy, November 2025
Disclaimer: This article is for informational purposes only and does not constitute financial or investment advice. Consult a qualified financial adviser before making investment decisions.
You May Also Like:
- What Is the Gold Volatility Index (GVZ) — and What Does It Mean for You?
- Gold & Silver Market Correction: Is the 2026 Bull Market Over?
- JPMorgan Cut Its Gold Forecast by 25%. Here’s What Long-Term Holders Need to Know.
- Why HSBC Still Believes Gold Hits $4,750 by Year-End (And What the Mainstream Is Missing)
- State Street Predicts $5,500 Gold by Q1 2027: Is the Dip Over?
- Why China’s Gold Buying Spree Outweighs India’s Pause
- What Is Purchasing Power — and Why Every Dollar You Save Is Slowly Being Taxed Away
Popular Topics
Picked from the archive
-
01
 Topics
After Major Silver Price Crashes: What Investors Can Expect
-
02
Topics
Gold Price Outlook June 2026: CPI Impact and Fed Signals
-
03
Topics
Why Gold Failed to Rally Today: 5 Key Reasons
-
04
Topics
Is the Gold Price Correction Over? Rebound Signals for Investors
-
05
Topics
Why Silver Dropped 3.3% vs Gold’s 1.6%: The Gap Explained
-
06
Topics
How the London Gold Fixing Shapes Global Gold Prices
-
07
Topics
Could Silver Prices Reach $75 After Surging Past $60?
-
08
Topics
Gold Price Near $5,000 as Fed Battles Sticky Inflation