China Moves Gold Reserves After 20-Month Buying Spree
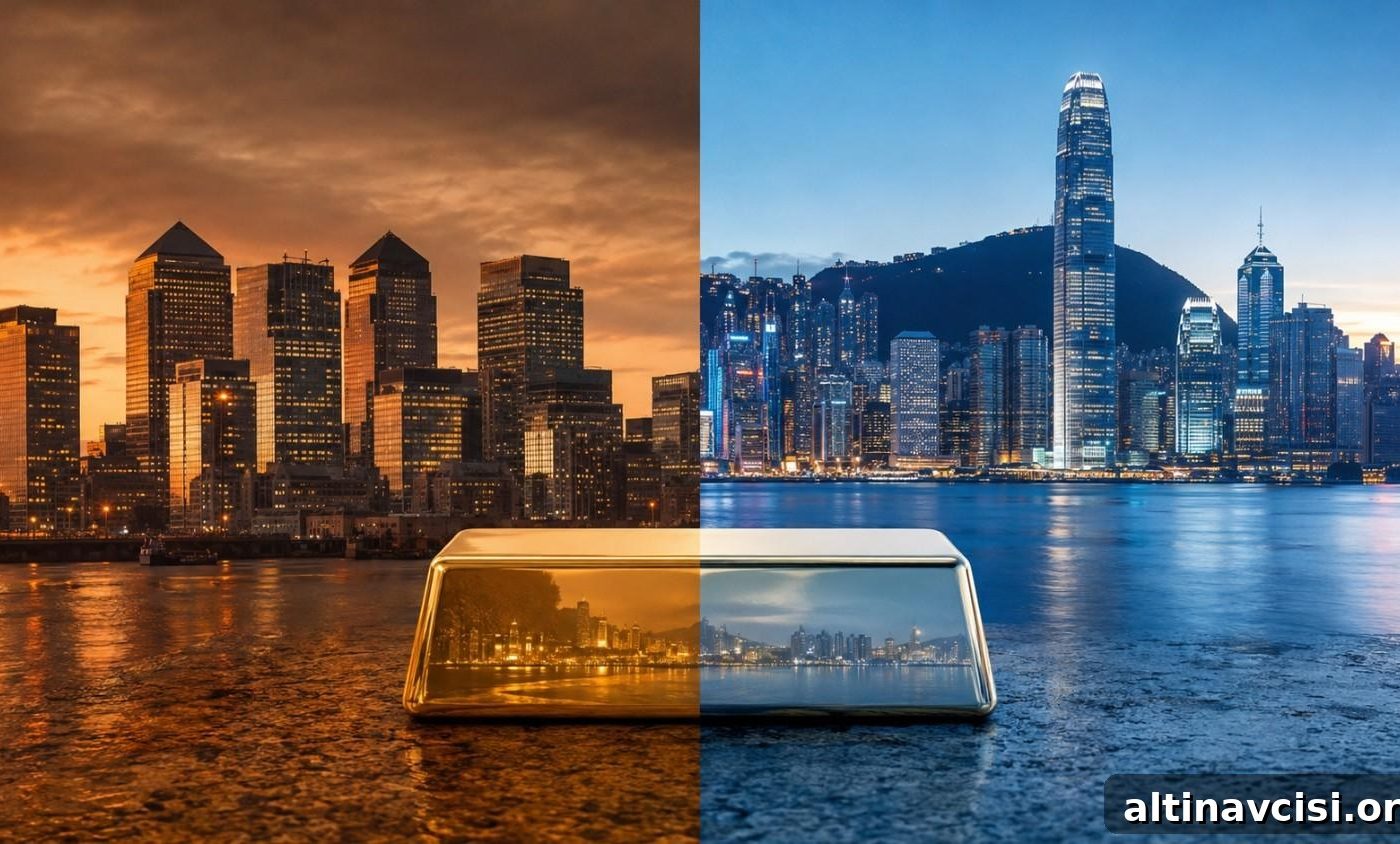
Most headlines this year about China’s central bank have been straightforward: the People’s Bank of China (PBoC) continues to buy gold. That is accurate, but recent reporting shows a more consequential development beneath the surface. Bloomberg and other outlets have reported that the PBoC has been transferring physical gold into Hong Kong vaults in recent months — a move that appears to accelerate a longer-term effort to shift part of China’s official gold reserves out of London and into an Asia-based settlement system that Beijing has helped establish.
The significance of this relocation becomes clearer when you consider why London has historically held so much central-bank gold. London’s gold market relies heavily on unallocated accounts: deposited gold becomes part of a pooled inventory that commercial banks can borrow, lease, or use for financing. That model has made London the dominant center for global gold price discovery for over a century. Moving physical metal away from London reduces the size of that pooled inventory and changes how liquidity and pricing function across the global gold market.
Central Bank Buying
PBoC Monthly Gold Purchases, Jan–Jun 2026
Tonnes added to official reserves each month
June 2026 — largest since Oct 2023
| Month | Tonnes added |
|---|---|
| January 2026 | 1.20 t |
| February 2026 | 5.00 t |
| March 2026 | 5.00 t |
| April 2026 | 8.00 t |
| May 2026 | 9.95 t |
| June 2026 | 14.93 t |
June 2026 was the PBoC’s largest single-month purchase since October 2023. China’s official holdings reached 2,346 tonnes at the end of June 2026, marking 20 consecutive months of net buying.
Sources: China State Administration of Foreign Exchange (SAFE); World Gold Council Gold Demand Trends Q2 2026.
Shifting metal out of London does two practical things. First, it withdraws available inventory from London’s lending and leasing pool, which can tighten gold lease rates and reduce the supply available for short-term financing. Second, it places that same metal into Hong Kong’s emerging infrastructure, increasing deliverable liquidity in Asia. Market participants will begin to price these changes into funding rates and into the relationship between paper-based and physically settled gold prices.
The Edge Every Investor Needs
Smarter precious metals investing starts here. The Nuggets Newsletter delivers concise market insights, central bank developments, Asian market structure changes, and practical educational content.
What Is Hong Kong Building — and Why Does It Matter?
On July 7, 2026, Hong Kong began a trial operation of its Precious Metals Central Clearing Company (PMCC), achieving, for the first time at institutional scale in Asia, a government-backed gold settlement infrastructure. The PMCC connects directly to the Shanghai Gold Exchange, settles trades in physical allocated gold on a T+1 basis, and introduced a new Asian benchmark called the HAU that is published during Asian trading hours.
The HAU is significant because it is anchored to physically deliverable, allocated gold settled the next business day. By contrast, London’s long-standing benchmark is based on spot unallocated gold through an auction mechanism: participants hold pooled claims rather than title to specific bars. Put simply, two settlement models exist in parallel. Over time, the system with the greater quantity of physical metal available in its time zone — and the infrastructure to settle that metal — will exert more influence on price discovery.
Notably, banks that are central to this new Hong Kong system are also established players in Western finance. HSBC, JPMorgan, UBS, and Citi are part of the PMCC governance and also participate in London’s gold clearing. These institutions effectively helped seed the infrastructure that could become a regional alternative to London’s market.
Why Does the PBoC Keep Buying Through a Declining Market?
In June 2026 the PBoC added 14.93 tonnes of gold, its largest single-month purchase since October 2023, and continued a streak of 20 consecutive months of accumulation even as gold experienced its worst quarterly decline in over a decade. Central banks do not generally buy gold in response to short-term price moves. They accumulate because gold is unique among reserve assets: it exists outside the credit and sovereign-claim system. Gold cannot be created by another government, and it cannot be frozen or fully devalued by the policy decisions of a counterparty. For many central banks, that attribute makes gold an essential element of reserve diversification.
Global central-bank demand has been strong in recent years, with institutions adding significant tonnes annually. The World Gold Council reported particularly high central-bank purchases in recent quarters, reinforcing the trend that official buyers are steadily increasing their allocations irrespective of short-term price swings.
What Does This Mean for You as a Gold Owner?
The PBoC’s reallocation of metal is primarily an infrastructure and market-structure move, not merely a political signal. Beijing is enhancing the exchange and settlement system it helped create in Hong Kong rather than continuing to rely solely on a system that developed under Western financial dominance.
For private owners of physical gold, the practical implication concerns settlement type and custody. Gold held in allocated custody — where specific numbered bars are registered in your name and not part of a pooled claim — remains outside the lending and leasing dynamics of the London unallocated system. As Hong Kong’s allocated clearing volumes grow and central-bank metal migrates to Asian vaults, the spread between London’s paper-anchored price and a physically settled Hong Kong price is likely to become an increasingly important market signal.
At the time of the most recent reporting, gold was trading around $4,328 per ounce and remained anchored to the LBMA Gold Price, London’s twice-daily benchmark auction. The central question for market participants is how long London’s auctions will remain the dominant global reference as Asia develops its own deliverable, allocated settlement infrastructure.
SOURCES
1. Bloomberg — China Central Bank Adds Gold in Hong Kong to Support Trading Hub (August 7, 2026).
2. World Gold Council — Gold Demand Trends Q2 2026 (July 30, 2026).
3. China State Administration of Foreign Exchange (SAFE) / South China Morning Post — China extends gold buying binge to 20th month (July 7, 2026).
4. GoldSilver.com — Hong Kong Just Ran Its First Gold Settlement (July 17, 2026).
5. BullionStar — Deep Dive: China’s Exit from Retail Paper Gold Trading (July 2026).
6. GoldSilver.com Price Charts — Live Gold Price (August 7, 2026).
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Past performance is not indicative of future results. Consult a qualified financial advisor before making investment decisions.
You May Also Like:
- Trump’s Polysilicon Tariff Just Hit Silver’s Biggest Industrial Customer
- Gold Rallied 6% This Week. Tomorrow One Number Decides Whether It Holds.
- Why Is Silver Outperforming Gold? A 6-Year Deficit
- Hormuz. ISM. Hecla. Barrick. Five Things Moved Gold and Silver Today.
- Jobs Missed. Gold Hit $4,200. Silver Hit $62.
- South Korea’s Central Bank Hasn’t Bought Gold in 13 Years. That Just Changed.
- Gold and Silver Hold As Bessent Promises a Hormuz Deal, a Vessel Gets Hit, and JOLTS Drops
Popular Topics
Picked from the archive
-
01
 Topics
Central Banks Favor Gold Over the Dollar: Impact on Your Savings
-
02
Topics
Record Gold ETF Outflow Sparks Debate as China Disagrees
-
03
Topics
Is Gold Still a Safe Haven in War? Investor Insights
-
04
Topics
Gold Near $4,330 as 70% Rate-Hike Odds Rise, China Intervenes
-
05
Topics
Jobs Beat, Ceasefire, Deficit: Impact on Gold Prices
-
06
Topics
Silver Price Spikes to $69.85, FOMC Erases Gains
-
07
Topics
Banks Forecast Gold Over $5,400 After Greenland News
-
08
Topics
Why Gold Climbed After an 8% Oil Spike — What’s Different