Barrick CEO: Tariffs Won’t Derail Copper Rally Amid Supply Crunch
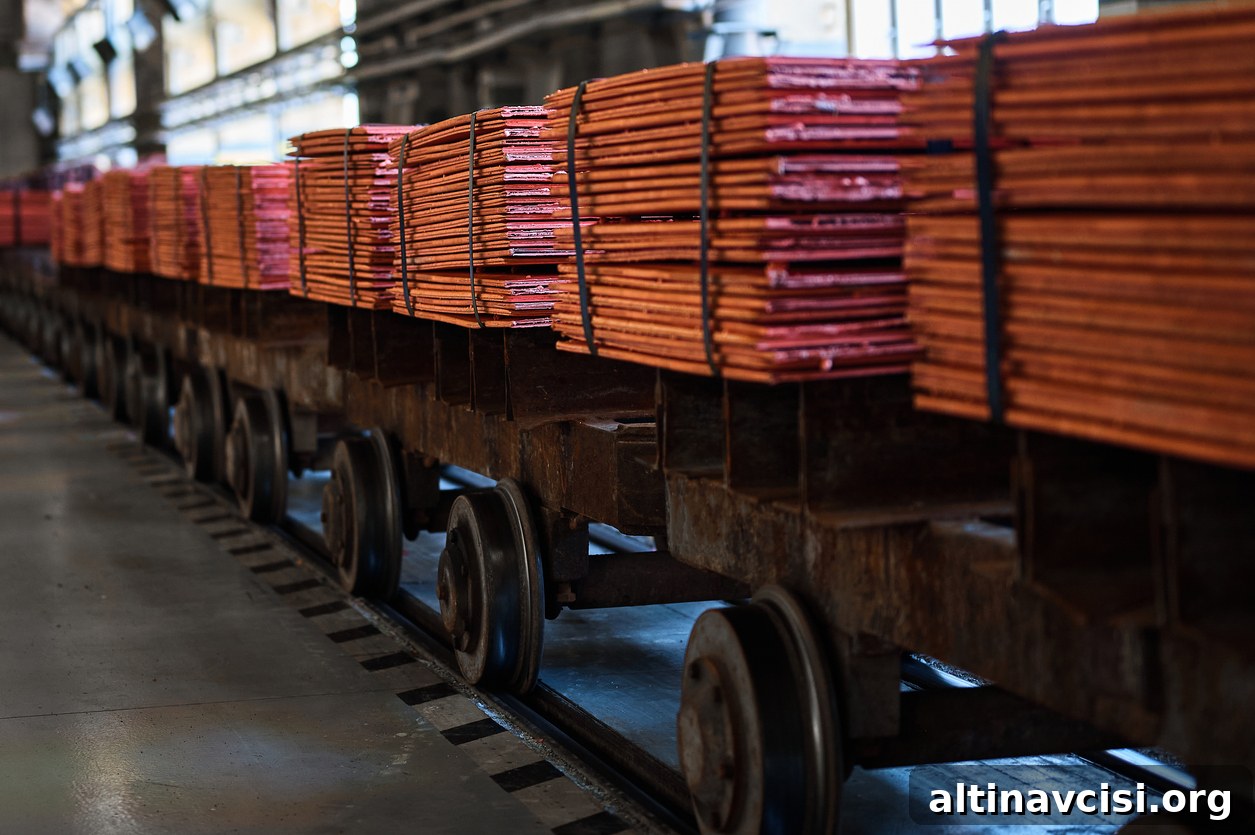
Barrick CEO Says Copper’s Long-Term Outlook Remains Strong Despite U.S. Tariffs
Barrick Mining CEO Mark Bristow, speaking from Zambia, has reiterated a confident long-term outlook for copper even as recent U.S. trade policy has injected short-term volatility into markets. The announcement of a 50% copper tariff by President Trump sent U.S. copper futures to record highs and sparked immediate market reactions, but Bristow emphasized that the underlying fundamentals supporting copper demand remain robust.
Short-Term Market Reaction Versus Long-Term Fundamentals
The tariff announcement prompted an acute market response: futures climbed sharply as traders and consumers recalibrated supply-cost expectations. Such policy shocks can cause rapid price swings and heightened volatility as market participants reassess import costs, inventory strategies and hedging positions. Bristow acknowledged this short-term turbulence while making clear that policy-driven price movements do not erase the structural drivers that support sustained copper demand.
In Bristow’s view, the global copper market remains undersupplied relative to anticipated demand growth. Short-term price spikes, while disruptive, do not change the longer-term supply-demand imbalance that many industry participants and analysts have been citing for several years.
Demand Drivers: Data Centers, Clean Energy, and Emerging Market Industrialization
Multiple sectors continue to propel copper consumption higher. Data centers require substantial electrical infrastructure and cooling systems, both of which rely heavily on copper for power distribution and thermal management. The rapid expansion of cloud services and hyperscale computing facilities increases copper intensity per data center, adding to aggregate demand.
Clean energy technologies are another critical driver. Renewable energy systems, electric vehicles, battery storage, wind turbines and solar farms all use copper extensively for electrical wiring, grounding, motors and power electronics. As countries and companies work toward decarbonization targets and electrify transport and grids, copper becomes central to those transitions.
Finally, industrialization and urbanization in emerging markets are raising baseline consumption of copper for construction, electrical grids, telecommunications and manufacturing. As infrastructure investment and household electrification advance in those regions, per-capita copper usage tends to rise, further tightening the global supply-demand balance.
Barrick’s Expansion at Lumwana
Against this backdrop, Barrick is proceeding with a major investment in its Lumwana copper mine in Zambia. The company has committed roughly $2 billion to expand capacity at Lumwana, with the stated aim of roughly doubling production by 2028 and extending the mine’s operating life through 2057. That expansion reflects a strategic bet on continued copper demand over multiple decades and represents a significant capital allocation to boost long-term supply from a stable mining jurisdiction.
By advancing the Lumwana project, Barrick signals confidence in both the mine’s resource potential and the long-term macroeconomic trends that support copper consumption. Larger, predictable production from established operations can help balance market tightness over time, even as short-term shocks influence prices.
Implications for Industry Stakeholders
For miners, tariffs and policy shifts underscore the importance of portfolio diversification, cost control and strategic planning. Companies with projects already under development or in production can absorb short-term shocks more effectively than those relying on new greenfield assets. For consumers and midstream users, higher tariffs increase input costs and may accelerate hedging or substitution strategies where feasible, though copper’s unique electrical and thermal properties make it difficult to replace in many applications.
Investors watching copper should weigh near-term volatility against the deeper structural drivers of demand. While tariffs and geopolitical developments can produce spikes or dips in pricing, long-term capital cycles in mining—exploration, permitting, construction—mean that supply response to higher prices is slow, reinforcing the potential for sustained market pressure if demand growth continues.
Outlook
Mark Bristow’s message from Zambia is one of measured optimism: short-term disruptions from trade policy are real and can be significant, but they do not alter the long-run trends that underpin copper’s critical role in modern infrastructure, digital expansion and the energy transition. Barrick’s investment in Lumwana demonstrates a commitment to supply growth intended to match that long-term demand trajectory.
As markets digest tariff developments and companies adjust strategies, the interplay between policy, pricing and investment will remain a focal point for stakeholders across the copper value chain. For now, the consensus reflected in Bristow’s remarks is that the long-term case for copper remains intact.
Popular Topics
Picked from the archive
-
01
 Topics
US Economy Sees First GDP Decline Since 2022: Q1 Falls 0.3%
-
02
Topics
Tariffs Drive Up Consumer Prices as Inflation Rises
-
03
Topics
Bullion Premiums: How to Spot Fair Prices
-
04
Topics
Silver Approaches $40 Amid Tightening Supply and Trade Tensions
-
05
Topics
Russia Taps $1B Chinese Gold Market Amid Geopolitical Shift
-
06
Topics
Gold Prices Rise on Trade Tensions and Currency Moves
-
07
Topics
Goldman Sachs Sees Gold Price Reaching $4,000 by Mid-2026
-
08
Topics
Goldman Sachs: Central Bank Demand Pushes Gold Past Silver