Why Silver Fell 3.8% as Gold Dropped 2.9%
Silver is unique among major financial assets because a large portion of its supply is consumed by industry. Roughly 58% of every ounce mined is used directly in manufacturing—most notably in solar panels, semiconductors, and electric-vehicle motors—before any of it is held by savers or investors (Source: Silver Institute, World Silver Survey 2026).
That industrial attachment is silver’s strongest long-term advantage. Today, however, it also explains why silver tumbled more sharply than gold.
Silver closed at $57.59 on Monday, July 13, down 3.8% for the day. Gold settled at $3,999, a 2.9% decline, briefly dipping below the psychologically important $4,000 level intraday.
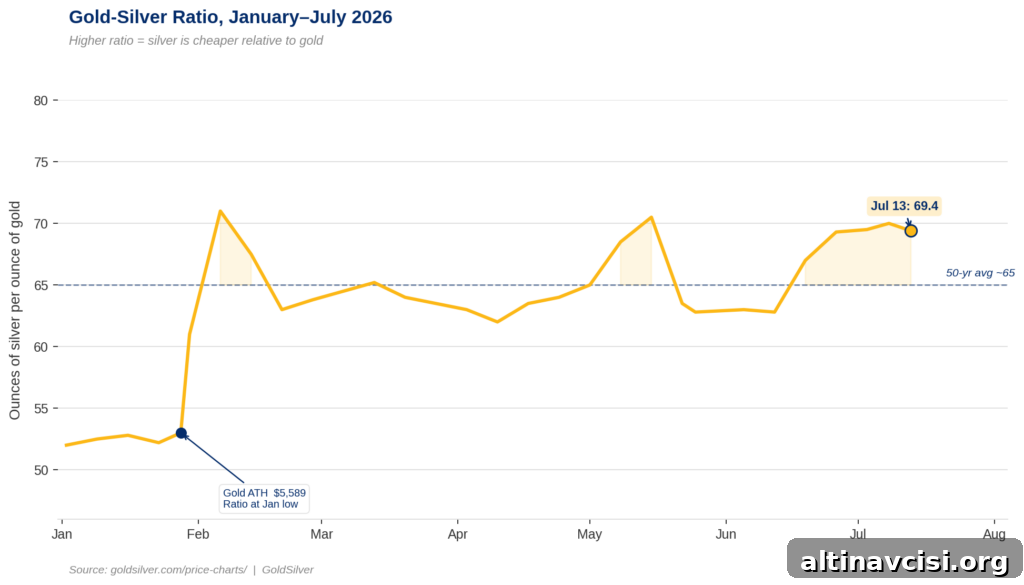
The gold-silver ratio climbed to 69.4, meaning it now takes nearly 70 ounces of silver to purchase one ounce of gold. By comparison, the roughly 50-year historical average sits near 65.
Why Did Silver Fall More Than Gold Today?
Overnight on July 12–13, US and Iranian forces exchanged missile and drone strikes for the fourth time in a week. Iran reported that it had closed the Strait of Hormuz; US Central Command rejected that claim. Still, oil prices jumped by more than 4% on the news.
Rising energy costs lift inflation expectations, and higher inflation expectations tend to push central banks toward tighter policy. Markets quickly repriced the odds of a September Federal Reserve rate hike, with data indicating roughly a 70% probability at the time of the move.
That shift in rate expectations hit silver from two angles simultaneously.
How Does Silver’s Dual-Engine Structure Work?
Silver operates on two demand engines at once: monetary demand and industrial demand. On the monetary side, silver reacts similarly to gold: when real interest rates rise, the opportunity cost of holding a non-yielding metal increases, weighing on prices. On the industrial side, silver is an essential input in rapidly growing sectors—solar panels, EV motor windings, electronics, and certain medical devices—so its price is also tied to growth expectations.
Gold is predominantly a monetary asset and lacks large-scale industrial use, so it primarily responds to changes in real yields and investor demand. Silver, by contrast, absorbs the same monetary pressure as gold and then takes an additional hit when industrial buyers pull back in anticipation of slower growth.
That dual-exposure works both ways. In hawkish environments silver tends to fall faster than gold, but it also has a history of rising more strongly when conditions improve. For example, during the shock of March 2020 the gold-silver ratio reached roughly 127:1; in the following 12 months silver significantly outpaced gold—by roughly fifty percentage points—during the recovery.
What Are Central Banks Doing While Silver Falls?
Short-term downward pressure on silver is clear, but several central bank actions point to a different longer-term backdrop for precious metals overall.
China’s central bank added 14.93 tonnes of gold to its reserves in June 2026—the largest single-month purchase since October 2023—extending a streak of monthly buying to 20 consecutive months. Total Chinese official gold holdings stood at about 2,346 tonnes, which remains under 10% of estimated total reserves. That steady accumulation suggests a structural, longer-term demand picture for bullion that goes beyond short-term market moves.
Does Today’s Drop Change Silver’s Structural Case?
No. The underlying structural case for silver remains intact. For six consecutive years silver has faced a supply challenge: annual demand has outpaced mine production since 2021, according to industry assessments. Short-term hawkish signals from the Fed—such as a split in FOMC views noted in minutes released in early July—do not alter that fundamental supply-demand imbalance.
Industrial demand is driven by concrete projects—solar farms, vehicle production lines, and industrial electrification—many of which are already under construction. A single Fed hike signal does not stop panels from being installed or EVs from being manufactured. And the monetary side of silver’s demand reacts to real yields over months and years rather than in a single session.
In other words, the same industrial exposure that deepens silver’s sell-offs also amplifies its recoveries. When real-yield pressure eases, industrial buying can accelerate silver’s rebound, often producing a stronger upside move than gold experiences from the same turning point.
What Should Investors Watch Next?
Two near-term catalysts merit close attention over the next 18 hours.
First, the June Consumer Price Index (CPI) will be released at 8:30 AM ET on Tuesday, July 14. Consensus forecasts at the time called for a slight month-on-month decline—around -0.1%—largely driven by a meaningful drop in gasoline prices compared with mid-June levels. Core CPI, which strips out volatile food and energy components and is the Fed’s preferred gauge, was expected to remain near 2.9% year-over-year. A core reading at or above that level would keep expectations for a September rate increase elevated.
Second, Federal Reserve Chair Kevin Warsh was scheduled to testify before the House Financial Services Committee at 10:00 AM ET the same day. His assessment of whether recent energy-driven disinflation is temporary or more persistent will influence how markets price the July 29 FOMC decision and the path of real yields.
Investors should watch both the gold-silver ratio and outright metal prices. If core inflation prints softer than expected and Fed commentary turns more measured, a move toward a ratio around the historical average (~65) would signal that markets are beginning to price in a recovery driven by silver’s industrial and monetary engines.
Sources
1. Silver Institute — World Silver Survey 2026 (April 15, 2026).
2. Bloomberg reporting on China central bank gold purchases (July 2026).
3. South China Morning Post coverage of Chinese gold accumulation (July 2026).
4. Federal Reserve — FOMC calendar and rate decisions.
5. Bureau of Labor Statistics — Consumer Price Index release schedule (July 14, 2026).
6. Reuters reporting on Fed Chair testimony scheduling.
Disclaimer: This article is informational and does not constitute financial or investment advice. Consult a qualified financial adviser before making investment decisions.
You May Also Like:
- Trump’s Hormuz Toll Is an Inflation Tax. Here’s Why Gold Fell.
- Gold Fell 1.4% on an Iran Strike. One Number Tomorrow Morning Could Change Everything.
- Trump Declared the Ceasefire Over. Gold Barely Moved.
- HSBC Cut Its Gold Forecast by $304. Then Said Gold Will Hit $4,750 by Year-End.
- The Fed Named AI Its Top Inflation Risk. Gold Noticed.
- Five Days From Now, Two Numbers Will Decide Gold’s Second Half.
Popular Topics
Picked from the archive
-
01
 Topics
Why Gold Tumbled After the Hormuz Tanker Strike
-
02
Topics
GDP Report Delays and Weak Retail Sales Signal Economic Risk
-
03
Topics
Physical vs Digital Gold: Which Is the Safer Investment?
-
04
Topics
Gold Price Near $5,000 as Fed Battles Sticky Inflation
-
05
Topics
Wall Street’s $6,000 Gold Call Relies on Hidden Data
-
06
Topics
PCE Inflation Hits 4.1%: Why Gold Prices Rose
-
07
Topics
UBS Cuts Gold Price Target by $400: What They Kept Matters
-
08
Topics
Gold and Silver Hit Record Highs Amid Shutdown Deadlock