Silver Price Drops 7% After No-Deal at Trump-Xi Summit
Key Takeaways
- Silver dropped about 7.7% to $77.11 on May 15, 2026, erasing a four-day summit-driven rally that had pushed prices from roughly $77 to $86.10.
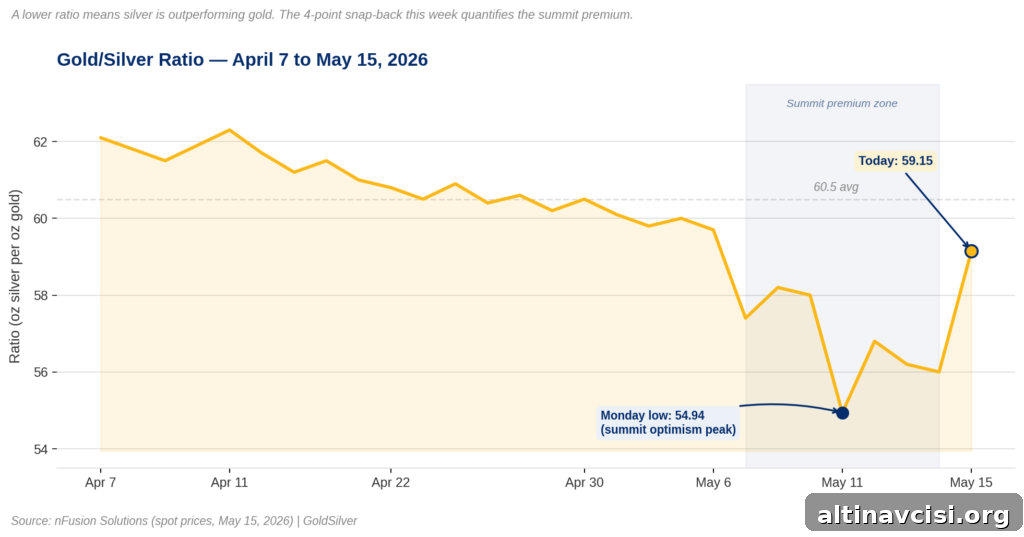
- The gold/silver ratio snapped back from 54.94 to approximately 59, indicating about $8/oz of the recent silver move was driven by short-term trade optimism now reversed.
- The structural supply-demand picture remains intact: six consecutive annual supply deficits, a projected 46.3 million ounce shortfall in 2026, and a monetary backdrop that, in some respects, deteriorated rather than improved.
Why did silver fall so sharply today? The short answer: a summit premium that had accumulated over four days evaporated in a single session.
On May 15, 2026, silver slid roughly 7.7% to $77.11 as traders unwound positions that had priced in hopes of a trade breakthrough from the Trump-Xi Beijing summit. Markets had built a premium ahead of the meeting that assumed a substantive trade outcome. Silver opened the day near $83.47 and then declined steadily, ending the session close to where it traded before the summit optimism began.
This sell-off represents the removal of short-term optimism, not a reversal of the fundamental case for silver. Structural drivers remain supportive: persistent supply deficits, strong industrial demand, and monetary conditions that still favor precious metals as an inflation hedge and store of value.
The Edge Every Investor Needs
Smarter precious metals investing starts here. The Nuggets Newsletter delivers timely market insights, Fed updates, global trends, and educational content.
Why Does Silver React So Sharply to Trade News?
Silver’s price is driven by two distinct demand engines: monetary demand and industrial demand. Monetary demand treats silver as a store of value and a hedge against currency debasement—an asset often held outside the banking system. Industrial demand accounts for roughly 60% of annual silver consumption, according to the Silver Institute’s World Silver Survey 2026. Much of that industrial use flows into solar panels, electric vehicles, and electronics, and these supply chains are closely tied to US-China trade dynamics.
Because silver sits at the intersection of monetary and industrial demand, it reacts more sharply than gold to trade developments. Ahead of the Trump-Xi summit in Beijing, markets priced in a potential breakthrough. Traders built a summit premium that pushed silver from about $77 to $86.10 over four days. When the summit failed to deliver concrete, market-moving agreements, the optimism was unwound rapidly.
Public statements after the summit were short on specifics. Reported plane orders and announcements did not meet the most ambitious expectations, and some geopolitical comments introduced fresh inflation and risk considerations. With no tangible trade agreement to justify the earlier rally, that summit premium came off the price.
What Is the Gold/Silver Ratio Saying Right Now?
The gold/silver ratio shows how many ounces of silver are required to buy one ounce of gold. The ratio tightened to about 54.94 before the summit and then widened back to roughly 59.15 by May 15, 2026. That four-point swing over several trading sessions is the largest round-trip in this ratio since early 2025 and highlights how much of silver’s short-term move was speculative, tied directly to trade hopes.
At $77.11, silver sits near the monetary support level that previously carried prices from $60 in late 2025 to a record high near $121 in January 2026. The long-run factors that supported that rally—persistent supply deficits, compressed real yields, and stress in the monetary system—remain in place.
So What Hasn’t Changed?
The supply deficit persists. The Silver Institute’s World Silver Survey 2026 documents six consecutive years of supply shortfalls, with a projected 46.3 million ounce deficit for 2026. Short-term political events do not alter that structural imbalance.
Monetary conditions, in some respects, worsened after the summit. The 10-year Treasury yield rose to 4.544%—its highest level since May 2025—adding pressure to nominal rates. April’s CPI reading showed inflation running at 3.8% year-over-year, and producer prices were near multi-year highs. Fed futures priced in a meaningful probability of an additional rate hike by year-end, reflecting a more hawkish end-of-year outlook.
In short, the industrial demand outlook for silver was dented by the lack of trade progress, while the monetary case — inflation pressures and central bank policy expectations — remains a supportive backdrop for precious metals.
SOURCES
1. nFusion Solutions — Silver & Gold Spot Prices — May 15, 2026
2. Silver Institute — World Silver Survey 2026 — Metals Focus, April 15, 2026
3. Coverage of the Trump-Xi Beijing summit and market reaction — news reports, May 15, 2026
4. US Bureau of Labor Statistics — Consumer Price Index — April 2026 (CPI data)
5. US Bureau of Labor Statistics — Producer Price Indexes — April 2026 (PPI data)
6. FRED, St. Louis Fed — 10-Year Treasury Constant Maturity Rate (DGS10)
7. CME Group — Fed rate probability pricing and market expectations, May 15, 2026
Disclaimer: This article is for informational purposes only and does not constitute financial or investment advice. Always consult a qualified financial adviser before making investment decisions.
You May Also Like:
- Gold Fell. China Bought Its Most in 17 Months. Here’s Why.
- Why Silver Falls Harder Than Gold — And What It Means
- Gold Near $4,700: The Chaos Isn’t a Ceiling. It’s a Floor
- 5 Forces Shaping Gold and Silver at the Beijing Summit
- The Real Reason Gold Falls When Inflation Surges
- CPI Hits 3.8%. Gold Falls. The Mechanism Nobody Explains
- Why the Gold-Silver Ratio Is Falling — and What It Means
- What’s Moving Gold Prices This Week: CPI, Seoul & Beijing
Popular Topics
Picked from the archive
-
01
 Topics
39% US Export Tax Sparks Reputation Fears for Swiss Gold Traders
-
02
Topics
Fed Policy Dilemma Fuels Gold Rally Amid Sticky Inflation
-
03
Topics
Gold Price: What Could Drive It to $6,300?
-
04
Topics
Why Silver Falls More Than Gold and What It Means for Investors
-
05
Topics
Treasury Secretary Urges Fed Rate Cut After Revised Jobs Report
-
06
Topics
Job Market Falters as Gold Nears $3,600
-
07
Topics
Gold vs Inflation: What 100 Years of Data Reveals
-
08
Topics
Switzerland Seeks US Pledge to Keep Gold Tariff-Free