How a Copper Mine Skipping Silver Explains the Deficit
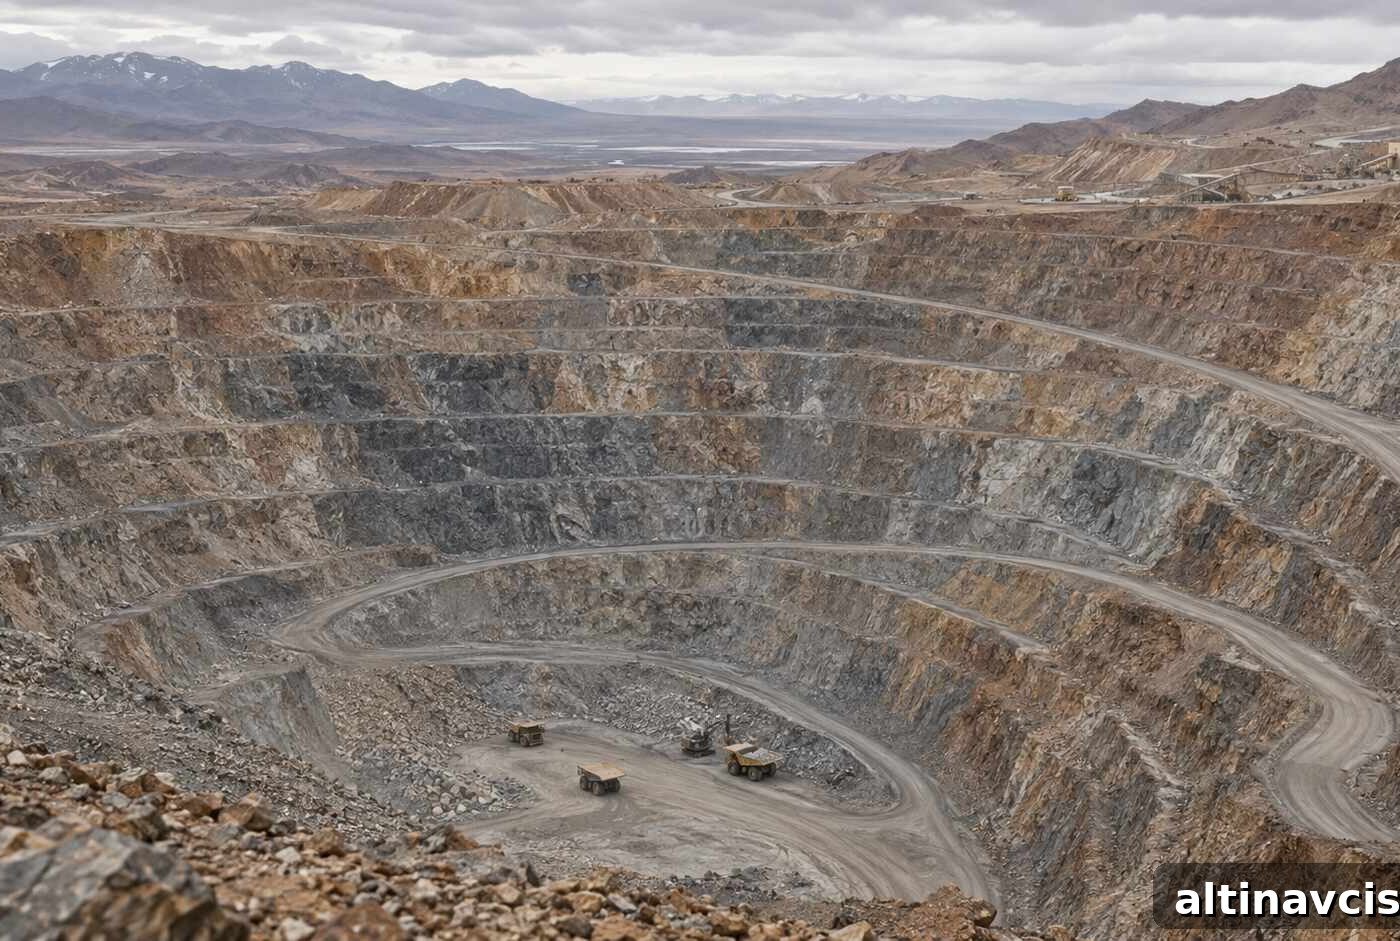
Byproduct silver mining refers to silver produced incidentally during extraction of other metals such as copper, lead, and zinc—not from mines developed specifically for silver. Because of this structure, an estimated 70–80% of the world’s silver supply does not expand in response to higher silver prices the way production from a dedicated silver mine would. That structural reality matters for market dynamics and explains why supply often cannot be ramped up quickly even as prices rise.
Three separate disruptions in August 2026 — a weather-driven shutdown in Chile, a temporary community blockade at a Mexican mine (now resolved), and a production decline in Peru — together removed roughly 1.1 million ounces of silver from expected output. That reduction equals about 2.4% of the Silver Institute’s projected 46.3 million ounce 2026 deficit. Crucially, these shortfalls were not driven by silver’s price but by events affecting mines where silver is a secondary product.
When silver supply is tied to the economics of other metals, the market has little direct control to call up additional ounces when they are needed. That structural limitation remains relevant even after any single disruption is resolved. The three incidents were compiled and reported in early September 2026.
Key Takeaways:
- Three unrelated events in August 2026 — weather-related guidance cuts in Chile, a now-resolved community blockade in Mexico, and a June production decline in Peru — together reduced silver supply by an estimated 1.1 million ounces, roughly 2.4% of the Silver Institute’s projected 46.3 million ounce 2026 deficit.
- Endeavour Silver’s Terronera mine in Jalisco, Mexico, resumed operations after a community blockade was lifted on August 24, 2026, according to the company’s disclosures.
- Approximately 70–80% of global silver mine supply is byproduct output of copper, lead, and zinc operations, meaning silver production decisions are usually driven by the primary metal’s economics rather than silver prices.
- 2025 is the fifth confirmed consecutive deficit year for silver; 2026 is forecast by the Silver Institute to be the sixth, but that remains a projection until final annual data are published.
- The structural fact that most silver cannot be quickly supplied in response to price underpins the case for physical, allocated ownership over unallocated paper claims, especially when the market is tight.
What Happened in August, and Is It Still Happening?
The essential point is straightforward: most silver comes as a secondary product from mines focused on other metals. For example, when Antofagasta cut its 2026 copper-production guidance on August 13 due to severe weather at its Los Pelambres operation in Chile, silver production tied to that copper mine was affected as well. Weather halted operations at a copper-producing site that also yields byproduct silver.
In Mexico, a blockade by an Ejido community halted operations at Endeavour Silver’s Terronera mine starting August 12. Company releases indicate that the blockade was lifted and full operations resumed on August 24, 2026. In Peru, government statistics reported a 9.0% year-on-year decline in silver production for June 2026. That June decline is a data point from earlier in the summer rather than an ongoing stoppage.
Combined, these three events account for an estimated 1.1 million ounce reduction in near-term supply. While this is a modest share of the projected annual deficit, it highlights a structural vulnerability: a market already running short has little spare capacity to absorb even modest supply losses, and there is no quick, price-driven lever to pull.
The Knowledge That Changes Everything
Two essential guides — free. Learn why gold matters and why fiat systems face recurring challenges.
Why Can’t Silver Mine Supply Increase When Silver Prices Rise?
Because most silver producers aren’t making decisions based on silver. About 70–80% of annual mine supply is a byproduct of copper, lead, and zinc operations. Those mines expand, contract, or invest based on the economics of their primary metal. A sudden rise in the silver price rarely changes decisions like opening a new pit, expanding a mill, or allocating capital for a multi-year project. As Americas Gold & Silver executive Oliver Turner observed, byproduct operations “can’t just turn on more silver supply when the world needs it”; their output depends on the supply chains and constraints of other metals.
Is 2026 Really the Sixth Straight Silver Deficit Year?
The Silver Institute’s World Silver Survey 2026 projects a 46.3 million ounce shortfall for the year. If that projection holds through final data, 2026 would mark a sixth consecutive year where demand exceeded supply plus recycling. It is important to distinguish between confirmed historical data and current projections: 2025 is the fifth confirmed deficit year; 2026 remains a forecast until final figures are published, typically the following spring.
How Much of the 2026 Deficit Do August’s Disruptions Actually Explain?
The three August events together account for approximately 1.1 million ounces, or about 2.4% of the projected 46.3 million ounce deficit. That number is meaningful but modest. The broader lesson is structural: when the market is already short, even relatively small, unrelated supply hits can matter because there is little spare capacity and no fast, price-driven mechanism to replace lost byproduct supply.
Is the Silver Deficit Getting Worse, or Just More Visible?
Both. The ongoing deficit measured in ounces is a continuation of a multi-year pattern that began in 2021. August’s incidents made the market’s structural limits more visible by providing concrete examples: weather in Chile, community disputes in Mexico, and production variances and regulatory issues in Peru. None of these causes were tied to silver’s price, which underscores that the constraint is structural rather than cyclical.
Why Does a Copper Mine’s Weather Problem Matter More Than a Silver Mine’s?
A weather problem at a copper mine matters to silver because the silver is produced incidentally at that copper operation. In practice, the copper mine’s operational decision becomes the silver story: decisions on drilling, milling, or shipping are based on copper economics, and silver output follows. That byproduct relationship helps explain why a persistent deficit can persist for years even as textbook supply-and-demand logic would suggest higher prices lead to increased production.
Even when individual mines return to normal, the underlying structure does not change. Variations in weather, community relations, ore grades, and regulatory processes recur annually, and none of these factors are reliably sensitive to the price of silver.
What Does This Mean for Gold, Silver, and Platinum Investors?
For investors choosing between paper exposure (ETFs, futures) and physical ownership, this structural dynamic is essential. Paper instruments represent claims on a price or on an issuer’s promise, while physical metal represents a claim on a specific, finite quantity of metal. When supply is constrained and largely byproduct-driven, the physical market’s ability to meet demand can be more fragile than paper prices imply. Growing industrial demand for silver — roughly 50–55% of annual usage for applications such as solar, electronics, and electric vehicles — combined with constrained supply strengthens the case for holding allocated physical metal if your objective is direct ownership of ounces rather than exposure to price alone.
Stay On Top of Gold & Silver Prices
Receive concise market alerts directly to your inbox.
Frequently Asked Questions
What is byproduct silver mining, and why does it matter for the silver price?
Byproduct silver mining produces silver incidentally while extracting a primary metal like copper, lead, or zinc. Since those operations make production and investment choices based on the primary metal’s economics, silver output is largely dictated by another metal’s market and supply-chain constraints. That is why rising silver prices often fail to trigger a proportionate increase in global silver production.
How is byproduct mining different from primary silver mining?
A primary silver mine exists because silver itself is worth extracting; its operators will typically respond directly to changes in the silver price. A byproduct operation produces silver incidentally and bases decisions on the economics of the main metal. Thus, silver from byproduct mines cannot be reliably scaled up or down solely in response to silver price movements.
How do I know if a silver supply disruption is still active or already resolved?
The most reliable source is the mine operator’s own public disclosures and press releases. Company statements typically report start and end dates for blockades, suspensions, or restarts. For example, statements from Endeavour Silver documented the timeline for the Terronera blockade and the resumption of operations on August 24, 2026.
What is the risk of holding paper silver versus physical silver during a supply deficit?
Paper silver instruments represent exposures to price or issuer claims and carry counterparty and structural risks that physical, allocated ownership does not. When supply is limited and driven by byproduct dynamics, the ability to obtain physical metal can be constrained; holders of allocated physical metal possess specific, identifiable ounces rather than a contractual claim.
What happens if the silver deficit keeps widening?
A widening deficit means demand continues to outpace mine production plus recycling, drawing down above-ground inventories built over years. Because byproduct-dominated mine supply and recycling cannot quickly replenish those stocks, persistent deficits can place sustained pressure on the physical market unless mine supply responds faster or industrial demand falls.
Is the silver deficit confirmed for 2026, or still a forecast?
As of this writing, the Silver Institute’s 46.3 million ounce figure for 2026 remains a projection. Final confirmation requires year-end data and the Institute’s subsequent reporting; 2025 is the most recent year with confirmed deficit data.
SOURCES
1. Silver Institute — Silver Market in a Deficit for Fifth Straight Year — Apr 15, 2026
2. Crux Investor — Mine Disruptions Test Whether The 46.3 Million-Ounce Silver Deficit Can Close — Sept 4, 2026
3. Endeavour Silver Corp. — Reports on a blockade and suspension at Terronera — Aug 16, 2026 (company disclosure)
4. Investing News Network — Report on removal of blockade at Terronera — Aug 24, 2026
5. GoldSilver — Silver Price Outlook September 2026 — Sept 14, 2026
Disclaimer: This article is informational and not investment advice. Past performance does not guarantee future results. Consult a qualified financial advisor before making investment decisions.
You May Also Like:
- Inherited Gold IRA: Beneficiary Rules & the Step-Up Basis Gap
- The Cantillon Effect: Why Money Printing Makes Some People Rich First
- Silver Price Outlook September 2026: The Hike Is Priced In. The Positioning Isn’t.
- Gold Is About to Face Its First Rate Hike of the Cycle. Here’s Why It Isn’t Scared.
- How Much Gold Should You Own at 25, 45, or 65?
- Gold Price Outlook September 2026: What the Fed’s September 15–16 Meeting Means for Your Metals
- Do You Have to Report Gold Stored in a Foreign Vault? FBAR and FATCA Rules Explained
Popular Topics
Picked from the archive
-
01
 Topics
Gold Nears $4,700, Silver Above $69: Markets Eye Friday Speech
-
02
Topics
Why Gold Remains Resilient Amid the First Interest Rate Hike
-
03
Topics
Gold at $4,502: Is This Dip a Buy? BofA Sees $6,000
-
04
Topics
How to Buy Silver Bullion 2026: Coins, Bars and Rounds Compared
-
05
Topics
What’s Driving Gold Prices This Week: CPI, Seoul and Beijing
-
06
Topics
Why Gold Prices Are Falling Amid the Oil War
-
07
Topics
July 2026 Silver Outlook: Two Catalysts Set to Move Prices
-
08
Topics
Silver Appears Weak, Silver-to-Gold Ratio Signals Accumulation