Hormuz Crisis and Fed Policy: Markets Race to Gold and US Dollar
Daily News Nuggets | Today’s top stories for gold and silver investors
March 3rd, 2026 | Brandon Sauerwein, Editor
Gold Falls as the Dollar Claims the Safe-Haven Crown
Gold prices plunged on Tuesday, at one point dropping more than 4%, while silver tumbled even more sharply, falling as much as 8% intraday. Rather than moving into precious metals, many investors sought refuge in the U.S. dollar as U.S.–Israeli airstrikes on Iran intensified. Spot gold fell to its lowest level since February 20.
This sudden rotation highlights a shift in which assets investors view as safest during heightened geopolitical risk. For now, the dollar is outperforming gold as the preferred haven. That preference can change quickly, but in the short term monetary policy expectations are carrying more weight than traditional flows into bullion.
Traders also pared back expectations for near-term Federal Reserve rate cuts. The reason: rising energy prices tied to the conflict could rekindle inflationary pressure, leaving the Fed less room to ease policy. When markets scale back rate-cut bets and the dollar strengthens, gold typically faces headwinds even amid geopolitical turmoil because higher real rates tend to diminish bullion’s appeal as a non-yielding asset.
Still, the dollar’s role isn’t the only factor. The conflict threatens a major global energy corridor, which introduces a persistent supply risk that can push energy prices higher and feed into broader inflationary trends — a dynamic that ultimately feeds back into central bank decisions and precious metals’ long-term outlook.
Iran Moves to Choke the World’s Most Critical Oil Passage
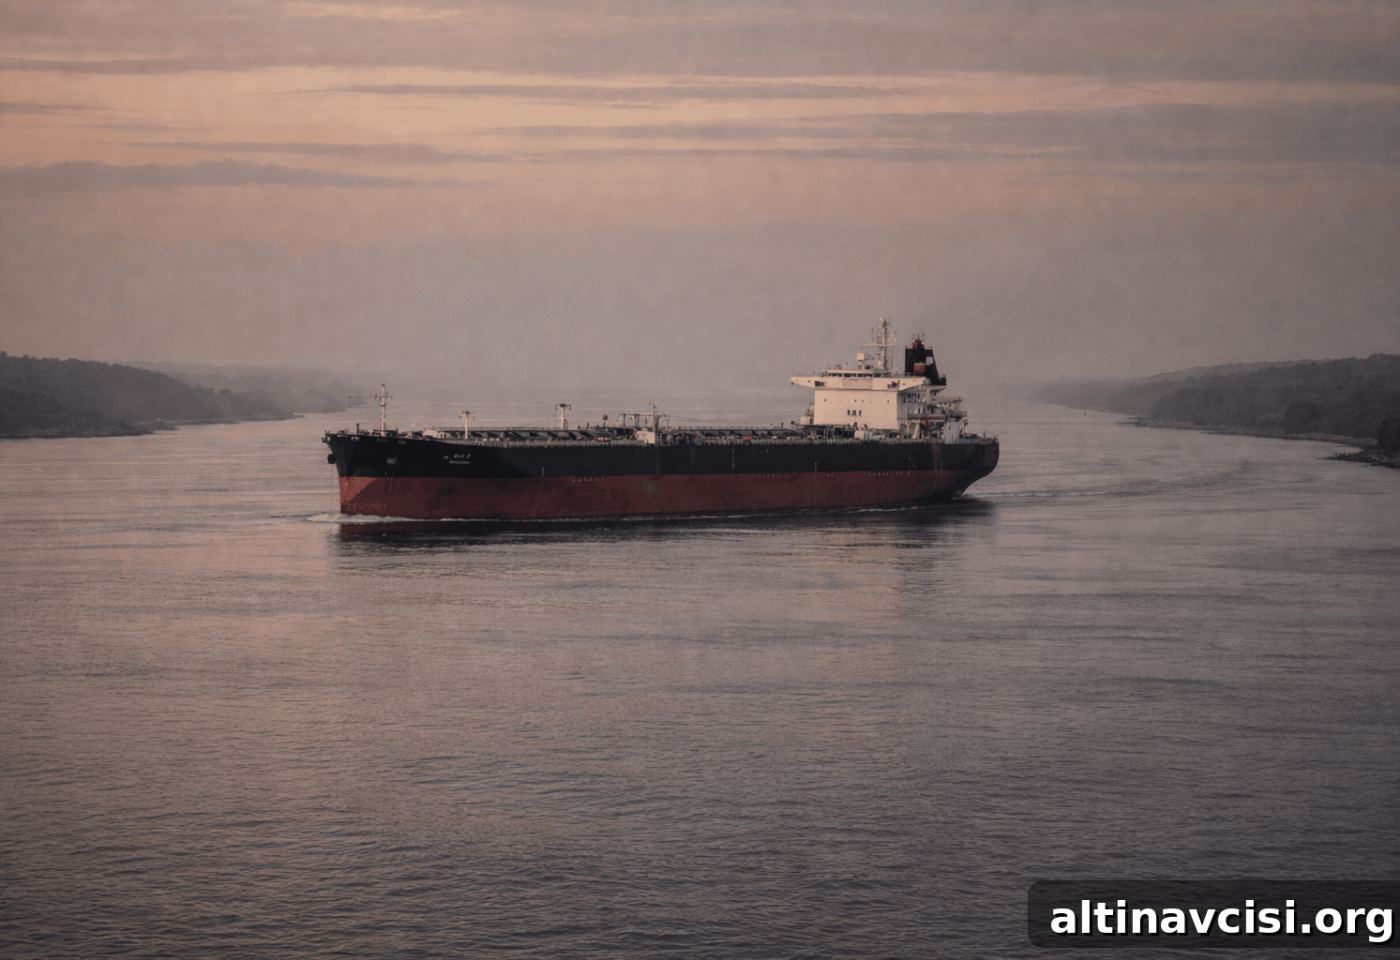
Ships transiting the Persian Gulf have been receiving an unusual radio message instructing them to avoid the Strait of Hormuz. The transmission is attributed to Iran’s Islamic Revolutionary Guard Corps, and shipping operators appear to be complying. Although Iran has not formally declared a blockade, many carriers are suspending voyages and insurers are withdrawing war-risk coverage, creating an effective stoppage in parts of the trade.
The Strait of Hormuz is a vital chokepoint: roughly one-fifth of the world’s oil and liquefied natural gas flows through this narrow waterway. Even temporary disruptions can push energy prices higher and produce spillover effects across inflation data, central bank deliberations, and global markets. The immediate economic impact is already visible as energy-driven volatility ripples through equities and fixed income.
Beyond the direct supply implications, interruptions to shipping and insurance markets introduce uncertainty into global trade and logistics. Companies may delay shipments or reroute vessels, which increases costs and delivery times. That uncertainty compounds the inflationary impulse from higher fuel prices and raises the stakes for policymakers monitoring economic stability.
Oil Surges, and the Everything Selloff Begins
As tensions in the Middle East rose, oil prices jumped on Tuesday morning and markets reacted sharply: global stocks fell, government bonds sold off, and yields climbed. That simultaneous movement across major asset classes is notable because it signals broader macro stress rather than routine sector rotation.
When stocks and bonds decline together, investors lose the usual diversification benefit of owning both equities and fixed income. The bond market selloff reflects growing concern that energy-driven inflation could persist, thereby reducing the likelihood of near-term rate cuts and keeping monetary policy tighter for longer. At the same time, higher energy costs squeeze corporate margins and can damp consumer demand, pressuring equity valuations.
Those twin pressures are reviving fears of stagflation — an economic environment of slowing growth coupled with elevated inflation. Stagflation is especially challenging for conventional portfolios because neither stocks nor bonds reliably protect purchasing power. In such times, some investors look to real assets and precious metals as partial hedges against persistent inflation and policy uncertainty.
The Federal Reserve now faces a narrower set of policy choices. If officials ease policy too soon, they risk reigniting inflation; if they hold tight for too long, the economy may slow further. That tension is central to market pricing and to how investors allocate across currencies, commodities, and safe-haven assets like gold.
The Financial System Isn’t Safer — And You Know It
As global risks intensify, discover why many analysts expect gold and silver to remain important parts of portfolios in 2026 and beyond.
The Fed Is Caught Between Inflation and a Slowdown
The Federal Reserve faces a difficult trade-off. Rising oil and other energy costs are pushing yields higher and reducing market expectations for rate cuts, even as broader economic momentum shows signs of cooling. That combination — slowing growth alongside persistent price pressures — is the classic definition of stagflation.
Policymakers must weigh the risk that cutting rates too soon would allow inflation to reaccelerate against the danger that keeping policy restrictive for too long will exacerbate an economic slowdown. Markets are already reflecting that uncertainty: bond investors expect fewer cuts and a longer period of restrictive policy than they did previously, which is a signal that confidence in a smooth soft landing has weakened.
Historically, uncertain policy and sticky inflation tend to elevate interest in tangible stores of value. Gold, in particular, has often been positioned as a form of insurance when financial systems face stress that central banks cannot easily resolve with conventional tools. Institutions and long-term investors responding to this risk environment are increasingly factoring precious metals into their allocation decisions.
JPMorgan and UBS Are Helping Singapore Become Asia’s Gold Capital
Singapore is actively positioning itself as a major regional hub for gold, and it has enlisted large international banks to help build that capability. JPMorgan and UBS are working with Singapore to expand bullion market liquidity, develop vaulting and custody infrastructure, and attract institutional flows into the city-state’s markets.
Several structural advantages support Singapore’s ambitions: it does not levy GST on investment-grade precious metals, it has a stable regulatory framework, and its geographic position places it close to the two largest centers of gold demand, China and India. As global market fragmentation accelerates and investors diversify where they store assets, Singapore aims to offer a neutral, politically stable alternative to existing vaulting centers.
These developments reflect a broader eastward shift in gold demand and settlement activity. By enhancing physical and financial infrastructure, Singapore hopes to capture a growing share of that flow and to serve as a regional anchor for institutional bullion trading and custody.
You May Also Like
- Gold Prices Surge on Middle East Tensions
- Gold Above $5,200, Silver Above $90 — as Inflation Refuses to Fade
- Gold Price Rally Nears Record Streak as Tariffs Return
- Metals Rise, Confidence Cracks, and the Affordability Gap Widens
- Gold Up 21%, Silver 25% YTD as AI and Inflation Risks Build
Popular Topics
Picked from the archive
-
01
 Topics
Gold Price Could Reach USD 5,000 by 2026: Institutional Forecast
-
02
Topics
Silver Squeeze Pushes Silver Prices Above $51
-
03
Topics
Gold Rises as Bitcoin Slips and Bubble Fears Grow
-
04
Topics
Bessent Urges 1.5% Rate Cut, Boosting Gold Prices
-
05
Topics
Tariff Deadline Fears Push Gold Prices Up as Other Metals Slide
-
06
Topics
Gold Fields Urges Major Miners to Boost Gold Exploration
-
07
Topics
Tech Giants Drive 90% of Earnings Growth Despite Trade War Fears
-
08
Topics
Brazil Threatens Retaliation After Trump Imposes 50% Tariff