Gold Price Could Reach USD 5,000 by 2026: Institutional Forecast
Gold reached record highs this year as powerful macro forces reshaped the market. As investors search for a reliable gold price prediction 2026, one signal stands out: institutional investors broadly expect gold to continue climbing.
A Goldman Sachs Marquee survey of more than 900 institutional clients conducted November 12–14 found that nearly 70% believe gold prices will be higher by the end of 2026, and the largest single group—36% of respondents—predicts gold will break above $5,000 per ounce within the next year. These results underscore how the professional investment community is positioning for an extended bull market in precious metals.
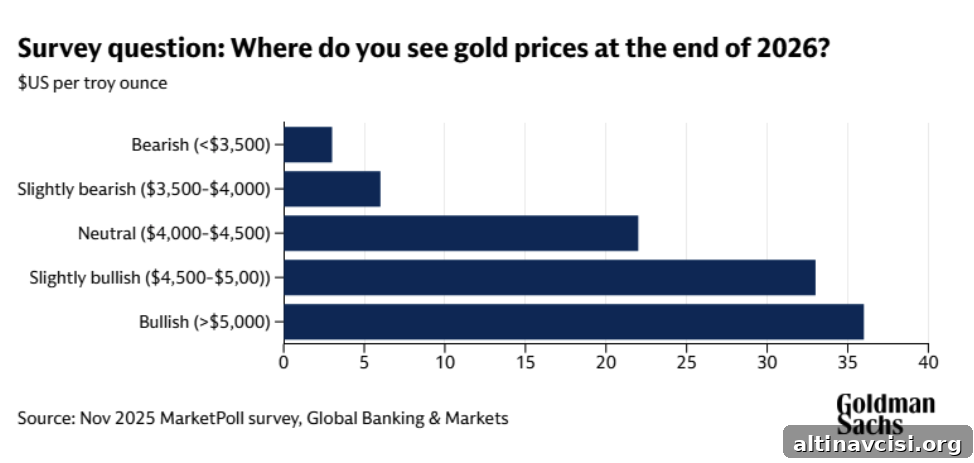
This institutional bullishness reflects a broader shift in gold’s role within modern portfolios. With central banks buying at unprecedented levels, real interest rates fluctuating, and geopolitical risks increasing, many investors now view gold as a strategic asset rather than only a defensive hedge. The same drivers that pushed gold into new territory across 2024 and 2025 remain active and continue to support upside momentum into 2026.
What is most striking is the confidence behind the forecasts. Institutional desks—typically conservative in their projections—are positioning gold as a core allocation rather than a marginal defensive holding.
If the world’s largest financial institutions expect higher gold prices, is your portfolio prepared for the same environment?
Why Institutions Are Bullish on Gold
Institutional investors rarely make aggressive bets, so their consensus carries weight. When nearly seven in ten professionals expect gold to be higher within 24 months, it signals that durable structural drivers are supporting the outlook for gold price forecast 2026.
1. Gold is behaving differently than the old playbook predicted.
Traditionally, higher real interest rates pressured the price of gold. Over the last two years, however, gold has decoupled from that historical relationship: despite aggressive rate hikes in many markets, gold has continued to rise. That shift suggests a market increasingly influenced by sovereign buyers and emerging-market demand rather than only Western financial flows.
2. Persistent macro uncertainty is now the norm.
Investors are navigating a landscape defined by:
- Sticky inflation in services, wages and energy
- Growing sovereign debt burdens
- Shifting monetary policy frameworks and debate over central bank independence
- Trade realignments and “friend-shoring”
- Escalating geopolitical tensions and fragmentation
In this environment, assets with no counterparty risk, such as gold, become more attractive as portfolio anchors.
3. Structural demand now outweighs price-sensitive demand.
Demand from central banks and consumers in emerging markets tends to be strategic and less sensitive to short-term price swings than ETF flows in Western markets. That dynamic means dips are often met with quick buying, establishing a stronger market floor and supporting long-term price stability.
Central Bank Demand Hits Multi-Decade Highs
One of the most consequential drivers for gold today is sovereign accumulation. Central bank purchases have reached the highest sustained rates seen in modern times, and that trend remains a core structural force behind the gold price forecast 2026.
Why are central banks adding gold?
- Diversification away from dollar-dominated assets
- Protection against sanctions and political risk
- Strengthening national reserves
- Insurance against currency volatility
- Preference for assets without counterparty risk
Central banks tend to buy gold for strategic reserve management rather than short-term trading. As a result, their accumulation reduces available supply and creates a durable support level for prices. Recent data indicate net global purchases have roughly doubled compared with pre-2022 norms, and large buyers—including major emerging economies—have been consistently active in the market.
Geopolitical Drivers: A World Reordering Around Risks
Geopolitical fragmentation and realignment are amplifying demand for neutral, stateless assets. As alliances shift and trade patterns evolve, gold’s appeal grows across multiple investor types.
1. East–West tensions are reshaping global trade.
U.S.–China rivalry, sanctions, tariff changes and policies encouraging friend-shoring are rewiring global supply chains and contributing to currency volatility and inflationary pressure—conditions that historically favor gold.
2. Conflicts and instability raise safe-haven demand.
Regional wars and geopolitical flashpoints prompt investors and sovereigns to re-evaluate risk exposure, often increasing allocations to gold as a politically neutral store of value.
3. De-dollarization and a multipolar world.
Some countries are diversifying reserve holdings away from the dollar, viewing gold as a neutral alternative for reserves and settlement. In a more multipolar environment, the traits that make gold valuable—no counterparty risk, no liability, lack of political attachment and no default risk—are increasingly prized.
Inflation, Debt, and Policy Uncertainty
Inflation dynamics, rising public debt and unpredictable policy choices remain core gold price drivers.
Sticky inflation: Structural inflation in services and wages can keep real yields low and push investors toward tangible stores of value.
Rising debt: Higher government borrowing increases the likelihood of prolonged periods of low or negative real interest rates, historically supportive of gold.
Policy uncertainty: Rapid shifts in monetary policy, political debates over central bank mandates, and fiscal pressures make long-term pricing harder to forecast—another factor that tends to benefit precious metals.
What This Means for Investors
When institutional forecasts, central bank accumulation, geopolitical realignment and inflationary pressures align, they create a powerful long-term backdrop for gold. The gold price forecast 2026 is not just a speculative target—it’s a synthesis of structural trends that are already affecting supply and demand.
For individual investors, the practical question is one of positioning: if major institutions and sovereign buyers are preparing for higher gold prices, how should a diversified portfolio reflect that environment? Considering allocations to physical metal, allocated storage, or gold-linked instruments can be part of a broader risk-management and diversification strategy.
The Financial System Isn’t Safer — And You Know It
As risks mount, see why gold and silver are projected to remain important portfolio anchors into 2026 and beyond.
People Also Ask
What is the gold price forecast for 2026?
Many institutional investors expect gold prices to rise into 2026, with a significant portion forecasting levels above $5,000 per ounce. That outlook is driven by strong central bank demand, geopolitical uncertainty, and persistent inflationary pressures.
Why do institutions think gold will go up in the next few years?
Institutions point to sustained buying by central banks, continued demand from emerging markets, growing geopolitical risks and high global debt as the main reasons they expect higher gold prices over the coming years.
How do central banks influence the gold price?
Central banks increase demand and reduce available supply when they add gold to reserves. Because central banks typically hold gold for long periods, their purchases can establish a durable support level that helps lift and stabilize prices over time.
What geopolitical events could push gold higher by 2026?
Escalating tensions between major powers, regional conflicts, disruptions to trade and a wider move toward de-dollarization can all increase safe-haven demand and support higher gold prices.
How does inflation affect the gold price forecast for 2026?
Persistent or structural inflation erodes purchasing power, prompting investors to seek real assets. Even if headline inflation moderates, elevated costs in services and wages can keep demand for precious metals robust.
Popular Topics
Picked from the archive
-
01
 Topics
Gold Prices Near $4,000 as Job Cuts Reach 20-Year High
-
02
Topics
Bessent Urges 1.5% Rate Cut, Boosting Gold Prices
-
03
Topics
Why Wealthy Investors Allocate 11% of Portfolios to Gold
-
04
Topics
10-Year Treasury Yield Tops 4.4% on Resilient Labor Market
-
05
Topics
US Dollar Strengthens Ahead of Major Trade Policy Announcements
-
06
Topics
ECB Reaches 2% Inflation Target in June as Eurozone Prices Hold
-
07
Topics
Consumer Prices Rise as Trump Trade War Hits Home
-
08
Topics
Visa Adds PayPal USD, Global Dollar and New Blockchains