Could the U.S. Government Seize Your Gold Again?
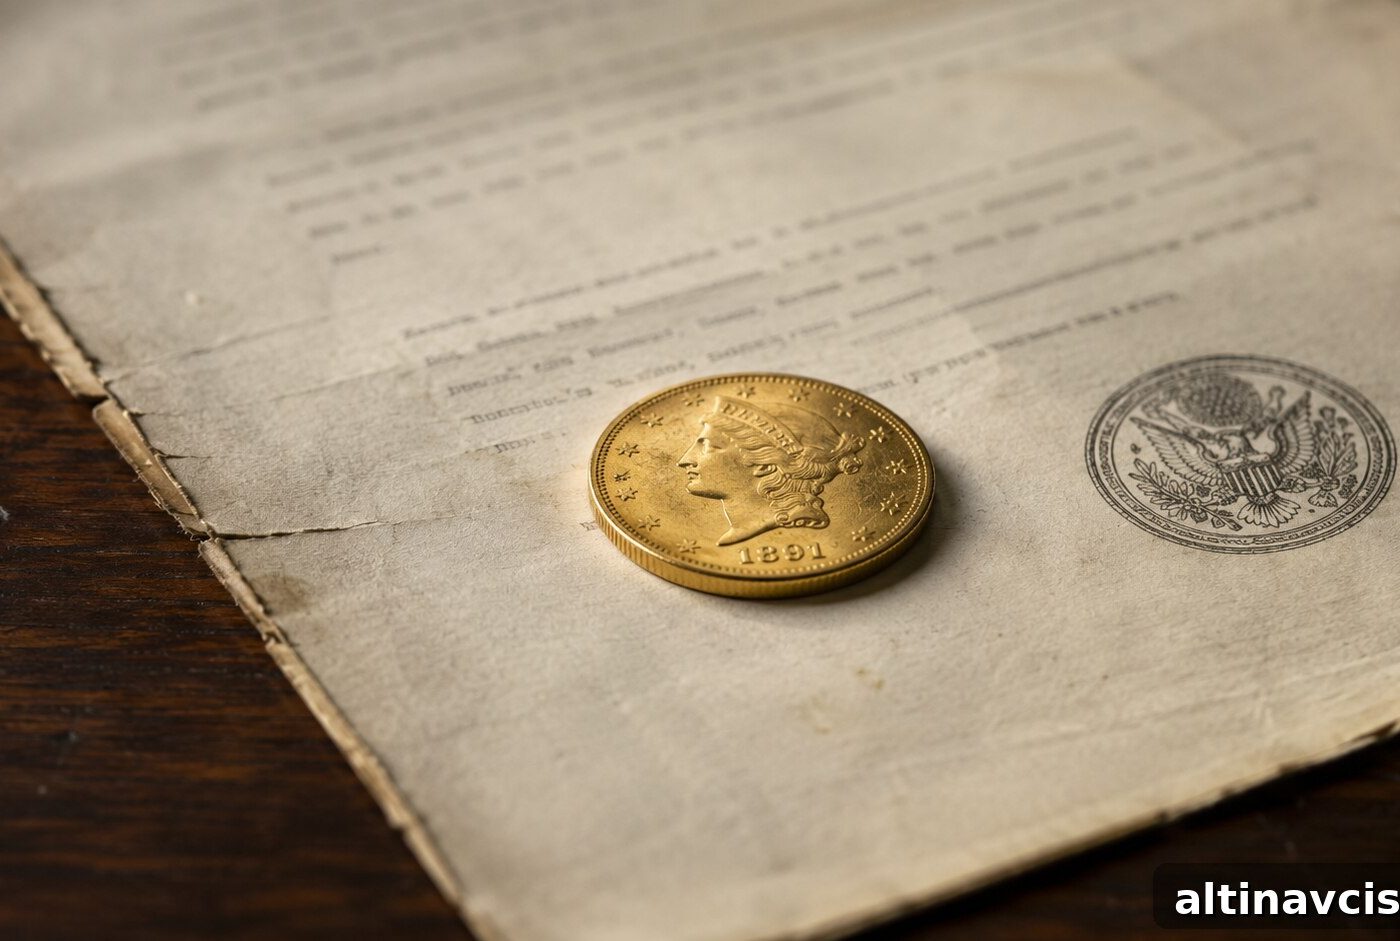
In 1933 the US government required citizens to surrender most private gold holdings within weeks. Executive Order 6102 fixed the exchange price at $20.67 per troy ounce and threatened fines and prison time for noncompliance. Most people turned in their coins and certificates. Within a year Congress revalued gold to $35 per ounce, creating a large gain for the Treasury. That event — lawful, effective, and lasting — is the historical basis for today’s questions about whether the government could repeat a similar action.
This article explains what happened in 1933, the legal mechanics that enabled it, why private ownership was later restored, the statutory changes that narrowed presidential emergency powers, and how modern ownership forms affect the actual risk for today’s investors.
Quick summary
- Executive Order 6102 (April 5, 1933) required most Americans to deliver gold to Federal Reserve Banks at $20.67/oz; the government later revalued gold to $35/oz.
- Private ownership of gold was effectively banned until Congress restored it by statute at the end of 1974; private trading resumed on January 1, 1975.
- Legislative changes in the 1970s, notably the International Emergency Economic Powers Act (IEEPA) and related statutes, raised the legal threshold for presidential restrictions on gold transactions.
- Today the realistic risks are regulatory constraints on transactions, reporting or export controls — not a wholesale forced surrender at a government price like 1933.
What was Executive Order 6102 — and what did it actually do?
On April 5, 1933, President Franklin D. Roosevelt issued Executive Order 6102, titled “Forbidding the Hoarding of Gold Coin, Gold Bullion, and Gold Certificates Within the Continental United States.” The order rested on emergency authority for use during a declared banking crisis; Congress had recently amended the Trading with the Enemy Act to extend emergency powers domestically during that banking emergency.
The order required most persons, partnerships and corporations to deliver gold coin, bullion, and gold certificates to a Federal Reserve Bank by a set deadline, with payment at the statutory rate of $20.67 per troy ounce. Important exemptions existed: rare numismatic coins, gold used in industry or the arts, and a small amount of coins per person for limited use.
How the government profited — and why most Americans complied
The order was not an uncompensated seizure; it was a forced exchange at a government-set price. The crucial follow-up was the Gold Reserve Act of 1934, which revalued gold to $35 per ounce and transferred legal title of monetary gold to the Treasury. The government thus acquired gold at $20.67 and accounted for it at $35, creating a substantial gain on the metal it collected.
Enforcement varied, but broad compliance arose because the government removed gold’s role in commerce. Once gold could not function as money within the legal system, holding it offered little practical benefit for everyday transactions. That loss of utility — more than prosecutions — drove widespread surrender.
Why did FDR have the authority to do this?
The 1933 action depended on a specific legal sequence: a declared national banking emergency, statutory amendments extending emergency trading powers to domestic situations, and an economy operating on the gold standard where gold underpinned the monetary base. The Supreme Court later upheld related actions in the Gold Clause Cases, accepting Congress’s power to alter contractual gold clauses under those exceptional conditions.
Those structural conditions mattered. The policy required (1) a gold-backed monetary system, (2) emergency enabling legislation, and (3) executive action in that emergency. Absent any one of these, the same mechanism would be far harder to apply.
Was private gold ownership ever restored?
Yes. Restrictions loosened gradually in the 1960s and 1970s. By 1964 the Treasury stopped requiring citizens to surrender gold acquired abroad. Congress then passed Public Law 93-373 in 1974, and on January 1, 1975 private ownership and trade in gold became legal again. Since restoration, private ownership has persisted through multiple major crises without a repeat of confiscation.
Notable crises since 1975 include stagflation in the 1970s, the savings and loan collapse, the 2008 financial crisis, the COVID-19 pandemic and recent inflationary pressures. None prompted a return to forced surrender at fixed government prices.
What is the 1977 law that changed presidential authority?
In 1977 Congress passed the International Emergency Economic Powers Act (IEEPA) and related reforms that clarified and limited presidential economic emergency powers. Under current law, the president may exercise certain controls over transactions only in the event of a Congressional declaration of war or after declaring a national emergency under the National Emergencies Act — and those powers are subject to Congressional oversight and termination. The statutory framework narrows the unilateral route that existed under the earlier Trading with the Enemy Act.
Could gold confiscation happen again?
The short, candid answer is: technically possible but highly unlikely in the same form as 1933. Three reasons explain why.
First, the structural need is gone. The US no longer operates under a gold standard; the Fed issues currency through credit mechanisms, so the government does not require private gold to expand the monetary base.
Second, the legal bar is higher. Modern statutory limits require a formal national emergency or a declaration of war to enact broad transaction prohibitions, and any such measure would face immediate and sustained judicial review.
Third, the political reality differs. Physical precious metals are now widely held across many households; large-scale confiscation of assets from millions of individual investors would be politically fraught and likely provoke intense opposition.
That said, more targeted regulatory actions remain plausible in extreme circumstances: reporting requirements, temporary export controls, limits on certain types of transactions, or capital controls. These are materially different from the 1933 model of forced surrender and fixed-price exchange.
What does modern gold ownership mean for this risk?
How you hold gold affects exposure. In 1933 most private gold existed as circulating coins, gold certificates or bullion held inside the domestic banking system — readily identifiable and easy to control. Today ownership structures are more diverse: allocated and segregated vault accounts provide specific legal title to identified bars or coins; offshore storage places the metal under another jurisdiction’s laws; and many investors hold coins, private bars, or bullion in secure private facilities.
Allocated, segregated holdings and storage outside the United States change the legal and practical calculus compared with the instruments targeted in 1933. Paper gold products, pooled or unallocated accounts, and certain ETFs carry different counterparty and regulatory risks than direct, allocated physical ownership.
Why the structural case for gold today is different from 1933
Today many investors hold gold as a hedge against currency debasement and extreme monetary policy, not as a component of the official monetary base. That shift in purpose and legal architecture means the incentive and mechanism that produced the 1933 action are not present in the same way now. Gold’s market price has reflected this freedom; long-term price appreciation since the early 1970s reflects market forces and concerns about purchasing power, not confiscation dynamics.
Key takeaways
- The 1933 confiscation under Executive Order 6102 was real and legally supported by emergency statutes and a gold-backed monetary system; those particular conditions no longer exist.
- Private ownership was restored in 1975 and has persisted through multiple crises without repeat confiscation.
- Legislative reforms in the 1970s substantially narrowed the executive route for broad asset restrictions; a declaration of war or a formal national emergency is now required for comparable measures.
- Modern risks are more likely to be regulatory constraints on transactions — reporting, export controls, or temporary limits — rather than forced surrender at a government-set price.
- Ownership structure matters: allocated, segregated holdings and offshore storage present a different risk profile than pooled or paper gold instruments.
People also ask
Did the US government really confiscate gold from citizens?
Yes. Executive Order 6102 required citizens and many businesses to deliver most gold holdings to the Federal Reserve at a fixed price in 1933; exemptions existed for certain coins and industrial uses. The Gold Reserve Act of 1934 revalued gold and confirmed Treasury title to monetary gold.
Can the US government confiscate gold today?
While the government retains broad emergency powers, modern statutes and the absence of a gold standard mean a repeat of 1933-style confiscation is unlikely. Any attempt would require a high statutory threshold and prompt legal challenges. Regulatory restrictions remain theoretically possible during extreme emergencies.
What was the punishment for not turning in gold in 1933?
Executive Order 6102 prescribed civil penalties up to $10,000 and criminal penalties up to ten years’ imprisonment for violations, plus forfeiture of withheld gold. In practice, enforcement focused more on reducing gold’s role in commerce than on mass prosecutions of individual holders.
Is gold confiscation risk a reason not to buy gold?
Most analysts do not view modern confiscation risk as a primary deterrent to owning physical gold. Key considerations include legal protections restored since 1975, higher statutory thresholds established in the 1970s, the political implications of large-scale seizures, and the option to hold allocated, segregated or offshore holdings. For most investors, gold’s role as a long-term hedge and portfolio diversifier remains the central rationale.
How do you protect gold from government confiscation?
Common risk-mitigation steps include holding allocated, segregated physical metal rather than pooled or unallocated accounts; diversifying storage across reputable jurisdictions; avoiding exclusive reliance on paper gold instruments that do not convey direct physical ownership; and using secure private vaults or trusted custodians. No strategy removes all risk in an extreme scenario, but ownership structure materially affects exposure.
Sources
National Archives — Executive Order 6102 (April 5, 1933); Federal Reserve History — gold and convertibility; Cornell Law School — IEEPA and 50 U.S.C. § 4305; Congress.gov — Public Law 93-373 (1974); Bureau of Labor Statistics CPI data; World Gold Council research on demand and ownership trends.
Disclaimer: This article is for informational and educational purposes only. It does not constitute investment advice. Consult a qualified financial adviser before making investment decisions.
You may also like:
- Gold price history and long-term trends
- The debasement trade: mechanism and implications
- Gold vs. silver: a first-time buyer’s decision framework
- Gold reserves by country — contemporary rankings
- Portfolio allocation and precious metals in modern portfolios
The Knowledge That Changes Everything
Two essential guides — yours free. Understand why gold matters and why fiat currencies face long-term pressures.
Popular Topics
Picked from the archive
-
01
 Topics
Market Movers Aug 25: Gold Pullback, Jackson Hole, Intel Warning
-
02
Topics
Silver Price Jumps 7% as Bulls Gain Momentum
-
03
Topics
Gold Price Falls Today: Why $4,500 Holds as Support
-
04
Topics
Barrick CEO: Gold Miners Unfazed by U.S. Tariffs on Bullion Bars
-
05
Topics
After January Jobs Surprise, Silver Dips as Gold Holds Firm
-
06
Topics
Gold Surges to Record High as $5,000 Target Nears
-
07
Topics
Why China’s Silver Imports Soared to a Record in 2026
-
08
Topics
Dollar Steadies After Jobs Data Shock Sends 90% Odds of Fed Cut