TIPS vs Gold: Which Protects Your Wealth From Inflation?
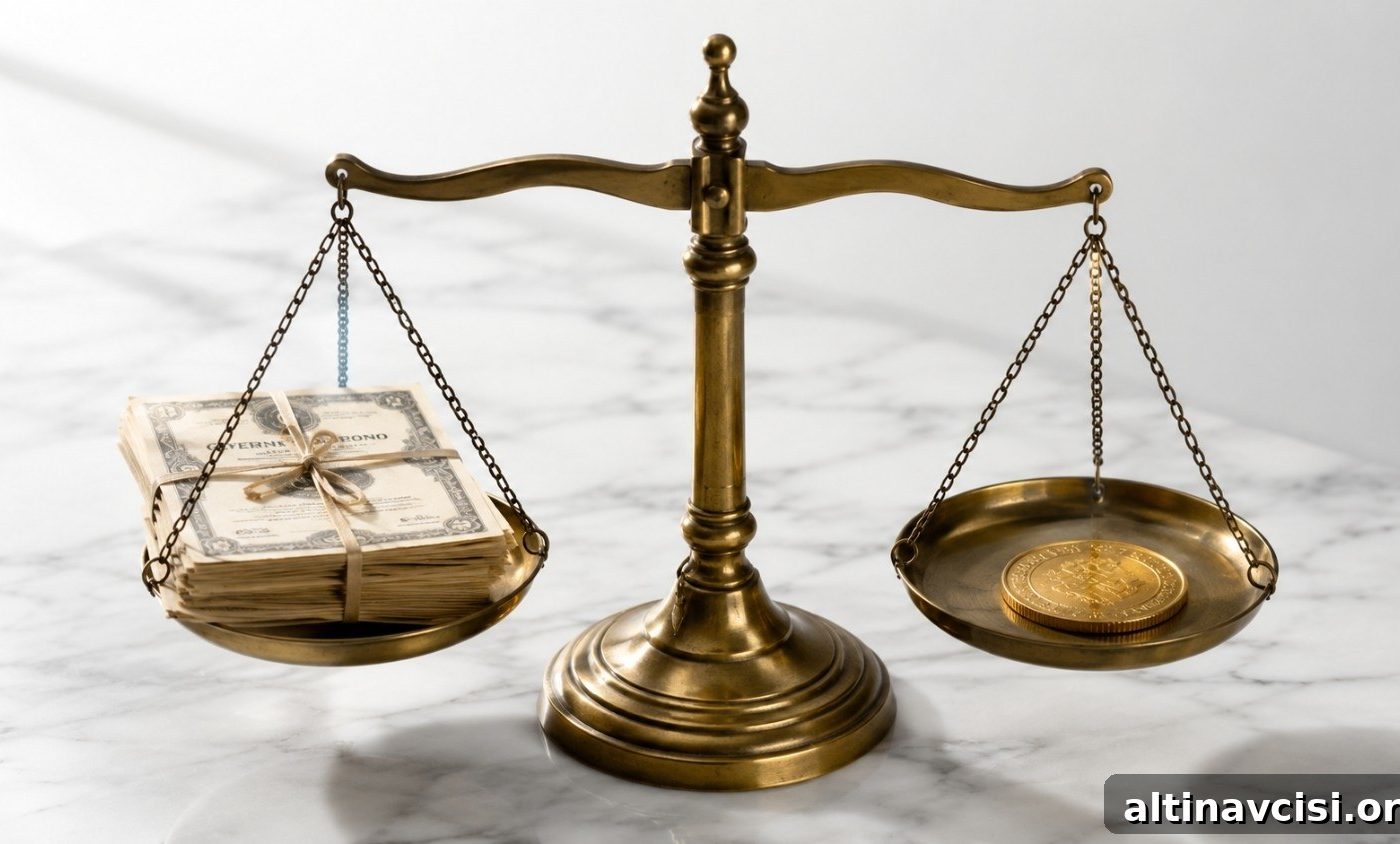
Most investors encounter gold and TIPS in separate conversations — gold from advocates of sound money and TIPS from fixed-income desks. Rarely are they compared directly, yet they compete for the same role in a portfolio: preserving purchasing power. Because they respond differently to distinct inflation scenarios, understanding how gold and TIPS diverge is one of the most practical steps a long-term investor can take.
Below is a clear, practical comparison of gold versus TIPS that many financial outlets don’t explain well. Both instruments deserve consideration, but they are not interchangeable.
What Are TIPS and How Do They Work as an Inflation Hedge?
TIPS (Treasury Inflation-Protected Securities) are U.S. Treasury bonds whose principal is automatically adjusted by changes in the Consumer Price Index (CPI). If you hold $10,000 in TIPS and CPI rises by 3% over the year, the principal is adjusted to $10,300, and future interest payments are calculated on that higher amount. At maturity, investors receive the greater of the inflation-adjusted principal or the original par value.
The key feature of TIPS is that they provide a government-backed real return above the official CPI. The 10-year TIPS real yield — a commonly referenced gauge — is currently near 2.21% (Federal Reserve / FRED, June 2026). In practical terms, buying 10‑year TIPS today locks in a real return roughly equal to that yield, above the CPI reported by the government.
On paper, TIPS are a near‑ideal inflation hedge: the principal tracks CPI mechanically and the real yield is fixed at purchase. That mechanical clarity is why TIPS are the default starting point in any comparison with gold.
However, three important caveats change how TIPS perform in practice.
The Knowledge That Changes Everything
Two essential guides — free: one explains why gold matters, the other explores the long history of fiat currency failure.
To request these guides, visit the publisher’s site or contact customer support. (Form and script content removed.)
What Are the Hidden Risks of TIPS That Investors Overlook?
1. Duration risk. Like all bonds, TIPS lose market value when nominal interest rates rise. In 2022, for example, aggressive rate hikes caused many TIPS funds to report significant losses — the iShares TIPS Bond ETF returned roughly -12% that year even while headline inflation was above 8%. The CPI-linked principal adjustment helped, but rising real and nominal yields pushed prices down for anyone who sold before maturity. Investors holding individual TIPS to maturity received the inflation-adjusted principal; those in funds were exposed to price volatility.
2. They hedge official CPI, not necessarily your lived costs. TIPS adjust with the government’s CPI measure, which reflects a specific basket of goods and services. Many people experience faster inflation in areas like housing, healthcare, or education than CPI reports. That means TIPS guarantee a real return above measured CPI, not necessarily above your personal cost-of-living increase.
3. Sovereign and credibility risk. TIPS are promises from the U.S. government. Historically reliable, these promises gain their value from the government’s fiscal position and institutional credibility. If fiscal pressure mounts significantly — as budget deficits and interest expenses grow — that same government may face strains that raise questions about long-term monetary credibility. That possibility does not imply imminent default, but it does mean TIPS expose holders to a circular risk: the issuer of the hedge can also be a primary driver of future inflationary pressure.
How Does Gold Compare to TIPS as an Inflation Hedge?
Gold provides no guaranteed return: it pays no interest or dividends and has no mechanical CPI adjustment. By the strict definition of an inflation hedge — an asset that directly tracks CPI — gold does not qualify. Historically, the rolling five-year correlation between gold prices and CPI has been low, indicating that monthly CPI movements explain only a small portion of gold’s price action.
Yet over long periods gold has preserved and grown purchasing power. Since the early 1970s, gold has compounded at roughly 8% annually while CPI averaged near 4%, yielding a sustained real return across decades. That long-term outperformance reflects gold’s role as a hedge against the kinds of monetary and fiscal breakdowns that erode currency value: negative real interest rates, fiscal expansion, monetary debasement, and loss of confidence in sovereign balance sheets. When those conditions appear, gold commonly outperforms government-issued inflation hedges.
Conversely, when real yields are high and monetary policy is credible and effective, gold can underperform for long stretches. The 1980–2000 period is a case in point: higher real yields and credible disinflationary policy left gold trailing in real terms for many years.
When Do TIPS Outperform Gold, and When Does Gold Outperform TIPS?
In short: TIPS tend to outperform when real yields are positive and monetary policy is functioning as intended. Gold tends to outperform when policy is constrained, inflation becomes entrenched, or sovereign balance sheets and monetary credibility are under pressure. Empirical research shows TIPS are among the most consistent short-term hedges in conventional inflation episodes, while gold’s relative strength appears in severe, structural scenarios that are harder to model.
Does the US Fiscal Situation Change the Calculation for TIPS vs. Gold?
This question is central but rarely addressed directly. Current fiscal dynamics increase the probability of scenarios in which gold’s unique features matter. Rising interest costs and large deficits do not mean TIPS will fail; the U.S. has not defaulted on Treasuries. Still, the same government that issues TIPS is running the fiscal policies that can create long-run inflationary pressure. That interdependence is the core reason some investors treat gold and TIPS as complementary rather than interchangeable.
Another practical consideration is that gold held physically in allocated storage cannot be frozen or controlled through sanctions in the way foreign exchange reserves or some sovereign assets can be. That geopolitical dimension has contributed to large central bank purchases of gold in recent years, as many national reserve managers seek assets free of counterparty or access risks.
Should Investors Hold Gold, TIPS, or Both?
The honest answer is: it depends on what you’re hedging.
TIPS are appropriate if your priority is a predictable, inflation-adjusted income stream and you are comfortable with U.S. government credit risk; they work best when held to maturity rather than through funds that expose you to duration-driven price swings.
Gold is appropriate if you are primarily concerned about systemic financial risk, monetary policy failure, or the possibility of structural currency debasement. Gold is a zero‑counterparty asset, and it can protect against scenarios TIPS cannot.
Holding both makes sense for many investors. They hedge different failure modes: TIPS for predictable, measured inflation; gold for structural, systemic, or geopolitical risks. Given contemporary fiscal and geopolitical uncertainties, a combined allocation to both, sized according to your risk tolerance and time horizon, often provides a more robust hedge than choosing one or the other exclusively.
Stay On Top of Gold & Silver Prices
Get market alerts delivered to your inbox.
Real-time tickers and subscription forms removed for security and privacy. Visit the publisher’s site for alerts and subscription options.
People Also Ask
Are TIPS or gold a better inflation hedge?
It depends on the inflation scenario. TIPS perform more consistently in moderate, predictable inflation because they mechanically track CPI and lock in a real return. Gold performs better in severe, entrenched inflation or when monetary policy and sovereign balance sheets lose credibility. For most investors, a mix of both provides complementary protection.
What is the main difference between TIPS and gold?
TIPS provide a guaranteed real return above the official CPI and depend on the U.S. government’s promise. Gold provides no yield and no guarantee, but it requires no counterparty. That fundamental contrast — guaranteed real return versus independence from any issuer — explains when each asset is most useful.
Did TIPS protect investors during the 2022 inflation spike?
Partially. Investors who held individual TIPS to maturity received the inflation-adjusted principal. However, holders of TIPS funds experienced notable losses as rising yields pushed bond prices down. The episode highlights that TIPS held to maturity behave very differently from TIPS accessed through pooled funds.
Why do central banks buy gold instead of just holding TIPS?
Central banks accumulate gold because it carries no counterparty risk and cannot be frozen or sanctioned in the same way as some foreign exchange reserves or sovereign assets. Recent central bank buying reflects a desire to diversify reserves away from assets that depend on other states’ access or goodwill.
Does the US national debt make TIPS riskier?
Not in the conventional sense of imminent default — the U.S. has not defaulted on Treasuries. But rising deficits and growing interest costs increase the probability of long-term inflationary pressures. Because TIPS are issued by the same entity driving fiscal outcomes, their protective value can be affected if that entity’s policies undermine monetary credibility. Gold, by contrast, does not have that circular dependence.
How much of my portfolio should be in gold vs. TIPS?
Institutional frameworks often allocate 5–15% of a portfolio to inflation-sensitive real assets. The split between gold and TIPS within that bucket depends on your goals: prioritize TIPS for predictable, income-producing inflation protection; prioritize gold for hedge against systemic, long-term purchasing-power risk. Many investors find a balanced allocation to both is the most practical response to diverse risks.
SOURCES
1. Federal Reserve / FRED — 10‑Year TIPS Yield (DFII10).
2. iShares / BlackRock — iShares TIPS Bond ETF (TIP).
3. Congressional Budget Office — Budget and Economic Outlook 2026–2036.
4. Peter G. Peterson Foundation — Interest costs on the national debt.
5. Moody’s Ratings — U.S. sovereign rating actions (May 2025).
6. World Gold Council — research on gold and CPI (“Beyond CPI”).
7. World Gold Council / LBMA — long-term gold return research (GLTER).
8. Federal Reserve Bank of St. Louis / FRED — Consumer Price Index (CPI‑U).
9. News reporting on frozen foreign exchange reserves in 2022 (Russia example).
10. World Gold Council — gold demand trends and central bank purchases (2022–2025).
Disclaimer: This article is informational only and does not constitute financial or investment advice. Consult a qualified financial adviser before making investment decisions.
You May Also Like:
- Gold Prices and Real Interest Rates: What Every Investor Must Know
- Gold Down 26%. Barclays’ $4,791 Target Never Moved.
- Gold‑Silver Ratio at 64: What It Signals for Silver in 2026
- How Central Banks Decide How Much Gold to Hold
- How Much Does Gold Storage Cost? The $72‑a‑Year Answer
- Silver Price Outlook June 2026: The Correction Was the Setup
- Wall Street’s $6,000 Gold Call: Data Most Investors Don’t See
- Silver Eagle vs. Maple Leaf vs. Britannia: Which Gives You More Silver?
- Gold Price Outlook June 2026: What CPI and the Fed Mean
Popular Topics
Picked from the archive
-
01
 Topics
Trump $2,000 Stimulus Checks, Auto Loan Crisis and Silver Rally
-
02
Topics
Silver Rises 3% to $88 as Markets Shrug Off Risk
-
03
Topics
Warsh Inflation Measure: What It Means for Gold Prices
-
04
Topics
After January Jobs Surprise, Silver Dips as Gold Holds Firm
-
05
Topics
IMF: Treasuries Are No Longer Safe, Gold Reacted First
-
06
Topics
AI Bubble Fears Surge as Gold Price Falls Below 4,000 USD
-
07
Topics
How to Check If Your Gold Storage Is Allocated
-
08
Topics
How Stagflation Sparks Both Drivers of Silver