Should You Still Hold Gold in Your Portfolio?
Yes. The 60/40 portfolio no longer provides the diversification it once did. Central banks purchased 863 tonnes of gold in 2025 — nearly double their pre-2022 pace — and the fiscal backdrop continues to erode the purchasing power of fiat currency. The case for a 5–15% allocation to gold remains valid; indeed, the conditions that built that case have become more acute.
Gold traded near $4,720 per ounce in April 2026 — roughly 16% below its all-time high of $5,589 set on January 28, yet still up approximately 42% year-over-year. Investors who watched gold more than double in under two years may wonder if the strategic case for holding gold has run its course. It has not. The fundamental reasons to own gold have not changed; in many respects they have strengthened.
What Makes an Asset “Strategic”?
A strategic asset is held for structural reasons, not tactical timing. It earns a place in a portfolio not because of next quarter’s potential, but because of what it reliably does across cycles: reduce risk, protect purchasing power, and perform when other assets decline simultaneously.
Gold meets those criteria. It carries no counterparty risk, its supply cannot be expanded by government decree, and over long periods it has delivered competitive returns driven by a different set of forces than equities. That independence from financial-system risk is what separates strategic holdings from short-term trades.
Your Gold Buying Guide Many investors overpay when buying gold — and again when selling. This guide explains what to own and why, with clear steps for building a long-term allocation.
Request the guide from your trusted provider or consult a qualified advisor to discuss how a strategic gold allocation fits your goals.
Has the 60/40 Portfolio Stopped Working?
For decades the 60/40 mix worked because stocks and bonds often moved in opposite directions during market stress: equities declined while bonds rallied. That relationship has weakened. When core inflation runs above roughly 2.5%, the negative correlation between U.S. equities and U.S. Treasuries can deteriorate, allowing both to fall together in the same inflationary shock — the environment investors have navigated since 2022.
Gold behaves differently. Over the past 20 years, the LBMA gold price has shown a low correlation with global equities, and during crisis episodes the relationship often turns negative. Adding a modest gold allocation can reduce overall portfolio risk materially while contributing only a small share of total portfolio volatility — offering meaningful protection at minimal long-term cost.
What Are Central Banks Telling Us About Gold?
Watch what the largest institutional investors do rather than what they say. In 2025, central banks purchased 863 tonnes of gold — nearly double the pre-2022 annual average of 473 tonnes and one of the largest annual increases on record. Several national banks materially expanded holdings; for example, one central bank added over 100 tonnes, bringing its holdings to roughly 28% of official reserves. Most central banks surveyed expected reserve increases to continue.
Late in 2025, gold overtook U.S. Treasuries to become the world’s largest reserve asset by value — a milestone not seen since the mid-1990s. Central banks accumulate over decades, not months, and their recent buying at historically elevated levels represents a structural shift in how sovereign institutions manage reserve risk. That activity is powerful external validation of gold’s strategic role.
Is Gold Really Just an Inflation Hedge?
Gold is often labeled an “inflation hedge,” then criticized when it does not track monthly CPI readings. That misses the point. Gold’s principal role is to protect against monetary debasement and long-term purchasing-power erosion, not to mirror month-to-month inflation statistics.
When governments run persistent deficits and central banks expand balance sheets, fiat currency tends to lose buying power over time. Gold’s supply grows at roughly 1–2% per year regardless of monetary policy, and no government can create more of it by decree. Concerns about fiscal deficits, rising sovereign debt, and the long-term credibility of monetary policy have driven institutional demand and helped form what some analysts call a “debasement trade.”
Several major research desks have published elevated year-end price targets for gold, reflecting the view that long-term structural pressures support higher levels. When large, cautious institutions reach similar conclusions, it merits attention from investors considering strategic allocations.
How Much Gold Should You Hold?
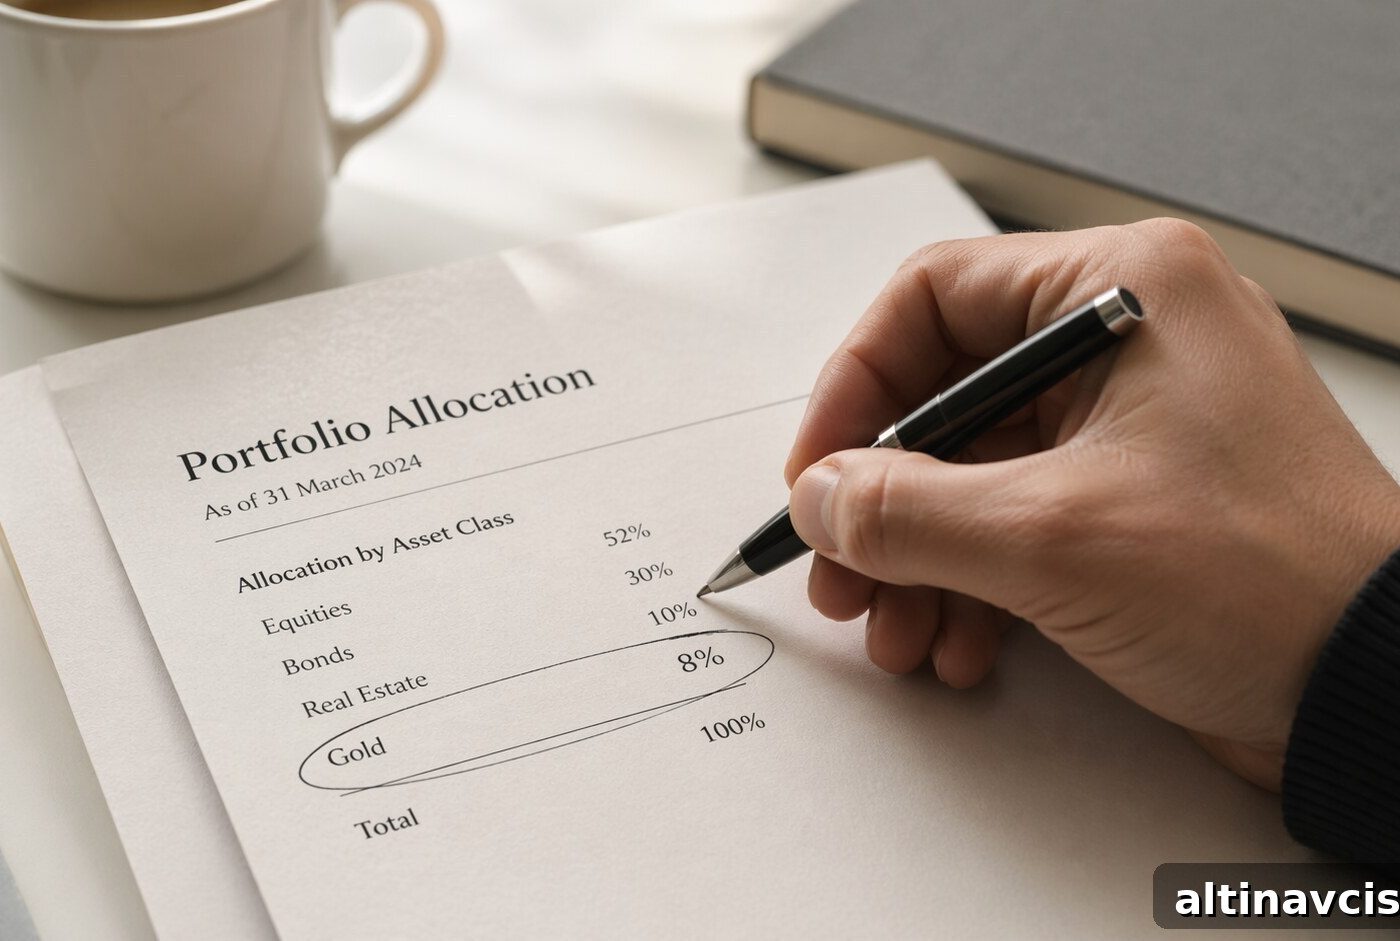
Most institutional frameworks recommend allocating 5–15% of a portfolio to gold, with the exact percentage determined by risk tolerance, time horizon, and investment goals. Historically, that range has improved risk-adjusted returns and reduced maximum drawdowns during stressed markets.
Conservative, wealth-preservation-focused investors tend toward the higher end of the range, while balanced portfolios more commonly hold 5–8%. The precise allocation matters less than the discipline of maintaining a strategic weight and rebalancing periodically rather than attempting to time price moves.
On the physical versus ETF question: physical gold eliminates counterparty risk and provides direct ownership, making it an anchor for investors concerned about systemic risk. Gold ETFs offer liquidity and low storage friction, useful for tactical adjustments. Many long-term investors combine both approaches to balance security and convenience.
Stay On Top of Gold & Silver Prices
Get timely market alerts and analysis delivered to your inbox.
Subscribe to updates or consult your advisor for personalized guidance.
People Also Ask
Is gold still a good investment in 2026?
Yes, by many institutional measures. Gold was up roughly 42% year-over-year in early 2026 and remained supported by central bank buying, fiscal deficits, and weakening stock-bond diversification. Major research desks published elevated targets for year-end pricing, and the structural drivers of the bull market remained in place.
Why do financial advisors recommend gold for portfolios?
Gold shows a very low long-term correlation with equities, meaning it often holds value or rises when other assets fall. That diversification outcome is difficult to replicate simply by adding more stocks or bonds, which is why advisors include a strategic allocation to precious metals in many portfolios.
How much gold should I have in my portfolio?
Institutional guidance commonly recommends 5–15%, based on risk tolerance and objectives. Conservative investors often target the higher end; balanced portfolios commonly hold 5–8%. Consistency and periodic rebalancing are generally more important than precise timing.
Is gold a hedge against inflation?
Not in the narrow sense of tracking monthly CPI readings. Gold functions more as a hedge against long-term monetary debasement and purchasing-power erosion. Over multi-year periods of fiscal excess and monetary expansion, gold has historically preserved purchasing power more reliably than fiat currency.
Does gold perform well during a stock market crash?
Historically, gold has often outperformed during severe equity drawdowns. During the 2008 financial crisis, for example, gold rose while equities fell sharply. Analysis of several large equity drawdowns shows gold tending to gain on average, highlighting its value as crisis-era diversification.
Gold’s Strategic Case: Three Pillars
Three conditions define gold’s strategic case in 2026:
- The traditional stock-bond diversification relationship has weakened, reducing the effectiveness of a pure 60/40 mix.
- Central banks are accumulating gold at historically elevated levels, signaling a structural shift in reserve management.
- The fiscal and monetary backdrop continues to put pressure on the purchasing power of fiat currency.
A 5–15% allocation to gold, held consistently and rebalanced periodically, has historically improved portfolio outcomes across cycles without requiring precise market timing.
SOURCES
1. Trading Economics — Gold Price.
2. CBS News — Highest gold price in history overview.
3. J.P. Morgan Private Bank — analysis of gold’s strategic role.
4. World Gold Council — Gold Demand Trends Full Year 2025: Central Banks.
5. World Gold Council — Gold Demand Trends Full Year 2025.
6. World Gold Council — Gold’s optimal portfolio weight in higher-correlated environments.
7. World Gold Council — Commentary on gold’s appeal amid rising volatility.
8. Morningstar — analysis of gold’s evolving behavior relative to equities.
9. The Wealth Advisor — coverage of major research updates to gold outlooks.
10. Mining.com — reporting on gold’s status in global reserves.
11. World Gold Council — market commentary for December 2025.
12. GoldSilver.com — market notes and analysis referenced in commentary.
13. GoldSilver.com — article on diversification benefits of gold and silver.
14. GoldSilver.com — coverage of central bank buying trends.
15. GoldSilver.com — portfolio allocation guidance and forecasts.
Disclaimer: This article is for informational and educational purposes only. It does not constitute investment advice. Consult a qualified financial adviser before making investment decisions.
You may also like:
- Best gold investment in 2026: bars, coins, IRA or ETF?
- What happens to gold when the dollar crashes?
- Gold Fell During a War. So Is It Really a Safe Haven?
- Is Gold at Fair Value? What three models say — and where they disagree
- Silver Price Predictions for the Next 5 Years: Data-Backed Scenarios
- Tariff Refunds, Dollar Weakness, the AI Bust: Gold’s Case
- How to Buy Gold for Beginners: Step-by-Step Guide (2026)
- Silver Price Forecast 2026-2027: The bull case and bear case laid out
Popular Topics
Picked from the archive
-
01
 Topics
Inside the Fed’s Most Contentious Jackson Hole Meeting
-
02
Topics
Why Americans Are Missing Out on Gold’s 60% Rally
-
03
Topics
Wall Street Whiplash: Stocks Rally on CPI, Plunge on PPI Shock
-
04
Topics
US Jobless Claims Jump to 3-Month High, Point to Labor Softening
-
05
Topics
What’s Moving Gold and Silver Prices This Week
-
06
Topics
What’s Driving Gold Demand from Washington, D.C. to Mumbai
-
07
Topics
Gold Price Tops $3,600 After $1,000 Rally This Year
-
08
Topics
Gold Price Drops Below $5K After Jobs Revisions Roil Markets