Gold vs Stocks and Bonds: Investment Data Explained
Gold vs Stocks & Bonds — The Quick Answer
- Stocks: Growth potential, but vulnerable to sharp drawdowns.
- Bonds: Income and historically diversifying, but their defensive power has weakened.
- Gold: Stability, crisis protection, and genuine diversification when other assets move together.
Most portfolios are built on a simple assumption: stocks grow and bonds protect. That worked for decades, but recent data shows the relationship has shifted. The classic 60/40 allocation depends on stocks and bonds moving in opposite directions. When that negative correlation breaks down, the portfolio has a vulnerability — and gold is the asset that fills that gap.
This article explains how gold differs from stocks and bonds, what the historical record shows, and how a modest allocation to gold can improve portfolio resilience without abandoning equities or fixed income.
Gold vs Stocks and Bonds — What the Data Shows
The 60/40 portfolio relied on the idea that bonds rise when stocks fall. That negative correlation powered diversification for decades. Today, however, that engine is stalling. A cross-asset analysis by the World Gold Council in early 2026 documented an important shift: stocks and bonds are increasingly moving together, not in opposite directions. The 2022 inflation shock made this reality impossible to ignore — stocks fell sharply and bonds fell too, producing one of the worst years for a 60/40 portfolio in modern history.
The issue is structural, not merely cyclical. With inflation remaining sticky and central banks constrained in how quickly and how far they can cut rates, the usual mechanism that lifts bond prices during stock market stress — rapid rate cuts — may not be available. That reduces bonds’ ability to act as a shock absorber just when investors need it most. Gold, by contrast, has historically behaved differently in these environments.
Gold Has Outperformed Every Major Asset Class
Does Gold Actually Protect You When Markets Crash?
Gold and stocks serve different roles in a portfolio, and the data shows those roles clearly. From 2014–2023, gold posted positive annual returns in seven of those ten years. Crucially, gold’s largest gains often occurred during periods of market stress: in 2020 it rose more than 25% as global markets responded to pandemic uncertainty, and during the 2008 financial crisis it produced positive returns while the S&P 500 fell nearly 40%.
Research on crisis performance, summarized by the World Gold Council, shows that across a range of major shocks — from the dot-com collapse and 9/11 to the COVID-19 pandemic and more recent market shocks — gold consistently gained or meaningfully cushioned portfolio losses when equities were deeply negative.
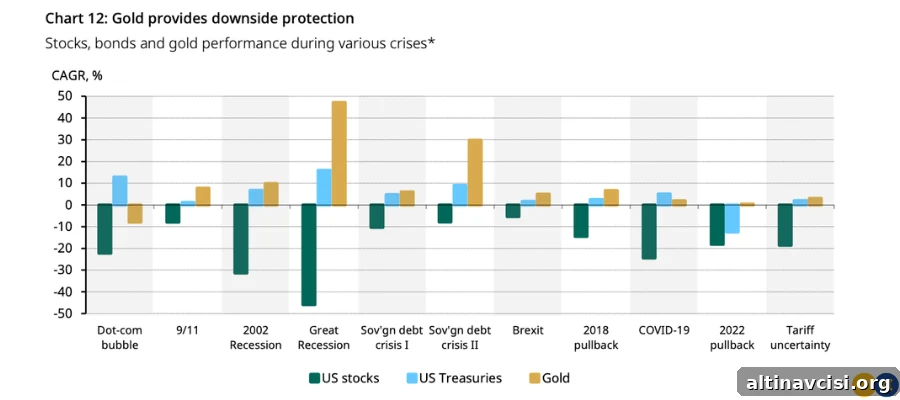
Source: World Gold Council, Why Gold 2026: Cross-Asset Perspective
Gold’s purpose in a portfolio is not to outperform stocks in a bull market; it’s to behave differently when other assets are falling. Stocks move based on earnings, growth, and sentiment. Gold reacts to inflation expectations, real interest rates, and demand for safety. Those different drivers are why gold provides true diversification.
Are Bonds Still a Better Safe Haven Than Gold?
For many years, long-duration Treasuries were the default hedge for equities: investors fled to bonds, yields fell, and prices rose, cushioning portfolios. That dynamic has weakened. When inflation rises and central banks tighten policy, both stocks and bonds can fall together. Gold does not follow the same pattern and has often acted as a buffer when Treasuries did not.
A clear example came in 2022, when aggressive rate hikes sent both stocks and Treasuries lower. Gold finished that year essentially flat, a result that preserved capital relative to many other assets. Gold tends to perform better when real interest rates are low or negative because the opportunity cost of holding a non-yielding asset is smaller — a condition that has prevailed intermittently in recent years.
The Financial System Isn’t Safer — And You Know It
As risks mount, gold and silver remain positioned to preserve value and provide crisis protection.
If you’re reviewing where to allocate risk, consider how precious metals behave when inflation expectations and market stress increase.
Does Gold Actually Hedge Against Inflation?
Short answer: yes, but not as a precise month-to-month CPI hedge. Over centuries gold has preserved purchasing power in ways fiat currencies have not because its supply cannot be increased by central banks. Over shorter horizons, gold reacts more to inflation expectations and confidence in monetary policy than to immediate CPI prints. When public confidence in policy weakens and real interest rates fall, gold tends to benefit — and recent surveys show household inflation expectations have risen even as official forecasts remain more optimistic.
Why Do Most Investors Own So Little Gold?
The data supporting a strategic role for gold is widely available, so the short answer to why most investors remain underweight is behavioral. Recency bias favors assets that have recently outperformed — equities have led for much of the past decade — and investors naturally overweight what has worked. Income bias also plays a role: gold pays no dividend or coupon, so investors focused on income may dismiss it. Institutional inertia keeps the 60/40 framework in place even as its assumptions change.
The result is portfolios optimized for a world of falling rates, low inflation, and reliable bond protection — a world that may no longer exist. Gold historically delivers its greatest value in the very environment many portfolios aren’t positioned for today.
What Percentage of a Portfolio Should Be Gold?
Research from the World Gold Council indicates an optimal allocation range of roughly 5–8% for many investors. Within this band, gold has historically improved risk-adjusted returns by reducing portfolio drawdowns while not materially sacrificing long-term gains. Conservative investors focused on capital preservation may gravitate to the higher end, while growth-oriented investors can still benefit from a modest allocation — even 5% can improve the Sharpe ratio of an equity-heavy portfolio.
Despite this evidence, most private portfolios remain well below this suggested range, creating a structural gap in resilience for many investors.
Is the Stock Market Overdue for a Correction — And What Happens to Gold If It Does?
Several conditions that historically precede market dislocations are present: elevated equity valuations by forward P/E measures, increased margin debt levels, and compressed credit spreads that imply low tolerance for surprises. When risk is concentrated and complacency is high, repricing can be fast and severe. In such scenarios, safe-haven demand tends to rise, and gold typically benefits as investors seek protection from multiple forms of market risk.
Gold is not a speculative bet on a crash; it is a hedge against risks embedded in current market pricing that many portfolios are not built to absorb.
So, Should You Add Gold to Your Portfolio?
The evidence supports adding gold as a complementary asset, not as a replacement for stocks or bonds. Gold preserves capital during crises, offers structural protection against inflation over long periods, and provides diversification that bonds may no longer reliably deliver. A modest allocation — often in the 5–8% range — has historically improved portfolio resilience without materially reducing long-term returns.
The 60/40 approach remains a useful starting point, but relying on it exclusively comes with a different kind of risk in today’s environment. Adding gold completes the picture and can reduce vulnerability to the new cross-asset dynamics investors face.
Stay On Top of Gold & Silver Prices
Receive market alerts and updates to help you track precious metals trends.
People Also Ask
Does gold outperform stocks over the long term?
Not consistently, and that’s not the point. Gold tends to outperform or hold up better during crises, periods of high inflation, and episodes of severe market stress. Between 2014 and 2023, gold delivered positive returns in seven of ten years, with the largest gains occurring when equities were under pressure. Its primary value is diversification and downside protection, not matching stock returns in sustained bull markets.
Why is gold considered a hedge against inflation?
Gold has maintained purchasing power over long spans where fiat currencies have lost value due to monetary expansion. Because gold’s supply increases slowly and cannot be created by central banks, it serves as a structural buffer against currency depreciation. Over shorter periods, gold responds to inflation expectations and changes in real interest rates.
What is the correlation between gold and stocks?
Gold typically has a low or negative correlation with equities, meaning it tends to move independently from stock markets. This low correlation is the reason gold improves portfolio diversification. During major equity drawdowns like the 2008 financial crisis and the 2020 pandemic selloff, gold posted positive returns while stocks fell sharply.
How does gold compare to bonds as a portfolio hedge?
Historically, bonds rose when stocks fell, providing a hedge. That relationship has weakened as stock-bond correlations have increased. In 2022 both stocks and bonds fell together during the inflation shock, while gold finished the year near flat, preserving value comparatively. In high-inflation, low-real-rate environments, gold can provide defensive benefits that bonds may not.
How much gold should I have in my portfolio?
Research suggests an allocation in the range of about 5%–8% for many investors, depending on risk tolerance. Even a modest 5% allocation has historically improved risk-adjusted returns by reducing drawdowns without materially sacrificing long-term gains. Many portfolios currently hold far less than this recommended range.
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Consult a qualified financial advisor before making investment decisions. Past performance is not indicative of future results.
You May Also Like:
- Silver Price Crash History: What Happens After the Biggest Drops
- Gold IRA vs Physical Gold: Which Is Best for Your Portfolio?
- When Should You Sell Gold and Silver? (And What to Buy Next)
- Could the US Revalue Its Gold Reserves to Pay Down Debt?
- How Gold Performs in Recessions: What History Tells Us
- Gold vs Inflation: What 100 Years of Data Shows
Popular Topics
Picked from the archive
-
01
 Topics
Japan Election Promises and Tariff Fears Rattle Bond Market
-
02
Topics
Global Oil Prices Steady as Travel Demand Rises, Sanctions Loom
-
03
Topics
Gold Holds Above $5,000 as Hedge Funds Brace for Volatility
-
04
Topics
Why Central Banks Are Buying Gold Amid Market Turmoil
-
05
Topics
Gold Hits $4,000: Wake-Up Call for Markets and Policymakers
-
06
Topics
Oil Price Rebounds to $69 as US-EU Trade Deal Nears
-
07
Topics
Gold Prices Surge as Middle East Tensions Escalate
-
08
Topics
Rare Earth Metals Driving the Global Economy