5-Year Silver Price Forecast: Data-Driven Scenarios
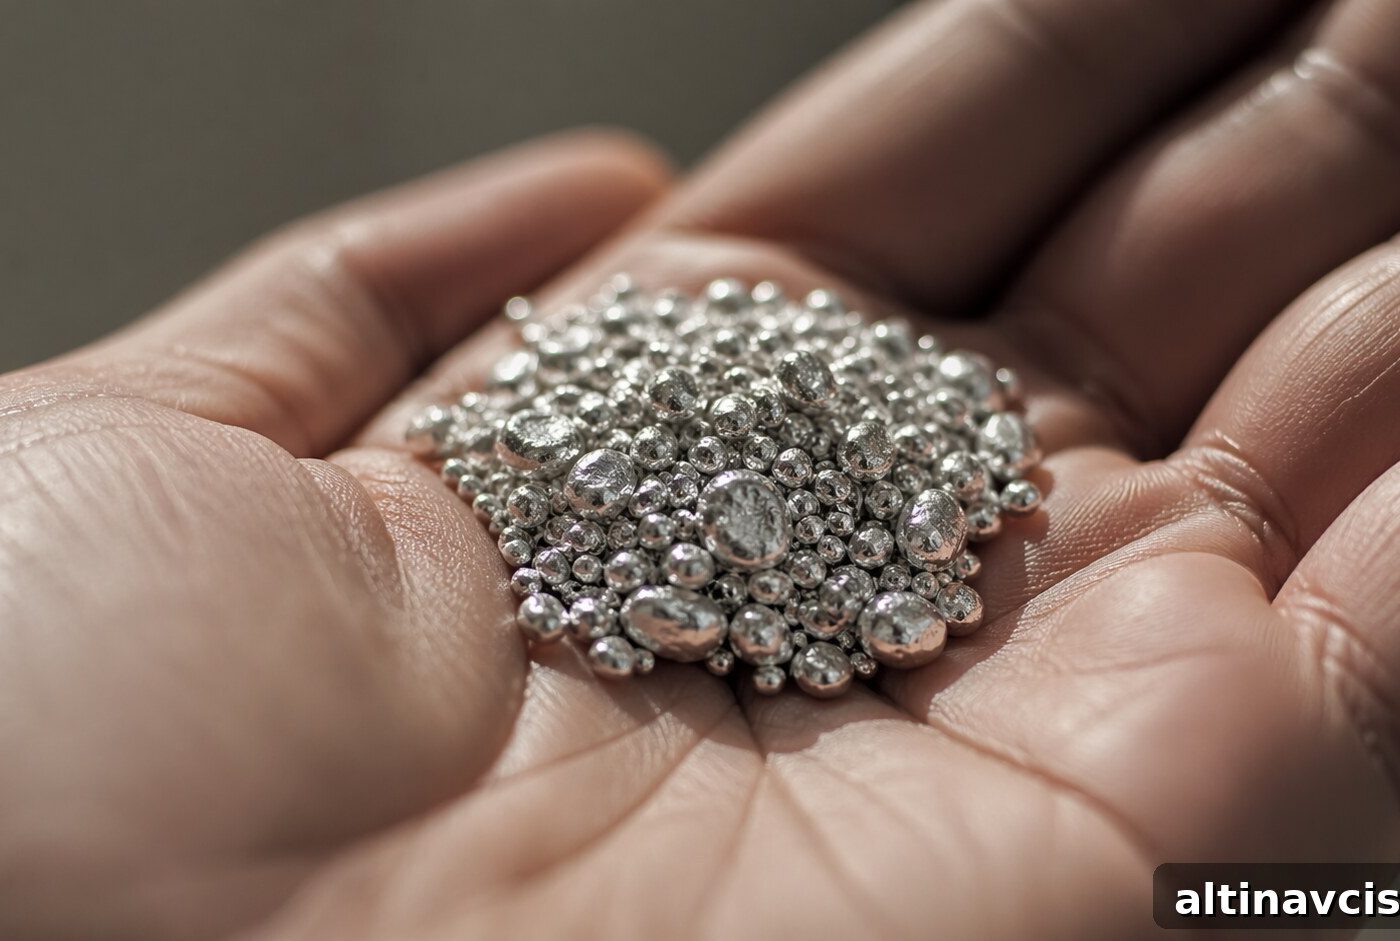
Silver currently trades around $49 per ounce after pulling back roughly 60% from its January 2026 nominal high of $121.64. Over the next five years, a realistic range is roughly $45–$200+ per ounce depending on how industrial demand, supply deficits, and monetary policy evolve. The structural case—five consecutive years of supply shortfalls (2021–2025), a projected sixth for 2026, rising solar and EV demand, and potential dollar weakness—remains intact. Historically, corrections during established bull markets are often accumulation windows rather than exits.
Price data and supply deficit figures last verified October 2026.
Silver reached a nominal all-time high of $121.64 on January 29, 2026 — the highest nominal price on record — before retreating to around $66.75 per ounce at its initial correction. That decline prompts a core question: where does silver go from here?
Any credible five-year silver forecast must be built on three pillars: the cumulative supply deficit, the industrial demand pipeline, and the direction of monetary conditions. Below, those forces are mapped into bear, base, and bull scenarios, with clear variables to watch.
What’s actually driving silver’s price over the next five years?
Few commodities share silver’s dual demand profile. Its price is shaped by both industrial consumption and investment/monetary demand — and currently both drivers are active.
On the industrial side, silver’s electrical conductivity and performance in thin-film and photovoltaic applications make it hard to substitute at scale. Silver is important in solar PV cells, EV electrical systems, 5G equipment, and data center infrastructure. Industrial demand reached 680.5 million ounces in 2024, a fourth consecutive annual record.
Industrial demand moderated to an estimated 665 million ounces in 2025 as some solar manufacturers reduced silver per cell. Industry analysts described that as a temporary adjustment rather than a structural reversal. At the same time, forecasts for solar and EV deployment through the end of the decade point to continued expansion in industrial silver use.
On the monetary side, silver tends to rise when real interest rates fall, the U.S. dollar weakens, and investors seek non-financial-system stores of value. Today, those monetary forces coexist with industrial tailwinds — a key difference from prior rallies that were driven mainly by monetary factors alone.
Your Gold Buying Guide Most investors overpay when they buy gold and again when they sell. This guide explains what to own and why.
Why the supply deficit is the most important number in these silver price predictions
The single most important metric for long-term silver outlooks is the cumulative supply deficit, not a near-term price target.
Silver ran structural deficits for five consecutive years from 2021 through 2025, with a sixth projected for 2026. The 2025 shortfall was estimated at about 95 million ounces. Some institutions revised near-term deficit estimates downward in 2026, citing lower photovoltaic silver intensity, but a narrower short-term deficit does not remove the multi-year gap. Over the five-year window from 2021–2025 the cumulative shortfall reached approximately 820 million ounces — roughly one year of global mine output.
Supply cannot close that gap quickly. Global mine production has been relatively flat at roughly 813 million ounces annually and ore grades are declining. About 70% of silver is recovered as a byproduct of gold, copper, and zinc production, so silver supply is less responsive to price signals than that of primary metals. New primary silver projects are limited, so sizable production growth faces long lead times.
Demand, meanwhile, continues to expand. Industry studies project that solar, EV, and data center applications will materially increase industrial silver consumption through 2031. For example, large-scale solar capacity commitments and accelerating EV adoption imply sustained incremental demand, and EVs use substantially more silver per vehicle than conventional cars.
Deficits of this magnitude deplete inventories, and rebuilding above-ground stocks can take years. That persistent deficit acts as a structural floor under the market.
What are the three price scenarios for the next five years?
The supply and demand backdrop sets the stage. What happens next depends on whether macro and industrial trends worsen, stabilize, or accelerate. Below are the bear, base, and bull scenarios and the key conditions that would drive each.
Bear case — $45–$75 per ounce
This is the downside the market is already testing. A combination of stronger dollar, higher real yields, and faster-than-expected industrial thrift (less silver per solar cell or substitution in some applications) pushed prices lower. A move toward $45 is possible if the dollar strengthens further and industrial demand disappoints. Even so, current levels still reflect the remaining structural deficit; a deeper rout to pre-2024 lows is unlikely without a material reversal of the deficit and demand trends.
Base case — $100–$140 per ounce
The base case assumes moderate industrial growth, persistent annual deficits in the 50–100 million ounce range, and a gradual return of easing monetary conditions that weakens the dollar. Under that path, institutional forecasts clustered around the $85–$100 range translate into a multi-year move toward $100–$140 as deficits compound and inventories stay tight. A reversion of the gold-silver ratio toward long-run averages would also mechanically lift implied silver prices if gold continues higher.
Bull case — $150–$200+ per ounce
The bull case requires existing trends to compound: accelerating solar and EV demand, further inventory tightening, and a return of investment inflows. If the gold-silver ratio compresses toward late-stage bull market norms and gold experiences a major revaluation, silver could exceed $150–$200 per ounce. Extreme analyst scenarios that model far higher prices assume very large moves in gold and significant ratio compression; such outcomes are possible but are outliers relative to consensus forecasts.
What are major banks forecasting?
Institutional forecasts that would have seemed aggressive two years ago are now part of the mainstream debate. Several major banks project average silver prices in the roughly $80–$100 range during the near term, citing continued industrial demand tied to the energy transition and limited near-term supply elasticity. Independent industry research also projects expanding demand from solar, EVs, and data centers through the five-year horizon.
Is this a good time to buy silver?
After a steep pullback, the structural case for silver remains in place; only the near-term price has repriced. The gold-silver ratio sits well above its long-run average, indicating silver is cheaper relative to gold than it has been historically. Corrections of 30–35% occurred multiple times during prior bull phases, yet larger gains followed when structural drivers persisted. If the long-term deficit and industrial demand fundamentals continue, today’s lower prices can represent a more attractive entry point for investors who view silver as a strategic industrial and monetary exposure.
Stay on top of gold & silver prices
Receive market alerts and updates delivered to your inbox.
People also ask
Will silver prices go down?
Silver has already declined from its January 2026 peak as monetary expectations shifted and real yields stayed elevated. Near-term downside to the mid-$40s is possible if the dollar strengthens and industrial demand slows. However, the multi-year supply deficits and structural industrial drivers remain unchanged, supporting medium- and longer-term upside potential.
What is a realistic silver price prediction for 2030?
The consensus base case points to roughly $100–$140 per ounce by 2030, assuming persistent deficits and moderate industrial growth. The bull case, under accelerated green-energy deployment and renewed investment inflows, could push silver toward $200 or higher.
Why has silver pulled back from its all-time high?
Silver’s pullback reflects a mix of factors: a shift in Fed rate-cut expectations, elevated real yields, profit-taking after a large 2025 gain, and downward revisions to near-term photovoltaic demand by some research teams. These near-term dynamics changed price momentum, but they did not remove the structural supply-demand imbalance.
Will silver ever reach $200 per ounce?
$200 per ounce lies within the bull-case scenario if deficits compound, gold continues a structural revaluation, and the gold-silver ratio compresses toward historical bull-market norms. It is not consensus, but given the underlying deficit and industrial demand trends, it is a plausible outcome under the right conditions.
How does the gold-silver ratio affect silver price predictions?
The gold-silver ratio (gold price divided by silver price) currently sits well above its long-run average. If gold rises toward multi-thousand-dollar targets and the ratio simply reverts to its historical average, silver would trade substantially higher than today. Greater compression of the ratio toward late-stage bull-market levels would imply even larger silver gains.
Is the silver supply deficit real, and does it affect price?
Yes. Independent industry surveys report consecutive annual deficits through 2025, with the five-year cumulative gap reaching roughly 820 million ounces. Sustained deficits reduce above-ground inventories and limit the market’s ability to absorb spikes in demand, exerting upward pressure on prices over time.
Where silver goes from here
Silver’s trajectory over the next five years depends on whether structural supply constraints widen further against growing industrial demand, and on monetary conditions that could accelerate or temper price moves. The bear case is roughly $45–$75 if headwinds persist. The base case is $100–$140 backed by institutional forecasts and persistent deficits. The bull case exceeds $150 if current trends compound and investment flows return.
Track the supply deficit, industrial demand (solar, EV, data centers), and the gold-silver ratio to understand which path is most likely. These variables matter more than point forecasts for making informed allocation decisions.
Sources
Silver Institute — World Silver Survey 2025
Silver Institute / Metals Focus — World Silver Survey 2026
Silver Institute / Oxford Economics — Silver: The Next Generation Metal, December 2025
JP Morgan Global Research — How Will Silver Prices Fare in 2026?
Macrotrends — Gold-to-Silver Ratio historical chart
This article is for informational purposes only and does not constitute investment advice. Precious metals investing involves risk, including the possible loss of principal. Price data referenced as of October 2026. Consult a qualified financial advisor before making investment decisions.
You may also like:
- How to Buy Gold for Beginners: Step-by-Step Guide (2026)
- Silver Price Forecast 2026–2027: The bull case and bear case laid out
- How to Buy Silver Bars: The Investor’s Guide
- Why Silver Falls While Gold Rises: What It Means for You
- Why Are BRICS Countries Buying So Much Gold?
- Gold Price Forecast 2026–2027: Key Predictions from Top Analysts
- Is Now a Good Time to Buy Gold? The Macro Case
- Is Gold a Better Investment Than Bitcoin Right Now?
Popular Topics
Picked from the archive
-
01
 Topics
Gold Coins vs Gold Bars: Compare Value, Liquidity and Costs
-
02
Topics
Silver Price Hits $50 as Morgan Stanley Allocates 20% to Gold
-
03
Topics
HSBC Survey: Investors Double Gold Allocations as Markets Falter
-
04
Topics
Wall Street Whiplash: Stocks Rally on CPI, Plunge on PPI Shock
-
05
Topics
Gold Price Support Shifts After Ceasefire Violation
-
06
Topics
Gold Prices Jump Past $4,000 as Fed Signals Rate Cut
-
07
Topics
Why Gold Is Outperforming Nvidia in 2025
-
08
Topics
High Earners Falling Behind on Credit Cards and Auto Loans