High Earners Falling Behind on Credit Cards and Auto Loans
Rising Financial Stress Among Upper-Income Americans: Credit Card and Auto Loan Delinquencies Grow
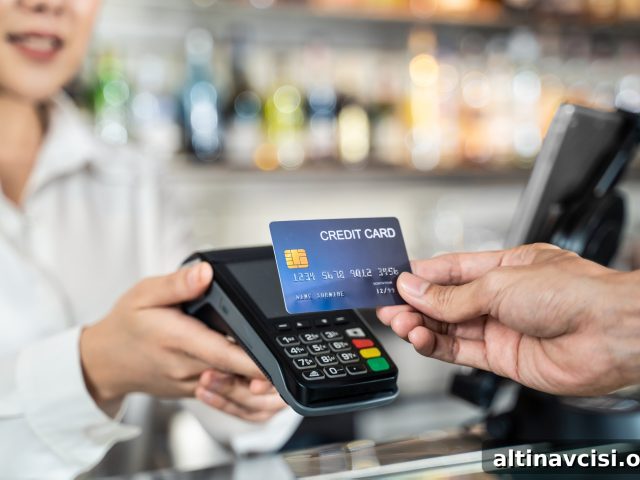
Households with incomes of $150,000 or more are increasingly falling behind on credit card and auto loan payments, a trend that signals rising financial strain among higher earners and could have broader implications for consumer-driven economic growth.
What the Data Shows
Recent observations indicate that delinquencies for households making $150,000 or more have climbed by nearly 20% over the past two years. This increase in late or missed payments on credit cards and auto loans contrasts with the common assumption that higher earners are largely insulated from short-term financial shocks. While the precise breakdown of delinquency types varies by lender and region, the overall rise points to growing vulnerability in a segment of the population long seen as a stable contributor to consumer spending.
Key Factors Driving the Rise in Delinquencies
Several interconnected factors appear to be contributing to this development:
- Higher borrowing costs: Rising interest rates increase monthly payments and the cost of carrying balances on credit cards and variable-rate loans, squeezing household cash flow.
- Slower hiring and labor market softness: A less dynamic job market can reduce income stability, making it harder for households to maintain timely debt payments.
- Rising living expenses: Persistent inflation in essentials—housing, utilities, transportation—can force households to reallocate funds away from debt repayment.
- Higher leverage and lifestyle commitments: Even among higher earners, larger mortgages, car leases, and discretionary expenditures can leave limited buffers for unexpected costs.
These factors do not affect every household equally, but together they help explain why delinquencies are increasing among a demographic that historically showed lower default rates.
Why This Matters for the Broader Economy
Upper-income households have been a significant driver of consumer demand. When higher earners tighten their spending or struggle with debt payments, the effects can ripple through the economy. Potential implications include:
- Reduced discretionary spending: Less spending on non-essential goods and services can slow growth in sectors that rely on higher-income customers.
- Increased pressure on lenders: Rising delinquencies can strain credit providers, potentially leading to tighter lending standards that make credit less accessible for other borrowers.
- Shifts in policy focus: Policymakers monitoring financial stability and consumer resilience may adjust fiscal or regulatory approaches if stress among higher-income households persists.
While a single trend does not determine macroeconomic outcomes, the increase in delinquencies among higher earners is an important signal for economists, businesses, and policymakers to watch.
Practical Steps for Households Facing Financial Strain
Households experiencing pressure on credit card or auto loan payments can take proactive steps to improve their situation. General strategies include:
- Review and prioritize debts: List all payments, interest rates, and due dates to identify high-cost balances to target first.
- Contact creditors early: Lenders often offer hardship programs, modified payment plans, or temporary forbearance when contacted before accounts become seriously delinquent.
- Explore refinancing or consolidation: Where possible, refinancing a loan or consolidating high-interest credit card balances into a lower-rate option can reduce monthly costs.
- Reassess the budget: Trim discretionary spending, redirect savings to build an emergency buffer, and consider delaying large purchases until cash flow improves.
- Seek professional guidance: Financial advisors or nonprofit credit counselors can provide tailored advice and help negotiate with creditors.
These steps are general in nature and may not fit every situation. Individuals should evaluate options based on their specific financial circumstances.
What to Watch Next
Observers will be monitoring several indicators to understand whether this trend deepens or stabilizes. Key things to watch include changes in delinquency rates across income groups, shifts in consumer spending patterns, and any adjustments in lending practices. Economic data on employment, wage growth, and interest rates will also shape how this development unfolds.
For now, the uptick in late payments among households earning $150,000 or more is a reminder that financial resilience can be fragile and that higher income alone does not eliminate exposure to economic stress.
Popular Topics
Picked from the archive
-
01
 Topics
Why Ground Beef Prices Are Soaring as Cattle Supply Shrinks
-
02
Topics
Gold Falls to One-Week Low as Trade Talks Enter Final Days
-
03
Topics
Brazil Inflation Off Target for Sixth Straight Month
-
04
Topics
Oil Price Tops $65 as US-China Trade Talks Lift Markets
-
05
Topics
June CPI Jumps 2.7 Percent as Tariffs Push Up Consumer Prices
-
06
Topics
Why Wealthy Investors Allocate 11% of Portfolios to Gold
-
07
Topics
Senate Tax Bill Adds 3.3 Trillion to Deficit, Raising Alarm
-
08
Topics
Powell’s Rate-Cut Dilemma: Trump vs Fed Credibility