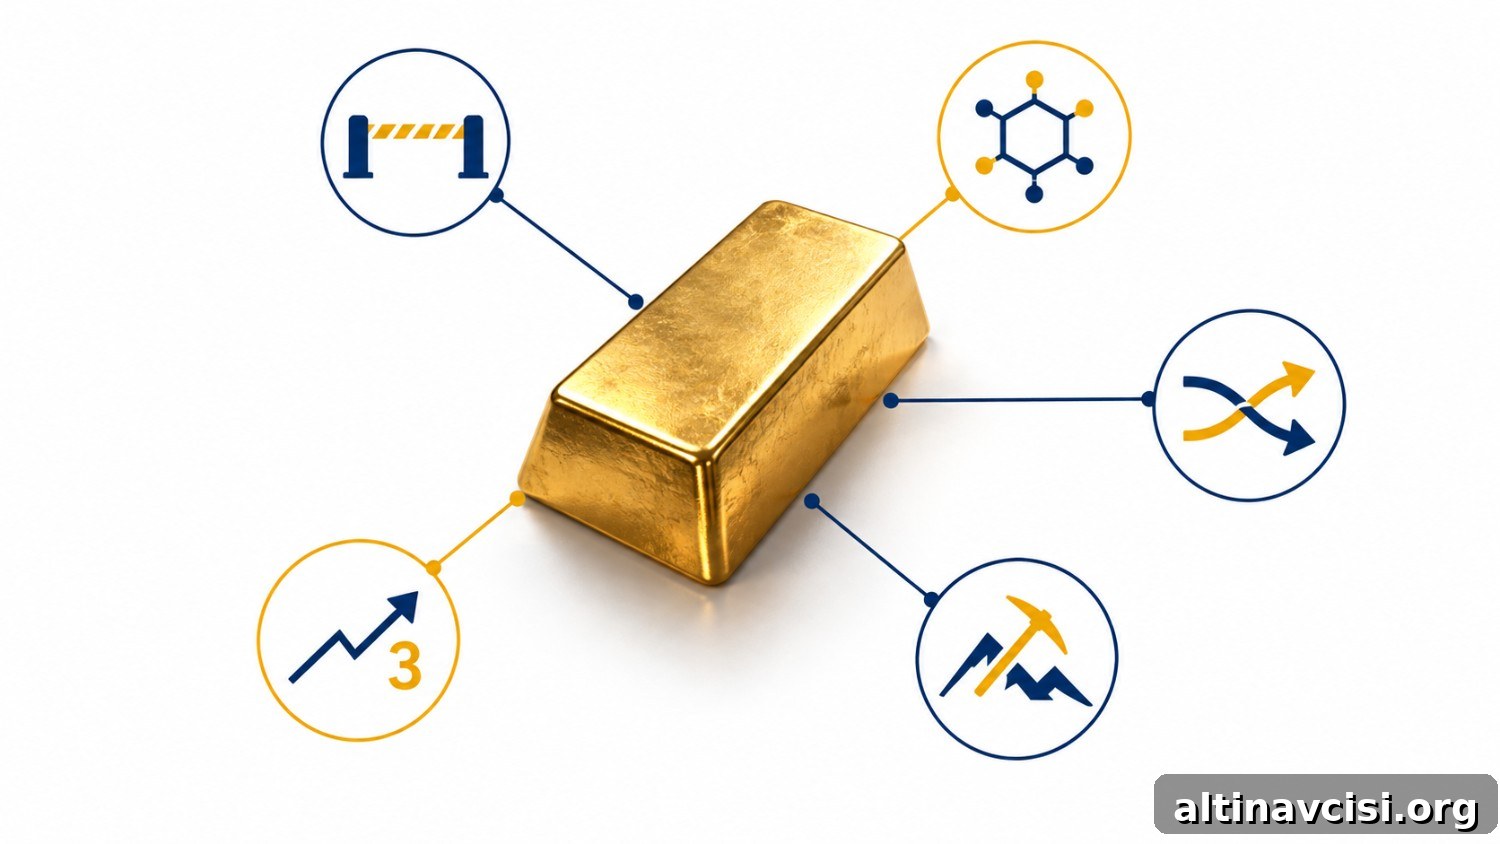
Five moves this week are about who controls gold, how it’s traded, and who will own it next — not just what the Fed does.
Gold and silver continue to react to Fed signals and dollar strength, but this week several developments affected the metal itself rather than its spot price. Five institutions made moves that change ownership, custody, trading infrastructure, or market positioning: Russia tightened controls on gold leaving the country; the UK regulator advanced a consultation on tokenized gold; a major miner expanded into metals trading; China’s largest gold producer is actively acquiring mines; and Wall Street positioning shifted behind the scenes. None of these actions shows up directly in a spot quote, yet each influences how gold flows, who holds it, and how markets will price it over time. Below is a clear look at what each development means for the gold market and investors.
Why Is Russia Cracking Down on Its Own Citizens’ Gold and Cash Exports?
Bogdan Shablya, who leads the Central Bank of Russia’s currency-control service, announced plans on September 24 to tighten limits on exports of gold and cash. Current rules cap gold-bar exports by individuals at 100 grams; larger quantities require Assay Office approval and must leave through one of four designated airports. There are also limits on ruble cash exports to Eurasian Economic Union countries, effectively capping such transfers at the equivalent of $100,000. Officials say the goal is to curb shadow-economy flows and stop gold being used as a proxy for foreign currency in illicit transfers.
That policy deserves attention because it reflects how a government can simultaneously restrict cross-border flows while changing its own reserve behavior. Russia’s central bank has reduced reserves on net this year, even as other central banks — notably the People’s Bank of China — continued to add to theirs. For example, Beijing reported a large single-month addition to its holdings in August. Restricting exports makes it harder for private holders to remove gold from a country, but it does not prevent the state from altering how much gold it holds. The distinction matters for global supply: export controls affect available private supply, while official reserve changes affect sovereign demand.
The Edge Every Investor Needs
Smarter precious metals investing starts with timely, clear market insights, global context, and practical analysis.
Could Tokenized Gold Change How You Access Bullion?
On September 22, Financial Conduct Authority chief executive Nikhil Rathi said the FCA and the Bank of England plan a joint roadmap on tokenization by year-end. The FCA is also running a Call for Input on tokenized gold, asking whether these instruments should fall under the UK’s existing fund rules or require a bespoke regulatory regime. Responses to the consultation were due by October 23. This debate is technical but consequential: it concerns wholesale market plumbing rather than retail app features.
At stake is how tokenized gold will be treated when used as collateral, traded between institutions, or offered to investors. If tokens are treated like fund shares, they would be subject to protective rules designed for pooled investment vehicles. If regulators design a regime tailored to physical commodities, tokenized gold could be governed by rules that reflect custody, provenance, and physical delivery concerns. London still clears a substantial share of global over-the-counter gold trading, so any classification chosen by the FCA will have international spillovers, influencing settlement speed, cost, and counterparty risk for global participants.
Why Is Rio Tinto Suddenly Building a Metals-Trading Desk?
Rio Tinto, the world’s second-largest miner, is expanding its trading capability to buy and sell metals it does not produce and to trade derivatives, according to reporting this week. Historically, Rio marketed primarily its own output rather than operating a broad trading book. The move follows broader industry trends: miners increasingly want direct access to price discovery and risk management tools rather than relying solely on third-party traders.
CEO Simon Trott has suggested a larger trading desk could extract more value from an existing ore body, by optimizing when and how metal is marketed. While Rio’s core metals are iron ore, copper, and aluminum — not precious metals — the shift signals a structural change in the supply chain. When producers become active traders, they can influence liquidity, hedging patterns, and term structures across metal markets. Over time, this trend may affect the desks that handle precious metals as part of broader commodity flows, changing how bullion liquidity is sourced and priced.
Why Is China’s Biggest Gold Miner Hunting for More Mines Right Now?
Shandong Gold told investors at its September 24 earnings briefing that it is actively pursuing several mergers and acquisitions, with a preference for large, producing deposits on established gold belts. The company favors immediate production over speculative exploration and evaluates political stability carefully when considering overseas assets.
Buying producing mines while gold trades near multi-year highs is a strategic decision: it assumes that proven reserves and current production streams are more valuable than the expense and uncertainty of discovery and development. This acquisition push is also a supply-side signal. If a major producer expects to expand output, it suggests the company sees room for growth in mined supply after recent rallies, which can temper long-term price upside in a way different from markets that assume miners have already captured the easy gains.
Is Wall Street’s Gold Trade Quietly Repositioning Underneath the Price?
TD Securities strategist Ryan McKay highlighted that current positioning may matter more than headline price targets. Momentum funds trimmed modest long positions ahead of a recent Fed decision, leaving room for those flows to rebuild if monetary policy expectations shift. Markets were pricing several additional rate hikes; if the Fed delivers fewer hikes than anticipated, reallocations into gold could accelerate because positioning was already cleared and ready to rebuild.
This structural room to grow is reinforced by the relatively small share of private gold holdings in global financial assets. Incrementum AG’s 2026 In Gold We Trust report estimated privately held gold at about 2.7% of all financial assets, leaving substantial capacity for additional inflows without creating an overcrowded trade. Put simply, if positioning rebuilds and flows resume, that trade can be large and fast relative to current ownership levels.
SOURCES
1. UA News — Russia plans to tighten restrictions on the export of gold and cash, September 24, 2026
2. Financial Conduct Authority — Call for Input: Tokenised Gold, Opportunities and Risks for UK Wholesale Markets, September 2026
3. Securities.io — FCA to Consult on Safeguarding Rules for Tokenised Investment Assets, September 23, 2026
4. Mining.com (via Bloomberg) — Rio Tinto to Expand Metals Trading Beyond Own Output, September 24, 2026
5. Shanghai Metals Market — Shandong Gold Prioritizes High-Quality Gold Resources in M&A Strategy, September 24, 2026
6. FXStreet — Gold: Next Leg Higher Toward $5,000, TD Securities, September 23, 2026
7. Incrementum AG — In Gold We Trust Report 2026
8. World Gold Council — Goldhub Gold Focus, September 2026
9. Caixin Global / SAFE — PBOC Gold Reserve Data, August 2026
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Past performance is not indicative of future results. Consult a qualified financial advisor before making investment decisions.
You May Also Like:
- Iran Repeated Its Hormuz Demand at the UN. The Market Already Priced It In.
- Today’s PMI Beat Cuts Gold Two Ways. Only One Side Has Been Priced In.
- Gold Fell 1.7% Today. Silver Fell 3.6%. Five Signals Point at the Dollar, Not Demand.
- Xi Lands in Washington. Gold and Silver Both Retreat, and Silver Falls Harder.
- UBS Holds Its Silver Target. The Market Already Got There First.
- China Imported 1,000+ Tonnes of Gold in Eight Months. Its Central Bank Bought Only 80.
- Fed Officials Turn Hawkish. Gold’s Iran-Diplomacy Bounce Can’t Hold.
- Bernstein Just Cut Its Gold Forecast — By Breaking Gold’s Oldest Rule to Defend It