10% of Gold Sent Abroad, 9% Brought Back Home
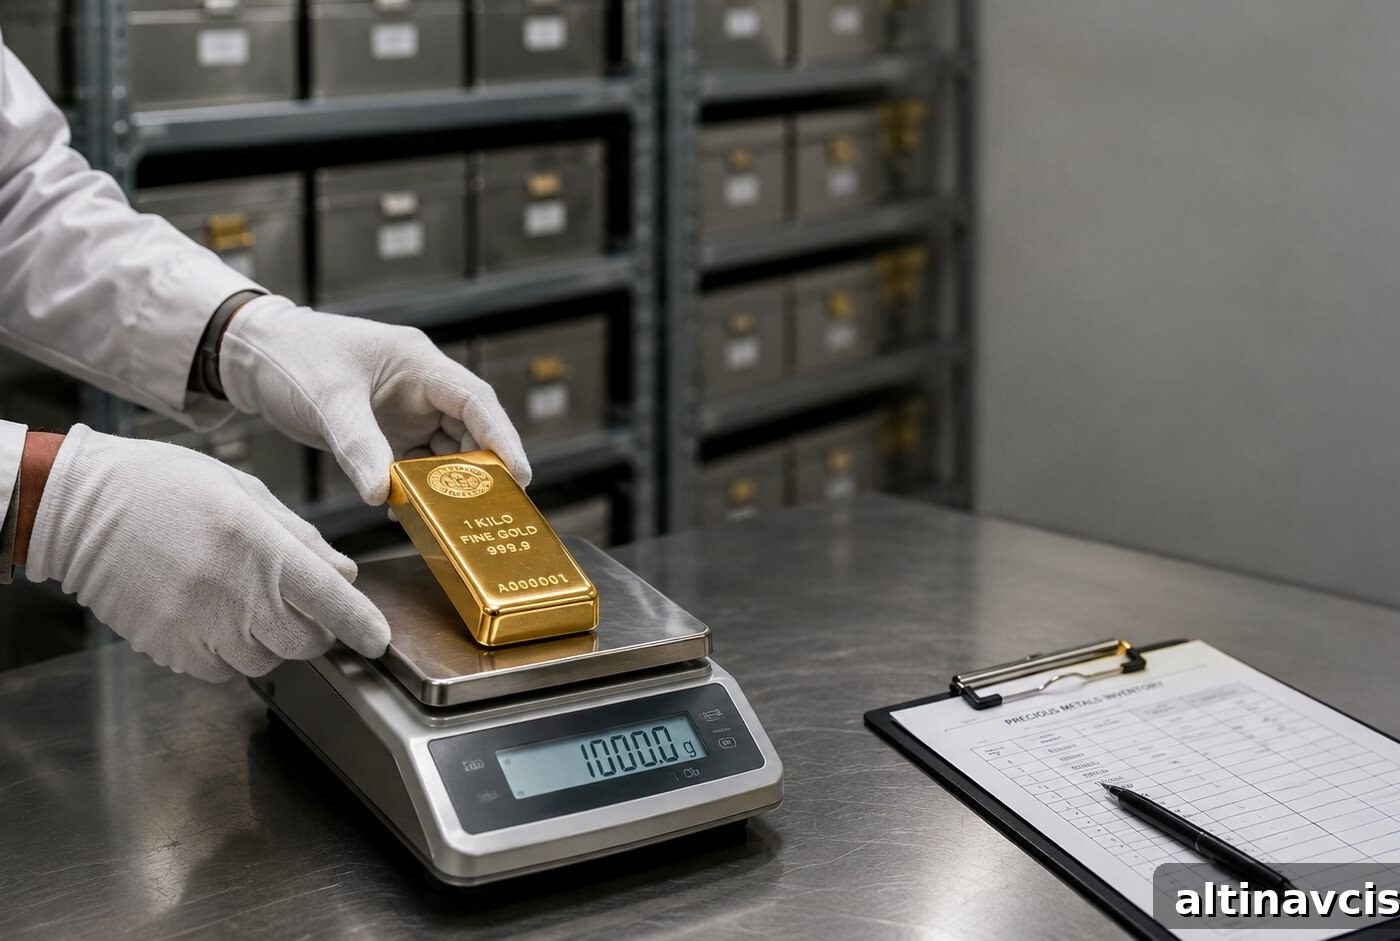
The World Gold Council asked 76 central banks where they keep their gold. The answer contradicts almost every headline you have read this year.
Headlines this year have repeatedly proclaimed that central banks are “bringing their gold home.” The narrative is simple and striking: trust in global institutions is eroding, so nations are flying bullion back to domestic vaults. The World Gold Council decided to check what reserve managers actually did and its 2026 survey tells a different, more useful story.
Where do central banks actually keep their gold?
Most official gold reserves remain stored in foreign vaults, and that fact has not changed. The World Gold Council’s Central Bank Gold Reserves Survey 2026 (published 16 June 2026) collected 76 responses—the largest participation in the survey’s nine-year history. It gives a current, self-reported picture of how conservative institutions manage custody.
The Bank of England is still the most common vaulting location, cited by 57% of respondents. Domestic storage came second at 49%, the Bank for International Settlements third at 16%, and the Swiss National Bank fell to 6% from 12% the previous year. These shares exceed 100% because reserve managers typically split holdings across multiple locations rather than choosing a single vault.
Are central banks repatriating gold or not?
Some central banks are increasing domestic holdings, but slightly more are diversifying into additional foreign jurisdictions. In the 12 months before the survey, 9% of respondents increased domestic storage while 10% added new overseas storage locations. Looking ahead 12 months, 7% intend to increase domestic storage and 9% plan to diversify overseas.
Those figures rose from a low base: the prior year saw only 5% increase domestic storage and 2% diversify overseas. The overseas diversification rate therefore grew faster. This pattern is not a broad “homecoming” but a deliberate diversification of custody—reserve managers are spreading risk across jurisdictions rather than concentrating it in a single place.
Why would a central bank spread its gold across more countries?
Concentration is the risk. Holding a large share of reserves in one jurisdiction exposes those reserves to legal, political and operational risk under that jurisdiction. The freezing of roughly $300 billion of Russian reserves in February 2022 made this clear: assets held under another government’s control can be limited by that government. That lesson prompted many reserve managers to rethink custody.
One simple response is to repatriate everything. A more nuanced response accepts that domestic storage carries its own risks: slower access in a crisis, potential operational constraints, and the challenge of quickly mobilising large volumes. London, by contrast, is the deepest wholesale market where gold can be lent, swapped or sold within hours. Splitting holdings across domestic and foreign vaults reduces single-point legal and operational concentration while preserving liquidity where needed.
What does “earmarked” gold actually mean?
Earmarked gold refers to specific, numbered bars assigned to a named account—bars that are identifiable and held for a particular owner rather than pooled. This distinction matters because it separates legal ownership of physical metal from a creditor claim against an institution.
- Earmarked: The Federal Reserve’s term for gold held on behalf of others; specific bars assigned to account holders.
- Allocated: The commercial-market equivalent meaning you own identified bars and they are your property, not the vault’s.
- Unallocated: A claim against an institution rather than ownership of specific bars; you are a creditor.
- Good Delivery: The London Bullion Market Association standard for weight, purity and certification that makes bars universally tradeable.
The Federal Reserve Bank of New York is explicit: its vault is a custodian for account holders and does not own the gold it stores. That vault contained roughly 507,000 bars weighing 6,331 metric tons as of 2024. The striking reality is that the largest concentration of monetary gold sits in a place where the custodian is clearly not the owner.
What did France actually do with its 129 tonnes?
France did not undertake a political repatriation; it upgraded bar standards. The Banque de France has long worked to align its holdings with the London Good Delivery standard (99.99% purity). About 129 tonnes held in New York did not meet that standard. Instead of physically shipping old bars to Europe, France sold those bars in New York and purchased higher-standard bars in Europe. Its total reserves remained essentially unchanged at roughly 2,437 tonnes. The move was technical and liquidity-driven rather than a symbolic return of sovereign property.
By contrast, Germany still holds a significant tranche—around 1,236 tonnes—at the New York Fed, making it the single largest foreign holding in that vault. Political debate in Germany is ongoing, but the reserves remain in place.
What does this have to do with a private investor?
Everything. The custody question is scale-invariant: the same considerations that guide central banks apply to individuals. The key questions are identical—where does the metal sit, whose books is it on, and what legal or operational barriers could prevent access?
Three practical principles used by institutional reserve managers can be applied by private investors:
- Insist on allocated storage: Own identified bars assigned to you. Allocated holdings are physical ownership; unallocated accounts are promises.
- Understand the custodian: A good custodian clearly records that the stored metal belongs to clients, not to the vault operator.
- Manage concentration risk: Spread holdings across jurisdictions, vaults and custodians to avoid putting control of your asset under a single legal system or counterparty.
These points—allocation, clear custody language, and diversification of location—are the practical application of what central banks are doing and what private holders should consider.
Why does any of this matter over the long run?
The long arc is visible in a single statistic: the New York Fed’s vault held more than 12,000 tonnes of monetary gold in 1973 and about 6,331 tonnes by 2024. That decline began after the United States ended official convertibility of dollars into gold for foreign governments. While gold is unique among reserve assets because it is not anyone’s liability, that advantage only matters if you can access the metal when needed. Custody determines accessibility.
Gold remains attractive for many central banks: in the World Gold Council survey a record 45% of respondents expect their holdings to rise. But the dominant topic for the most conservative institutions over the past year was not how much metal to own, but where to keep it.
Gold traded near recent highs while this piece was prepared. Prices change constantly; custody does not. Custody sits beneath the price and often only matters when someone needs to reach the metal.
People Also Ask
Not currently. The Bundesbank continues to hold roughly 1,236 tonnes at the Federal Reserve Bank of New York, roughly a third of its reserves. Political debate is active, but no formal repatriation programme has been implemented and the gold remains in place.
The Federal Reserve does not own the gold. The New York Fed operates as custodian and guardian for account holders—sovereigns, central banks and official organisations. The gold is earmarked: specific bars are assigned to specific account holders.
Allocated gold means ownership of identified bars recorded as your property, outside the custodian’s balance sheet. Unallocated gold is a claim against an institution rather than ownership of specific metal, making you a creditor of that institution.
Official data show the United States holds the largest official reserve, followed by countries such as Germany, Italy and France. Note that official national holdings are distinct from in-ground mining reserves.
There is no single “safest” place. The criteria that matter are the same at every scale: allocated rather than pooled, segregated rather than commingled, independently audited, insured, and held in a jurisdiction whose legal system you understand. Reserve managers split holdings to avoid concentration risk.
Sources
World Gold Council — Central Bank Gold Reserves Survey 2026; Federal Reserve Bank of New York — Gold Vault (figures as of 2024); Banque de France — 2025 Results; London Bullion Market Association — Good Delivery standards; reporting on France’s transactions in 2025–2026; and contemporary market price reporting.
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Past performance is not indicative of future results. Consult a qualified financial advisor before making investment decisions.
Popular Topics
Picked from the archive
-
01
 Topics
Why Gold Prices Rose While the World’s Top Gold Miner Slumped
-
02
Topics
How Real Interest Rates Drive Gold Prices: Investor Guide
-
03
Topics
Silver Slides While Gold Holds as Markets Reduce Risk
-
04
Topics
Use the 50-Day Moving Average to Read Gold and Silver Trends
-
05
Topics
Five Key Reports Shift Gold Prices and September Fed Pivot Odds
-
06
Topics
3 Fed Officials Voted to Hike Rates: What It Means for Gold
-
07
Topics
Gold Near $4,700: Market Chaos May Be a New Floor
-
08
Topics
Gold Price Nears $5,000 as Silver Approaches $100