Gold Dips, Silver Holds as Iran Diplomacy Hopes Sink Oil Before a Bigger Week
Key takeaways:
- Oil just fell for a fourth straight session. Trump said Sunday he would “probably” meet Iran’s president at the UN this week. That comment alone knocked down oil’s war-risk premium.
- A bigger event lands Wednesday. Xi Jinping arrives in Washington for the first Chinese state visit to the US in a decade. Tariffs and rare-earth export controls both hit the same expiration date, November 10, and Taiwan’s arms package is also on the table.
- Gold and silver are splitting apart today. Two forces are pulling in opposite directions. Diplomacy hopes ease gold’s war premium, while a hawkish Fed keeps real yields high and holds silver up.
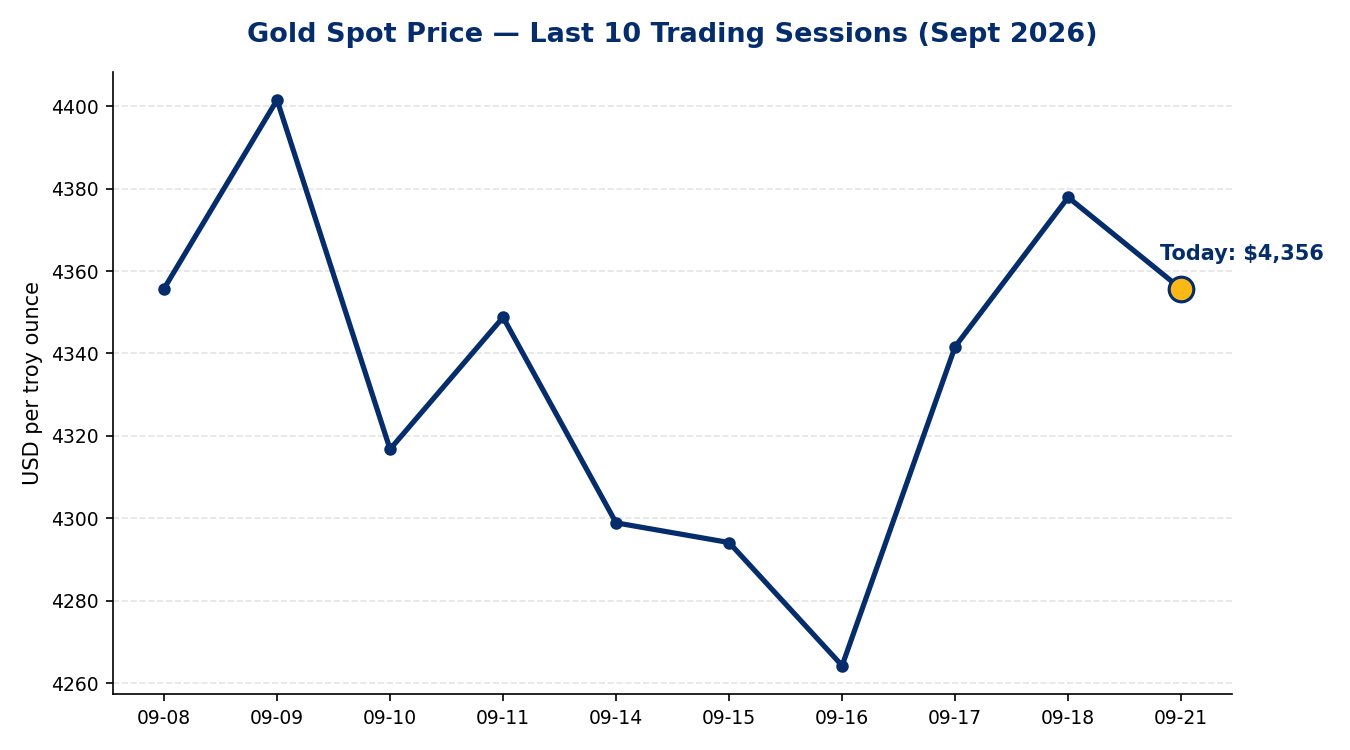
Iran’s president is flying to New York this week. So is China’s leader, to Washington. Gold sits caught between both trips. Gold trades near $4,356 an ounce today, down about half a percent. Silver holds near $66.44, up slightly. That split is rare, and it is the story.
Why Is Gold Slipping While Oil Keeps Falling?
Brent crude has dropped four sessions in a row. It traded near $102 a barrel on Monday, its longest losing streak since June. The cause was one sentence. A reporter asked Trump on Sunday if he would meet Iranian President Masoud Pezeshkian at this week’s UN General Assembly. Trump said he would “probably” be open to it. That single comment did the damage. Add in Saudi progress rerouting crude around a damaged pipeline, and oil fell while risk appetite rose across Asian markets Monday morning.
Gold followed the same logic, but backward. Lower war risk in oil means less reason to fear an inflation spike from energy prices. It also means less reason to hold gold as a geopolitical hedge. That is a small, mechanical drag on the price. It is not a verdict on gold’s longer case.
The Edge Every Investor Needs Smarter precious metals investing starts here. The Nuggets Newsletter brings you essential market insights, Fed updates, global trends, educational videos, and much more.
What Happens at the Trump-Xi Summit on Wednesday?
The bigger catalyst sits in Washington, not New York. Xi Jinping lands Wednesday for the first Chinese state visit to the US since 2015, confirmed this week by China’s own foreign ministry. It follows the two leaders’ Beijing summit in May.
The agenda is packed. Artificial intelligence sits at the top of that list. Two deadlines share the same date, November 10: a tariff truce and China’s rare-earth export controls, both currently suspended, both set to snap back that day unless extended. A $14 billion US arms package for Taiwan is also awaiting approval. Beijing warned weeks ago it could cancel this summit over that package, then let the threat pass; the visit is proceeding as scheduled.
Analysts at the Heritage Foundation and CSIS both expect no durable breakthrough this week. They say success should be measured by whether old commitments hold, not by new ones announced. That is the kind of standoff that has supported gold all year. It is not a crisis. It is a rolling list of deadlines between two giant economies that never quite closes.
Why Does the Fed’s Dot Plot Matter More Than Today’s Headlines?
One number sits under both stories: the real yield. The Fed raised its benchmark rate a quarter point on September 16, to a 3.75%-4.00% range. It was the first hike in three years. That same day, the Fed’s own projections put the median year-end rate at 4.10%, up from 3.80% in June. In plain terms, that signals one more quarter-point hike is likely before December. Sixteen of eighteen Fed officials expect at least one more increase this year.
The 10-year Treasury yield sits near 5.0%. The 10-year real yield is the nominal rate minus expected inflation. It has climbed to 2.68% from 2.62% in the days right after the hike, per Federal Reserve Bank of St. Louis data. Rising real yields usually push gold lower, since they raise the cost of holding a metal that pays no interest. Yet gold is holding near $4,356 anyway. That gap between the textbook reaction and the actual price is worth more attention than either headline event this week.
The Fed’s own forecast puts core inflation at 3.7% by year-end. That is still well above its 2% target, even after a hike built to fight it. Breakeven inflation expectations have sat between 2% and 3% since 2021 and have never fully returned to that target. A central bank keeps hiking into inflation it cannot fully tame. Gold barely dents. That pairing is not random. It suggests the hike itself was already priced into gold weeks ago.
What Is the Deeper Story Here?
The real story this week is not which leader meets which. Gold is holding its ground against two separate de-escalation stories, one in Manhattan and one in Washington. Meanwhile, a hawkish Fed keeps pushing real yields higher. In an earlier cycle, that combination would have been a clean signal to sell gold. Instead, gold is down half a percent while silver is up. The gold-silver ratio has narrowed to roughly 65.6, near its lowest point this month.
That split is the tell. Lower geopolitical risk should pull both metals down together. Only one actually falls. That means something structural is holding the other up. For silver, that something is the same real-yield story moving the whole complex. A tightening ratio does not care whether Trump and Pezeshkian shake hands on Tuesday. For gold, the floor is a question neither summit will answer this week: whether central banks keep leaning away from any single dominant currency, no matter how these meetings end. Gold has no issuer and no counterparty. That is the appeal when the world’s two largest economies cannot agree on rare earths, tariffs, or Taiwan by Thursday’s state dinner, let alone settle any of it by then.
What Should Investors Watch This Week?
Three dates matter more than today’s headlines. Tuesday opens the UN General Assembly’s high-level week. Pezeshkian addresses the chamber, and any Trump meeting would likely get confirmed or denied around then. Wednesday and Thursday bring the Trump-Xi summit itself, including a state dinner already drawing confirmed attendance from Nvidia’s Jensen Huang, OpenAI’s Sam Altman, Apple’s Tim Cook, Qualcomm’s Cristiano Amon, and Microsoft’s Satya Nadella, a sign AI may dominate the room more than tariffs do.
November 10 already sits on the calendar too. That is the single date both the tariff truce and the rare-earth export suspension expire, the real deadline both summits are quietly negotiating around. Check today’s gold and silver prices for the latest levels, and watch the Fed’s rate path alongside it. That mechanism will still be moving prices long after this week’s headlines fade.
Stay On Top of Gold & Silver Prices
Get important market alerts sent straight to your inbox.
SOURCES
1. CNBC: Iranian President Pezeshkian to Head to New York for UN Meeting as Trump Warns of No-Deal Consequences
2. The National: Trump Set for Washington Summit With Xi Focused on Trade, Taiwan and AI
3. Heritage Foundation: Xi Comes to Washington: Expectations for the Trump-Xi Summit
4. Federal Reserve: FOMC Statement and Summary of Economic Projections, September 16, 2026; 10-Year Treasury Yield (DGS10) and 10-Year Real Yield (DFII10) via FRED
5. South China Morning Post: Chinese President Xi Jinping Will Pay State Visit to US This Week, Beijing Confirms
6. Bloomberg: White House Invites Microsoft, OpenAI, Nvidia CEOs to Trump-Xi State Dinner
7. The White House: Fact Sheet — President Trump Strikes Deal on Economic and Trade Relations With China
8. Price benchmarks per CME Group and LBMA spot references.
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Past performance is not indicative of future results. Always consult a qualified financial advisor before making investment decisions.