Silver IRA Guide: Rules, Contribution Limits and Custodians
Key Takeaways
- A Silver IRA holds physical silver bullion inside a self-directed IRA — not ETFs, futures, or mining stocks — giving you tax-advantaged ownership of a tangible asset.
- The IRS requires silver to meet a minimum fineness of .999 and be held by an approved custodian in an approved depository; home storage is a prohibited transaction with severe tax penalties. (IRS IRC §408(m))
- Contribution limits apply across all your IRAs combined, with a catch-up amount for investors age 50 and older; check current IRS guidance for yearly limits. (IRS Publication 590-A)
- Total annual fees on a $50,000 Silver IRA typically range $450–$600 with segregated storage — higher than ETFs, but the premium buys physical ownership, tax-deferred growth, and an asset outside the banking system.
- Silver serves dual roles: a monetary store of value and a critical industrial input for solar panels, electric vehicles, and electronics, creating distinct and complementary demand drivers.
Your Gold Buying Guide Most investors overpay when they buy gold and then overpay again when they sell. This guide explains what to own and why.
Guide request form removed for clarity. Visit the publisher’s site to download the guide.
What Is a Silver IRA?
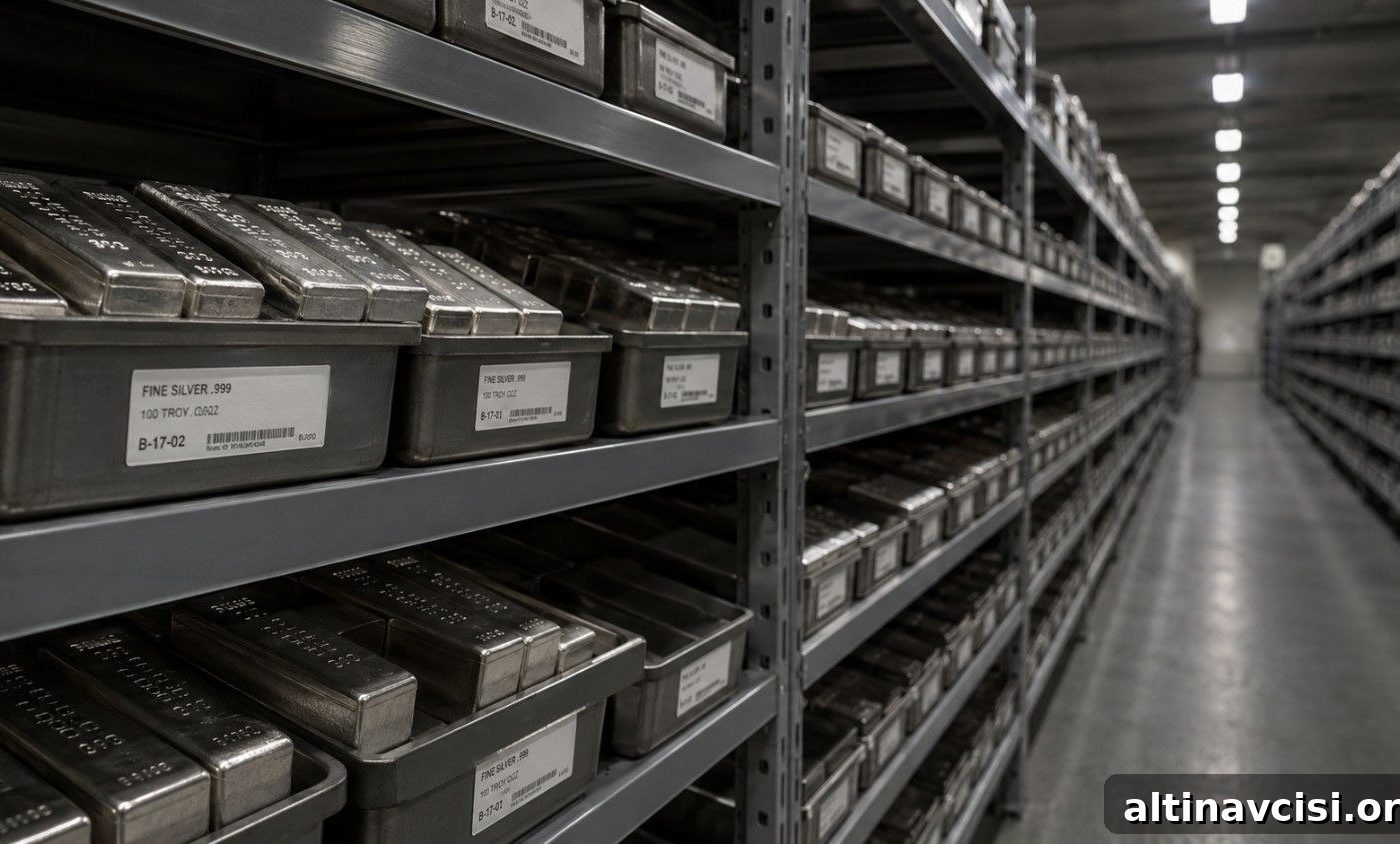
A Silver IRA is a self-directed Individual Retirement Account (SDIRA) that holds physical silver bullion rather than stocks, bonds, or mutual funds. The account holds actual bars and coins in an approved vault, not futures contracts, mining shares, or exchange-traded products. An approved custodian holds the metal on your behalf until retirement.
This physical distinction matters: paper silver instruments carry counterparty risk because they depend on another party to perform. Properly structured physical silver in an IRA eliminates that type of counterparty exposure — the metal is physically present and owned within the IRA wrapper.
What Are the Silver IRA Rules Set by the IRS?
The IRS enforces four core requirements for silver IRAs.
1. Purity Requirement
Silver placed in an IRA must have a minimum fineness of .999 (99.9% pure). Most investment-grade bars and coins meet or exceed this standard. Coins with lower silver content — for example, pre-1965 U.S. “junk silver” at 90% — and numismatic pieces valued for rarity rather than metal content do not qualify.
2. Approved Coins and Bars
Beyond purity, eligible coins must come from a national mint and eligible bars from accredited refiners, assayers, or manufacturers. Commonly accepted coins and bars include:
- American Silver Eagle (1 oz, .999 fine)
- Canadian Silver Maple Leaf (1 oz, .9999 fine)
- Austrian Silver Philharmonic, Australian Silver Kookaburra and Koala, British Silver Britannia (typically .999 fine)
- Investment-grade bars from accredited refiners such as Sunshine, PAMP Suisse, Credit Suisse, and recognized historic refiners
Products not on the approved lists cannot be held in an IRA. These rules have been in effect since the IRS clarified precious metals treatment in the late 1990s.
3. Custodian Requirement
A Silver IRA requires a qualified custodian. You cannot use a regular brokerage account as an IRA holding physical metals. Self-directed IRA custodians handle compliance, custody arrangements, and IRS reporting for precious metals IRAs. The investor directs purchases; the custodian holds the account and files the required tax forms.
4. Storage Rules — No Home Storage
The IRS mandates storage of IRA precious metals at an approved depository. Home storage is treated as a prohibited transaction and can trigger full taxation of the IRA’s value plus penalties. Approved storage options typically include specialized, insured depositories and international vault operators.
Depositories generally offer two options: commingled storage, where your metal is stored with other clients’ holdings at lower cost, and segregated storage, where your assets are kept separate and identified specifically to you for an extra fee.
What Are the Silver IRA Contribution Limits?
Silver IRAs follow the same annual contribution limits that apply to traditional and Roth IRAs combined. These limits are subject to change each tax year and include a catch-up contribution allowance for investors age 50 and older. Contribution limits apply across all IRAs you hold; consult current IRS guidance for the exact figures for the tax year in question.
Traditional IRA contribution deductibility may phase out at higher incomes if you or your spouse participate in an employer retirement plan. Roth IRAs have income eligibility thresholds that can limit direct contributions.
Traditional vs. Roth Silver IRA: Which Is Better?
Both account types hold the same physical silver; the key difference is tax treatment and timing:
Traditional Silver IRA
- Contributions may be tax-deductible today.
- Assets grow tax-deferred inside the account.
- Withdrawals in retirement are taxed as ordinary income.
- Required Minimum Distributions (RMDs) begin at the ages specified by current law.
- Often preferred by those who expect lower taxes in retirement.
Roth Silver IRA
- Contributions are made with after-tax dollars.
- Qualified withdrawals in retirement are tax-free.
- No RMDs during the original owner’s lifetime.
- Income limits determine eligibility for direct contributions.
- Often preferred by investors who expect equal or higher tax rates in retirement or who want to avoid RMDs.
If you expect the metal’s purchasing power to be significantly higher in the future, paying tax now on a smaller contribution (Roth) and taking tax-free distributions later can be advantageous.
How Do You Open a Silver IRA?
Opening a Silver IRA involves a few additional steps compared with a standard brokerage IRA, but each is straightforward:
- Choose a custodian. Compare setup fees, annual administration fees, and storage costs. Request a full, written fee schedule before committing.
- Fund the account. You can contribute using annual IRA contributions, complete a custodian-to-custodian IRA transfer, or perform a direct rollover from an eligible 401(k) or other employer plan.
- Select eligible silver. Work with a dealer to choose IRS-eligible coins or bars; the custodian purchases and directs delivery to an approved depository.
- Depository storage. The depository receives, verifies, and stores the metal; you receive statements showing holdings.
- Ongoing maintenance. The custodian files required IRS forms each year. At retirement you may take a cash distribution (liquidating the metal) or, if permitted, an in-kind distribution of physical silver taxed at fair market value on the transfer date.
Silver IRA: Typical Annual Fee Ranges
Based on a $50,000 account — total annual cost typically $450–$600 with segregated storage. Fees vary by custodian and service level.
Typical fee categories include one-time setup fees, annual custodian administration, storage (commingled or segregated), and transaction fees for trades and distributions. Factor these ongoing costs into your decision when comparing physical ownership versus exchange-traded alternatives.
Fee examples reflect common industry ranges; individual custodians may charge more or less.
On a $50,000 account, typical custodian and segregated storage fees run roughly 0.9%–1.2% annually. By contrast, many silver ETFs have lower expense ratios and no storage fees. The higher cost of a Silver IRA buys physical ownership, tax-advantaged growth, and an asset held outside the banking system — benefits that some investors find worth the premium.
Why Does Silver Belong in a Retirement Account?
Answering “inflation hedge” alone misses the full case. Silver uniquely serves two distinct demand structures simultaneously:
Monetary demand: Silver has long functioned as money and can preserve purchasing power when fiat currencies weaken. It cannot be created by a central bank’s ledger entry.
Industrial demand: A substantial portion of annual silver demand is industrial — solar panels, electric vehicles, electronics, and medical devices — providing a growing consumption base that differs from gold’s largely monetary demand. This industrial floor can support long-term demand as energy technologies scale globally.
Supply-side constraints matter too: mine production typically increases slowly, and new mine development takes years, which can create structural imbalances when industrial and monetary demand rise faster than supply.
Is a Silver IRA Right for Everyone?
No. Consider the downsides candidly: higher fees than ETFs, price volatility, less immediate liquidity, and no income generation while the metal sits in storage. Silver is typically a preservation tool — it protects purchasing power you already own rather than generating compound returns like income-producing investments.
A Silver IRA can make sense as part of a diversified retirement portfolio, often in the range many advisors suggest for precious metals (for example, a modest allocation). Investors who prefer gradual accumulation can dollar-cost average into a position rather than deploying a large lump sum.
Stay On Top of Gold & Silver Prices
Receive market updates and alerts to your inbox.
Subscription form removed. Sign up on the publisher’s site to receive alerts.
People Also Ask
Can I Convert an IRA or 401(k) Into a Silver IRA?
Yes. You can fund a Silver IRA via a direct rollover from a former employer’s 401(k) or by a custodian-to-custodian transfer from an existing IRA. These moves, when executed directly between institutions, generally avoid taxes and penalties. Indirect rollovers are possible but require redeposit within 60 days and may involve mandatory tax withholding that you must replace to avoid tax consequences.
Do I Receive the Physical Silver at Retirement?
At retirement you typically have two options: the custodian can liquidate the silver and distribute cash, or you may request an in-kind distribution of the physical metal if your custodian and plan rules permit. In-kind distributions are taxed at fair market value on the transfer date.
Is a Silver IRA Safe in a Financial Crisis?
Physical silver held at a regulated depository and stored segregated from a custodian’s balance sheet is your property and would generally survive a custodian bankruptcy. However, the IRA remains a tax-advantaged vehicle subject to U.S. tax and regulatory rules, so broad policy changes are theoretical risks to the framework itself. For those seeking ownership entirely outside the financial system, direct private ownership is the alternative.
How Much of My Portfolio Should Be in a Silver IRA?
There is no universal percentage. Common guidance places precious metals between 5% and 20% of retirement assets depending on risk tolerance, conviction about monetary risk, and time horizon. Silver’s higher volatility suggests a gradual approach to building a position.
Can I Add Silver to My IRA After the Initial Purchase?
Yes. A Silver IRA is an ongoing account. You can make annual contributions up to IRS limits, perform transfers and rollovers, or use cash already in the account to buy additional eligible silver through your custodian.
What Most Silver IRA Guides Don’t Tell You
Many guides are produced by sellers and emphasize buying now. The IRS opened IRAs to certain precious metals in the late 1990s, creating a vehicle that mixes paper-system tax benefits with ownership of a physical asset. That design has trade-offs: tax efficiency and storage requirements, contribution limits, custodian involvement, and purity standards. Whether those trade-offs are advantages or drawbacks depends on your objective: inflation protection within the tax code, or complete independence from financial infrastructure.
For investors focused on protecting purchasing power from monetary inflation, a Silver IRA is a rational, sanctioned tool. For those seeking absolute separation from the financial system, direct private ownership of metal is the more appropriate choice.
SOURCES
1. US Bureau of Labor Statistics — CPI Inflation Calculator (BLS data).
2. Internal Revenue Code provisions and IRS guidance on retirement accounts and precious metals (e.g., IRS publications on IRAs and rollovers).
3. Taxpayer Relief Act of 1997 and subsequent IRS clarifications regarding precious metals in IRAs.
4. Industry publications and silver market surveys documenting industrial demand and supply balances (industry surveys and World Silver Survey reports).
5. Historical silver price data and market observations from public market data providers.
Disclaimer: This article is for informational and educational purposes only and does not constitute investment advice. Consult a qualified financial adviser before making investment decisions.
You may also like:
- Silver’s Tesla Moment: The Solid-State Battery Thesis
- Physical Gold vs. Digital Gold: Which Is the Ultimate Safe Haven?
- BRICS Is Hoarding Gold — What It Means for Portfolios
- Gold to Oil Ratio: A Practical Guide for Analysis
- Dollar-Cost Averaging Into Gold and Silver: A Practical Guide
- The Silver-to-Dow Ratio: How to Spot a Shift from Paper to Physical
- What Moves Gold Prices? Six Key Factors Explained
Popular Topics
Picked from the archive
-
01
 Topics
US Economy at a Crossroads: Jobs Stall as Inflation Persists
-
02
Topics
How $1 Trillion in Debt Interest Is Driving Gold Prices
-
03
Topics
Gold Prices Slip After Rally as Fed Rate Cut Looms
-
04
Topics
Trump Threatens EU With 250% Tariffs on Pharmaceuticals
-
05
Topics
China’s PBOC Adds to Gold Reserves for Ninth Month
-
06
Topics
Gold’s Center of Gravity Shifted East: 5 Stories That Prove It
-
07
Topics
Gold Royalties Surge as Miners Struggle with Rising Costs
-
08
Topics
Gold Surges to Record High as $5,000 Target Nears