How Gold Prices Are Determined: East-West Market Forces
For nearly a century, gold has shifted in a clear pattern between Western financial markets and Eastern physical holders. Below is a concise explanation of how that flow works, why it has mattered for investors, and how the dynamics are changing today.
Key Takeaways
- Gold’s large above-ground stock and modest annual mine production give it a very high stock-to-flow ratio; who owns the metal matters more than new supply.
- Western financial institutions tend to set the marginal price; Eastern physical buyers absorb weakness and often sell into strength.
- London clears the wholesale market, Switzerland recasts bars between formats, and New York’s COMEX is the delivery point for futures.
- The historical correlation between real yields (10-year TIPS) and gold was extremely strong for years but has broken down since 2022.
- Central bank buying has been unusually large since 2022, changing the structural demand picture for gold.
Most investors know simple rules of thumb: gold often rallies when the dollar weakens or when real interest rates fall. Fewer understand the market’s physical and institutional plumbing — and that plumbing largely explains how and why prices move. Jan Nieuwenhuijs’s research mapped this architecture and showed a recurring east-west tide over roughly 90 years. That tide remains one of the most useful frameworks for anyone investing in physical gold or paper proxies.
Why Gold Moves Differently From Other Commodities
Unlike oil, wheat, or copper, gold is not driven primarily by annual production changes. There are roughly 208,000 tonnes of gold above ground, and annual mining adds only about 3,500 tonnes. That produces a stock-to-flow ratio near 60: annual output is small relative to the existing stock. As a result, new production rarely shifts the long-term supply picture. Price is determined more by who holds the metal, who is willing to trade it, and where major clearing hubs will settle those trades.
Because of that, gold behaves more like a currency or a reserve asset than a conventional industrial commodity. It is moved, recast, reallocated and stored across a global network of vaults, custodians, refineries and exchanges. Those flows of custody — not just mine output — are the primary drivers of price.
How the West Sets the Gold Price
In Western markets, gold competes with paper assets for investor attention. The single most important comparison is to real yields — the inflation-adjusted return on safe government bonds. When real yields fall or remain very low, the opportunity cost of holding non-yielding gold declines, and institutional buyers move in. When real yields rise, gold can be less attractive and institutional selling tends to increase.
For many years this relationship was extremely reliable: a strong inverse correlation existed between gold and 10-year TIPS. Institutional flows — hedge funds, ETFs, pension funds and bullion banks — respond to those signals and trade large volumes of paper and physical metal. London is the global hub for wholesale settlement, Switzerland converts bars into different formats for delivery, and COMEX in New York is the main futures delivery venue. This London-Switzerland-COMEX triangle forms the backbone of Western gold mechanics.
Why Eastern Demand Absorbs Gold When Prices Fall
Eastern buyers — particularly in China, India, Southeast Asia and parts of the Middle East — approach gold as savings, cultural wealth and insurance rather than as a liquid portfolio allocation. Gold there is often family wealth, wedding money, or a store of value outside the banking system. As a result, Eastern demand tends to be patient and price-sensitive.
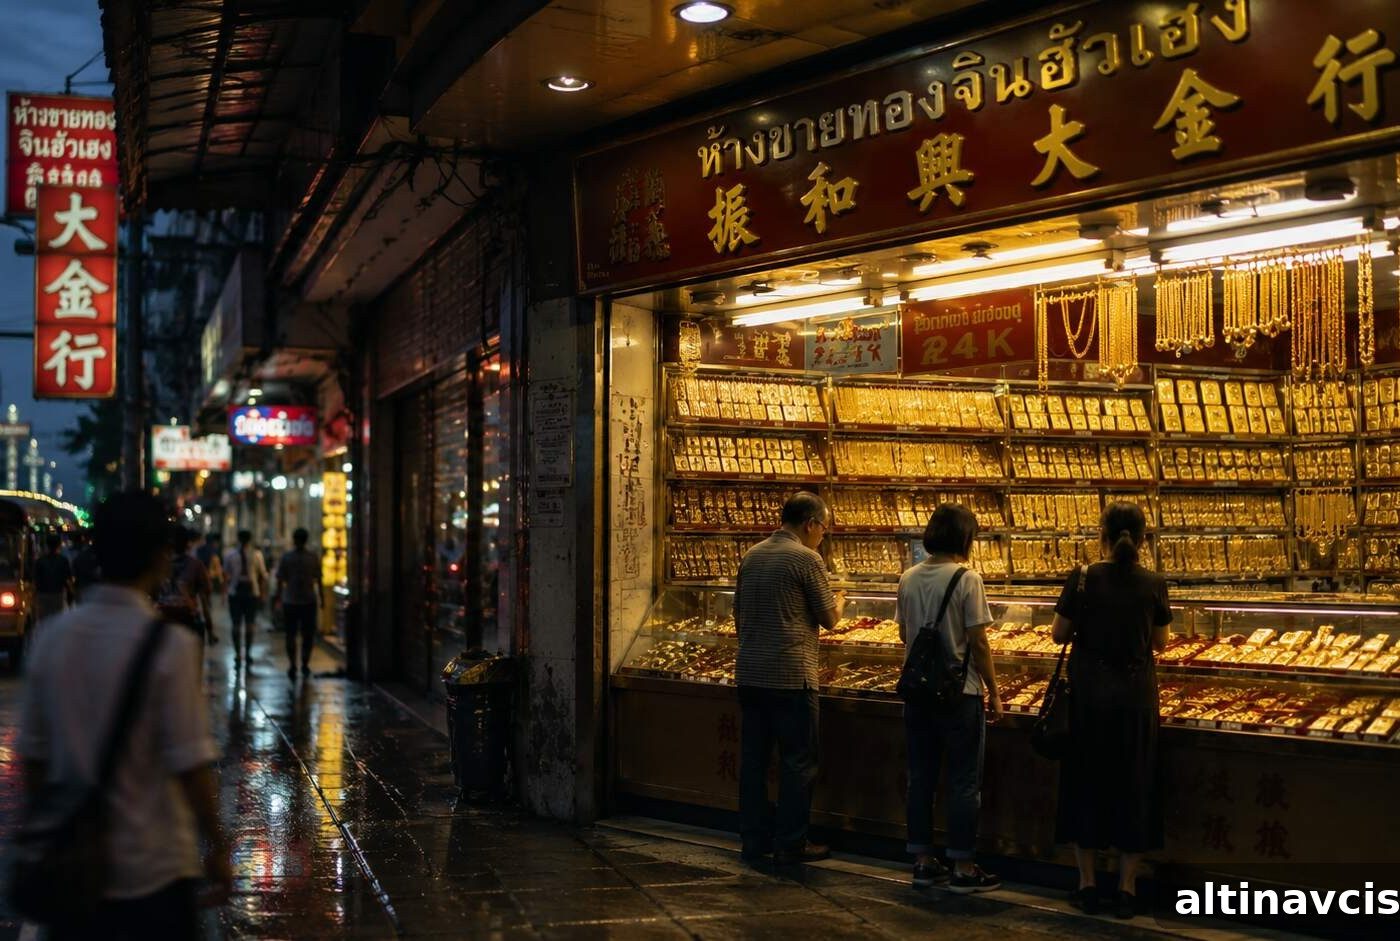
When prices spike, retail and household holders in these regions sometimes sell to lock in gains. When prices fall, demand returns as buyers quietly accumulate physical metal at prices they judge fair. Street-level markets such as Bangkok’s Yaowarat district make this behavior visible: gold shops act as small household balance sheets where queues form to sell at highs and to buy at dips. That pattern makes Eastern demand the market’s ballast: the West generates directional momentum, and the East often absorbs corrections.
People Also Ask
Is gold a commodity or a currency?
Exchanges list gold as a commodity, but its market behavior and store-of-value role make it function more like a currency or monetary reserve. Price is governed primarily by ownership and custody flows rather than annual production cycles.
Why do gold prices rise when real interest rates fall?
Gold yields nothing. When inflation-adjusted interest rates fall, the opportunity cost of holding gold decreases, making it relatively more attractive versus yield-bearing instruments. That relationship explained much of gold’s price action for many years, though other structural factors have altered its strength since 2022.
Why are central banks buying so much gold?
Two structural developments have driven large central bank purchases. First, geopolitical events in 2022 highlighted that sovereign foreign-currency reserves held in another jurisdiction can be frozen or restricted, while physical gold held outside custodial claims cannot be immobilized in the same way. Second, many emerging-market and Asian central banks have diversified reserves away from heavy dollar concentration. The result has been unusually large official-sector demand since 2022.
What does London actually do in the gold market?
London is the global clearing center for wholesale physical gold. Institutional flows, custody transfers and bullion-bank settlement are concentrated there. UK net gold import and export figures therefore provide a clear window into where Western professional money is positioned: when Western institutions want metal, London imports and stores it; when they sell, London becomes a distribution point.
London’s Role in the Global Market
Even though the UK is not a major mining country, London’s vaults and wholesale market are central to global price discovery and settlement. The COVID-19 disruption in 2020 showed how crucial physical logistics are: flight suspensions and refinery slowdowns created a premium on futures versus spot because metal could not be moved quickly enough for delivery. That episode was a reminder that electronic trading ultimately depends on someone moving bars in the real world.
Gold’s historical correlation with real yields has weakened
The strong inverse correlation that existed between gold and 10-year TIPS through 2005–2021 has collapsed since 2022, reflecting large central bank purchases and structural reserve diversification.
- 2005–2021: Strong inverse correlation (historically reliable)
- 2022–2023: Correlation collapsed as central banks became major buyers
- 2024–present: Correlation remains structurally lower; a new demand floor has emerged
Why the Real-Yield Relationship Has Changed
From 2022 onward, higher real yields did not produce the magnitude of gold declines that prior decades would have predicted. Two main forces explain this shift: accelerated central bank purchases — particularly among emerging-market and Asian banks — and a global reassessment of reliance on dollar-denominated reserves after 2022 events that demonstrated how foreign assets can be restricted. Together these forces create a structural bid under gold that reduces its sensitivity to short-term moves in real yields.
Implications for Investors
Investors should still watch real yields and the dollar, but those indicators no longer tell the whole story. Gold is transitioning toward a broader role as a strategic reserve asset rather than purely a tactical inflation hedge. Official-sector accumulation is structural and multi-year, which means periods of rising real yields may no longer trigger the same scale of selling they once did.
For individuals holding physical metal, the East-West framework remains useful. Eastern physical demand historically provides a durable floor by absorbing dishoarding from Western institutions. That dynamic, combined with a larger official-sector bid, suggests a thicker base of long-term demand beneath the market.
Practical Takeaways for Individual Investors
If you hold physical gold, prioritize custody, provenance and understanding why you own it. The market is increasingly driven by structural reserve decisions and by concerns about the credibility of paper-based monetary claims. Physical holders who understand the mechanics and who secure their metal appropriately will be better positioned than those who rely solely on paper proxies.
Gold has acted as a monetary anchor across centuries. The current east-west tide is a continuation of that long history — now unfolding in a financial system where reserve composition and geopolitics matter more than ever. Own the metal for the right reasons, understand the forces at work, and remain focused on long-term preservation of purchasing power rather than short-term price noise.
Sources
1. Jan Nieuwenhuijs — The West-East Ebb and Flood of Gold (research summary)
2. RBC Wealth Management — analysis of gold’s correlation with real yields
3. J.P. Morgan Private Bank — commentary on gold and central-bank demand
4. World Gold Council — data on central bank purchases and demand trends
5. London Bullion Market Association — guidance on wholesale settlement and good delivery standards
6. CME Group — information on gold futures and COMEX delivery practices
Disclaimer: This article is for informational purposes only and does not constitute financial or investment advice. Always consult a qualified financial adviser before making investment decisions.
You may also like:
- Does Physical Gold Have Counterparty Risk? The Facts
- Why Is Gold Still a Safe Haven? Insights from Major Refiners
- Rate Hike Odds and Gold: Why Prices Rise Even as Rates Shift
- Could Governments Confiscate Gold Again? Historical Context
- Gold Price History: A Century of Change
- The Debasement Trade Explained: Mechanism and History
- Gold or Silver First? A First-Time Buyer’s Framework
- Gold Reserves by Country: Recent Rankings
- Gold Portfolio Allocation: How Institutions Are Rethinking 60/40
- What the SILVER Act Means for Precious Metals Investors
The Knowledge That Changes Everything
Two essential guides — yours free. Understand why gold matters and why fiat currencies historically lose purchasing power.
Popular Topics
Picked from the archive
-
01
 Topics
Why BRICS Nations Are Stockpiling Gold
-
02
Topics
Gold Prices Fall to Seven-Month Low as Geopolitical Fear Fades
-
03
Topics
CPI-Adjusted Silver vs Spot Price: What the Ratio Reveals
-
04
Topics
Shutdown Nears Deadline as Gold Soars 12% in September
-
05
Topics
Gold Price Up 1.5% as ADP, ISM and Beige Book Weigh on Fed
-
06
Topics
Silver vs Gold 2026-2031: 5-Year Investment Outlook
-
07
Topics
US Jobless Claims Jump to 3-Month High, Point to Labor Softening
-
08
Topics
How Fed Pause and Rising PPI Affect Gold Prices